
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SLB (SLB) Wins Fresh Contracts, Is The Stock Still Cheap?
Why the latest contract wins matter for SLB
SLB (SLB) has picked up fresh attention after securing new work in Oman, the North Sea and Zimbabwe, a cluster of contract wins that puts its global project pipeline back in focus for investors.
These contracts arrive after a strong run, with SLB’s share price up 29.03% year to date and the 1-year total shareholder return at 53.53%. However, the 30-day share price return has eased 3.94%, suggesting shorter term momentum has cooled while the longer term trend remains positive.
Spot similar contract driven stories across the sector by scanning the 39 power grid technology and infrastructure stocks.The pullback from recent highs now sits against a long stretch of stronger returns and a fresh run of contract wins for SLB. Does that set up a reasonable entry today, or reward the patient investor who waits for a better price before committing new capital as valuation comes into focus next?
Most Popular Narrative: 16% Undervalued
SLB last closed at $51.87, while the most followed narrative points to a fair value of about $61.39. This frames the stock as trading at a discount and puts the focus squarely on how its mix of energy technology and services could support that gap.
The integration of ChampionX expands SLB's capabilities in production optimization, chemicals, and digital production technology, unlocking new revenue synergies through cross-selling and international expansion, while also driving significant cost synergies ($400 million targeted). All of these factors are expected to increase EBITDA margins and earnings per share, notably in 2026 and beyond.
See why 156 investors see SLB as 16% undervalued.
Result: Fair Value of $61.39 (UNDERVALUED)
Still, the SLB story can wobble if global upstream budgets soften further or if the ChampionX integration delivers slower or smaller cost and revenue benefits than expected.
Find out about the key risks to this SLB narrative.
Another View on SLB’s Valuation
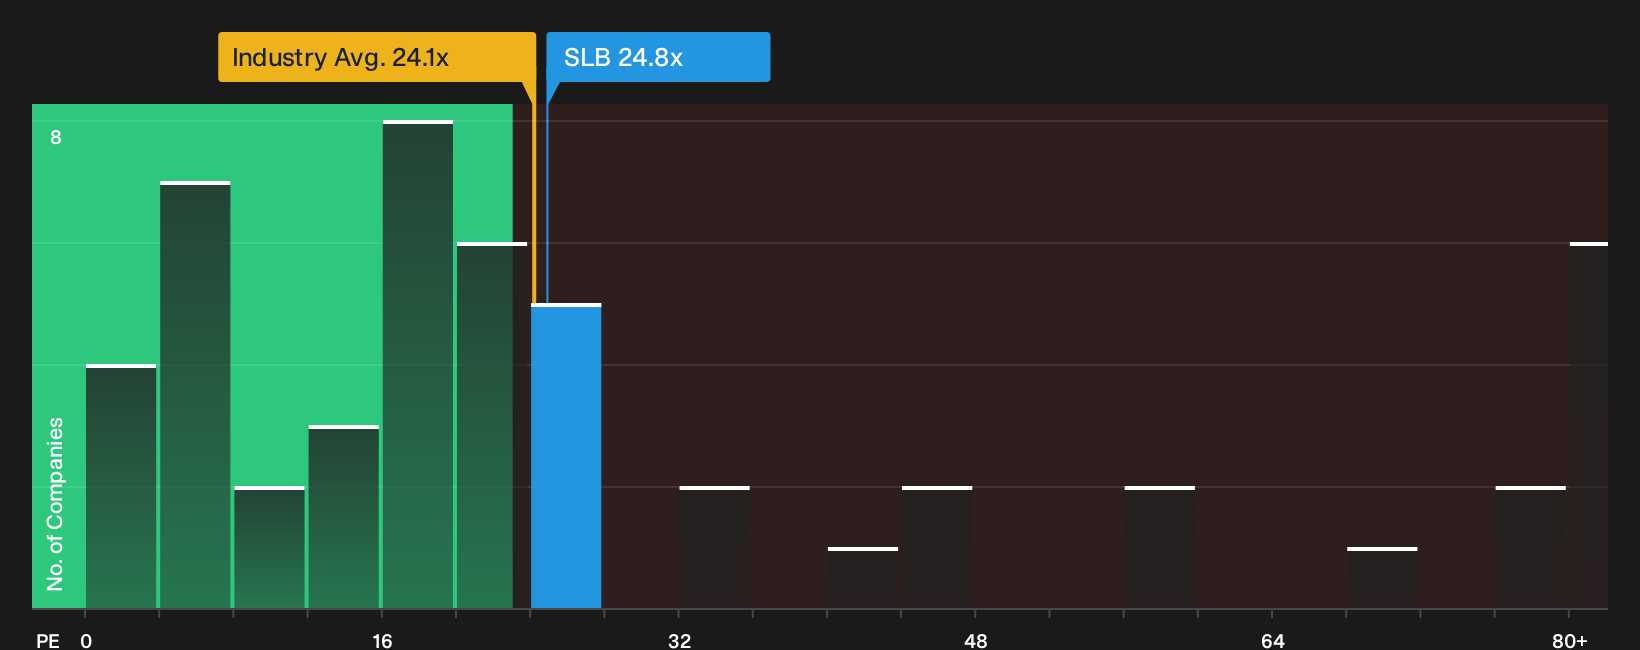
The earlier fair value narrative leans on analyst targets and earnings forecasts. A simple P/E check paints a different picture. SLB trades at 24.8x earnings, which is slightly richer than the US Energy Services industry at 24.1x, yet below a 33.9x peer average and near a 25.8x fair ratio. That mix hints at some valuation support, but also suggests the margin for error is not huge if expectations reset.
For a closer look at how these earnings multiples stack up against the underlying fundamentals, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the SLB story so far. If you want to move quickly and judge the balance for yourself, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond SLB?
If SLB has your attention today, do not let that narrow your field of vision. Fresh ideas often come from scanning beyond the obvious candidates.
- Target dependable income streams by reviewing the 7 dividend fortresses that can help anchor your portfolio when sentiment swings.
- Hunt for quality at a reasonable price with the 30 high quality undervalued stocks that filters for stronger fundamentals and potential mispricing.
- Guard against portfolio shocks by focusing on the 31 resilient stocks with low risk scores that screens for sturdier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com