
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What TD SYNNEX (SNX)'s AI Infrastructure Partnership Means For Shareholders
- Hammerhead AI recently announced a collaboration naming TD SYNNEX as distributor for its ORCA software, giving the distributor a packaged way to help data centers convert stranded power into AI-ready capacity through a standardized MW SKU aimed at neoclouds, AI providers, colocation operators, and enterprises.
- The agreement ties directly into TD SYNNEX's Destination AI program, linking its reseller network and integration capabilities to demand for power-efficient AI infrastructure as operators look to support new workloads without waiting for grid upgrades.
- This article examines how TD SYNNEX's investment narrative is influenced by this AI data center power orchestration partnership and by its upcoming earnings.
Scan beyond TD SYNNEX and this Hammerhead AI deal by lining up distributors and infrastructure players exposed to the same power bottleneck theme through 85 AI infrastructure stocks.
TD SYNNEX Investment Narrative Recap
To own TD SYNNEX, you need to believe its role as a large IT and AI infrastructure aggregator can keep attracting workload volume, even as hardware margins stay tight and as-a-service models grow. The Hammerhead AI partnership fits that view by leaning into power constrained data centers, although it does not remove core issues like margin pressure and customer concentration.
The near term swing factor is the upcoming earnings report, with expectations for revenue growth above 20% year on year. That report will show whether recent demand pull forward is easing into a softer patch. The main risk remains weaker purchasing patterns and compressed gross profit if volumes reset while costs stay sticky.
Of the recent developments, the earnings preview for Thursday is most relevant. The market is looking for more than 21% revenue growth year on year and watching whether TD SYNNEX can keep translating strong top line into steady profit, given its 1.6% net margin and debt that is not well covered by operating cash flow.
If results land close to those expectations, the Hammerhead AI agreement gives investors another concrete example of how TD SYNNEX is leaning into complex data center and AI workloads, where integration and services matter. If demand or margins soften, this kind of AI focused offering may still be seen as helpful, but not enough to offset cyclical pressure in broader hardware and distribution volumes.
TD SYNNEX's current analyst storyline points to US$90.7b in revenue and US$1.6b in earnings by 2029. This would represent 9.1% yearly top line growth and an earnings increase of about US$0.5b from the US$1.1b reported today.
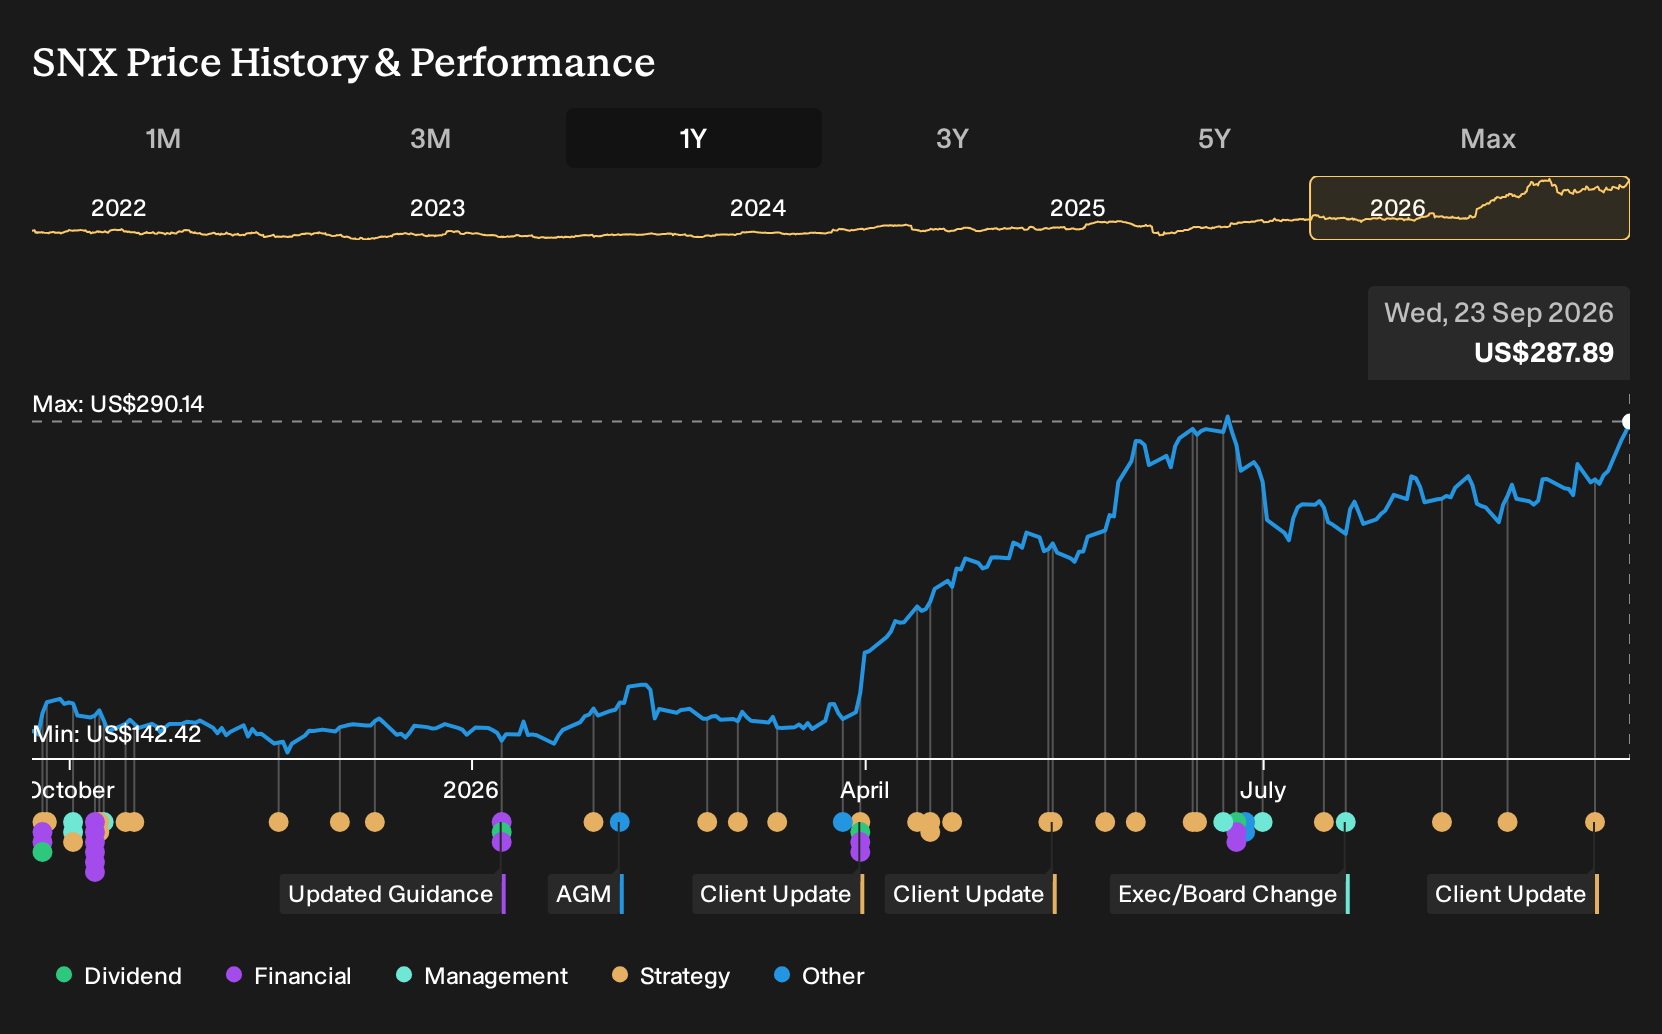
Uncover why TD SYNNEX's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might see the Hammerhead AI news as a potential offset to one big concern in the alternate view. The most pessimistic analysts worry that Hyve’s heavy reliance on two hyperscale clients leaves TD SYNNEX exposed if AI data center build plans slow. Their models only assume 7.7% yearly revenue growth and US$87.2b by 2029, so they paint a cooler picture than the consensus. Since both narratives were built before this announcement, you can treat today’s power orchestration partnership as a new test case and explore which version you find more convincing.
Explore 2 other TD SYNNEX fair value estimates, including one that suggests it could be worth just $333.55.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your TD SYNNEX research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TD SYNNEX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TD SYNNEX's overall financial health at a glance.
Looking for more TD SYNNEX style investment ideas?
If the TD SYNNEX story has you thinking about where else reliable cash flows, balance sheets, or dividend streams might show up, the Simply Wall St Screener can help you line up fresh ideas that fit your own risk and return preferences.
- For investors who want a mix of income and resilience, consider filtering for sturdy payers through 7 dividend fortresses that can help anchor a long term portfolio.
- If capital protection and steadier profiles matter most to you, scan a 31 resilient stocks with low risk scores and see which businesses line up with your comfort zone.
- When the goal is to look for robust finances without overpaying, start with a 16 high quality undiscovered gems that combine solid fundamentals with less crowded attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com