
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Newell Brands Stock Could Change Following Atlanta Design Center Opening
- Newell Brands has opened a nearly 37,000 square foot multi site Design Center in Atlanta, integrating industrial and brand design, advanced visualization, AI supported prototyping, and dedicated consumer UX labs such as Kitchen UX Lab and Kids UX Lab.
- The Crock Pot Brand collaboration with Valspar links countertop appliance colorways to coordinated paint palettes, signaling a push to turn design led kitchen products into anchors for deeper consumer engagement across the wider home.
- Next, the focus will be how Newell Brands' Atlanta Design Center could influence the existing investment narrative around product innovation.
Newell Brands Investment Narrative Recap
To own Newell Brands, you need to believe that product refresh, brand work and cost discipline can turn a US$7.2b revenue base and current losses into steadier cash generation over time. The Atlanta Design Center fits that story, since it concentrates design, UX research and prototyping around core labels that analysts already expect to do more of the heavy lifting.
In the near term, the key catalyst is whether product initiatives and omni channel execution start to show up in more resilient core sales while leverage gradually eases from a reported 5.5x. The biggest risk remains weak category demand, especially in discretionary items, combined with high interest costs and a dividend that is not covered by earnings or free cash flow.
The Crock Pot Brand and Valspar Color Drenched Kitchen Collection looks most directly tied to that thesis. It takes design led thinking from the Atlanta hub and puts it into a concrete launch that aims to link a countertop appliance with the broader kitchen look, which aligns with Newell Brands’ push toward premium household products.
For catalysts, this collaboration is a test of whether Newell Brands can turn design centric releases into better pricing power and retailer support without pushing volumes down. Execution risks remain around consumer price sensitivity, private label competition and the firm’s leverage, so investors will likely watch how frequently similar cross brand campaigns appear and whether they coincide with any change in category performance.
Newell Brands' current analyst script points to US$7.7b in revenue and US$557.1 million in earnings by 2029. That path assumes revenue growth of 1.9% a year and a swing in earnings of roughly US$778 million, from a loss of US$221.0 million today to the 2029 consensus figure.
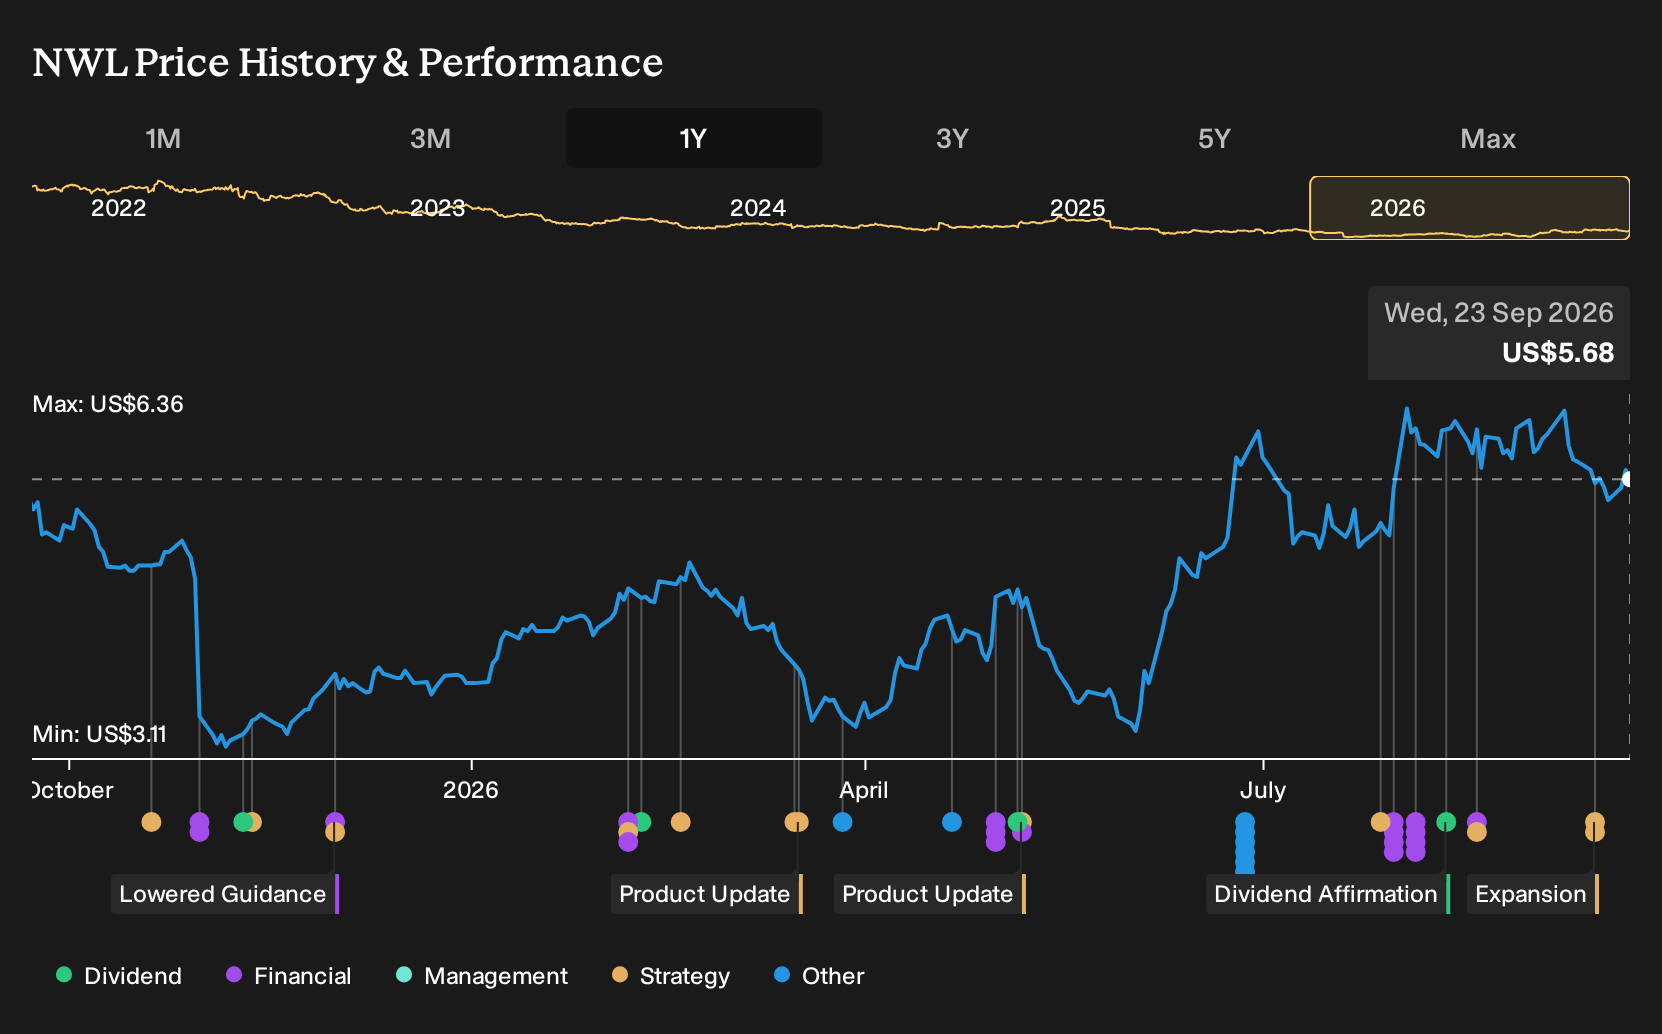
Uncover why Newell Brands' fair value indicates a 17% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
One alternate view on Newell Brands leans hard into product design as a moat. The most optimistic analysts were already penciling in US$7.9b of revenue and US$637.7 million of earnings by 2029, far above consensus. Those estimates came before this Atlanta Design Center news, so you may want to see how their narrative shifts now.
Explore 3 other Newell Brands fair value estimates, including one that suggests potential upside of up to 281% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your Newell Brands research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Newell Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Newell Brands' overall financial health at a glance.
Looking For More Investment Ideas Beyond Newell Brands?
Once you have a view on Newell Brands, it can help to widen the lens and compare it with other businesses that match different risk, income, and quality profiles using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting in your portfolio, check out a curated set of dependable payers through 7 dividend fortresses.
- For readers who care most about balance sheet strength and fundamentals, scan a list of solid balance sheet and fundamentals (23 results) that might hold up better when conditions get tougher.
- If you prefer to hunt earlier in the story, focus on quality smaller players that the market may not fully appreciate yet by reviewing 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com