
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ventia Services Group And 2 Australian Undervalued Stocks To Own
Global bond yields have climbed as investors react to higher interest rate expectations, which has put pressure on highly geared businesses and more speculative Australian stocks. That same market mood can leave solid cash generators trading at prices that do not fully reflect their balance sheet strength. This article walks through three high quality, undervalued Australian companies from our screener that fit that description.
These three stocks are a useful sample, but the full screen pulled out 3 more high quality, undervalued Australian companies with equally compelling stories that are not covered below. To go straight to the source and identify your own highest conviction ideas, head into the High Quality Undervalued Stocks screener
Ventia Services Group (ASX:VNT)
Ventia Services Group plugs directly into the High Quality Undervalued Stocks theme through its long-term work maintaining critical infrastructure and digital connectivity assets, which is where the recurring cash flows and potential breakout in investor attention start to intersect.
"A record $20.6 billion work in hand (up 19.4%) and a high contract renewal rate (95%) indicate a robust and growing multi-year pipeline, underpinned by new and renewed long-term government and infrastructure contracts."
For Ventia, it will really matter when one unseen pressure around how these commitments translate into future pricing and margins becomes clearer.
Ventia Services Group runs infrastructure and facilities services across roads, utilities, defence and telecoms. Its A$1.7b telecommunications arm ties it closely to the digital connectivity theme, alongside transport, infrastructure services and defence and social infrastructure that together generate several billion dollars in annual revenue. The stock carries a market value of about A$4.9b.
When that pressure on pricing and margins finally comes into focus, the full narrative for Ventia Services Group shows how Ventia Services Group could see sentiment accelerate beyond headline contracts.

Sigma Healthcare (ASX:SIG)
Sigma Healthcare underpins the High Quality Undervalued Stocks theme through its pharmacy wholesale and distribution engine, supplying Chemist Warehouse, Amcal and other banners. This business model feeds recurring cash flows and a balance sheet that can support growth in both Australia and overseas markets.
Sigma Healthcare runs a pharmacy wholesale, distribution and franchise network supplying healthcare and beauty products and MPS Connect services. It generates about A$10.8b from its Healthcare segment and carries a market value near A$29.4b.
"Although Sigma Healthcare is benefiting from strong GLP-1 demand and an aging population that lifts prescription volumes, the GLP-1 category is dilutive to gross margin percentage."
What really shapes the long term payoff is how one unresolved pressure on profitability interacts with those steady wholesale cash flows.
That profitability pressure is exactly where the story gets interesting, and the full narrative for Sigma Healthcare unpacks how Sigma Healthcare’s margin headwinds could evolve into an accelerating earnings engine.

Westgold Resources (ASX:WGX)
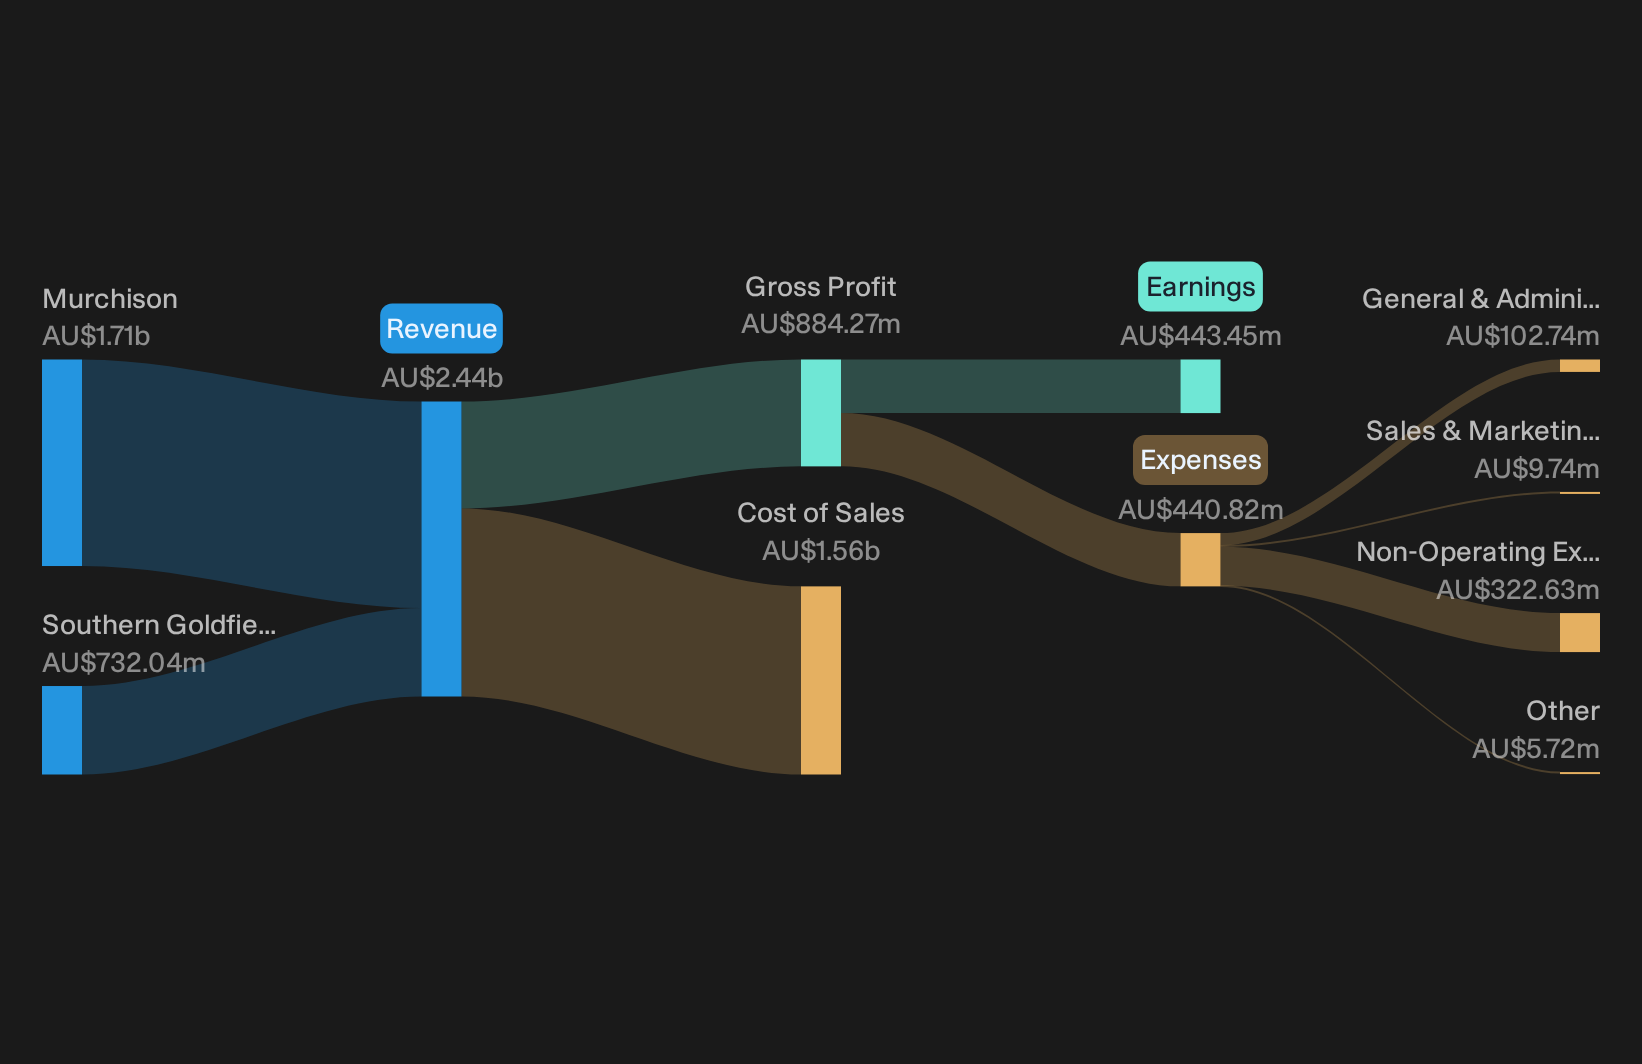
Westgold Resources is closely linked to the High Quality Undervalued Stocks theme through its producing Murchison and Southern Goldfields mines, which generate operating cash and support a robust balance sheet. The miner reported about A$1.7b from Murchison and A$732 million from Southern Goldfields, with a market cap near A$5.3b.
Westgold Resources is a relatively pure play on the screener’s idea that strong cash generation and a solid balance sheet can support a potential value opportunity, with its Western Australian gold hubs doing the heavy lifting while new projects move up the queue.
"The integration of the Karora transaction has significantly increased Westgold's production scale and operational flexibility, positioning the company to benefit fully from sustained global monetary instability and rising geopolitical tensions, with upside leverage to higher gold prices directly feeding into revenue and earnings."
The key factor from here is how one cost and grade equation develops inside those larger processing hubs over the coming years.
As that grade and cost equation plays out, the full narrative for Westgold Resources shows where Westgold Resources could see operating scale, capital plans and risk all start to decouple.
Seeking Fresh Alternatives Before They Fly
New ideas move first, prices move next. Fresh themes can gain breakout momentum while data is still under the radar for now. Consider acting early instead of reacting late.
- Explore income opportunities that may work harder for you by scanning the 3 dividend fortresses before yields change and the crowd takes notice.
- Look for potential infrastructure leaders by running the 39 power grid technology and infrastructure stocks while these grid upgrades may still be quietly reflected in prices.
- Monitor potential automation innovators with the 94 robotics and automation stocks before robotics spending changes and valuations adjust.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com