
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Onto Innovation (ONTO) Fairly Valued On Rising EPS Estimates?
Onto Innovation (ONTO) has attracted fresh attention after analysts raised earnings per share projections for its upcoming report, helping the stock climb 2.84% and end a month-long slide.
That bounce sits within a choppy year for Onto Innovation, where the share price has delivered a 70.20% year-to-date return but fallen 17.99% over the past 90 days, while the 1-year total shareholder return of 115.57% points to strong longer term momentum despite recent volatility.
Scan analyst-favored opportunities related to Onto Innovation momentum by reviewing the hand-picked 16 high quality undiscovered gems that may be flying under most investors' radar.
Bulls see Onto Innovation’s pullback as a chance to own a high-growth semiconductor supplier after a strong run. Bears see stretched expectations and recent weakness. Which case fits the current valuation setup?
Most Popular Narrative: 26% Undervalued
Onto Innovation’s most followed narrative pegs fair value around $380 per share, above the last close at $282.31. This frames the recent pullback as a valuation gap rather than just noise.
Onto Innovation is emerging as one of the most strategically important semiconductor equipment companies in the AI supply chain. While much investor attention remains focused on GPU manufacturers and memory suppliers, the next bottleneck increasingly lies in advanced packaging, the complex process of stacking, connecting, and inspecting AI chips and HBM memory at nanometer precision.
See why 37 investors see Onto Innovation as 26% undervalued.
According to FundamentalFlow, the narrative leans heavily on Onto Innovation’s role in advanced packaging, its TSMC qualification, and exposure to HBM inspection as core reasons the stock could warrant a higher valuation range than a more typical semiconductor equipment peer.
The same narrative anchors on a fair value of about $380 per share, which implies a meaningful gap to the current $282.31 price and a discount of roughly 25.7% to that internal estimate. This is in contrast with Simply Wall St’s own model-based fair value of $283.56 per share, which suggests the stock trades only 0.4% below that figure.
Forecasts in the dataset point to expected annual earnings expansion of 51.3% and revenue growth of 20.7% per year, both ahead of the broader US market assumptions in the model. Longer term return on equity is projected to reach 23.4%, compared with a current 6.9% level that is described as low.
Recent financial history adds some complexity. Profit margins of 11.8% are reported as lower than the prior year’s 19.2%, and last year’s earnings growth of 33.5% declined compared with the 5-year average pace. There is also a large one off loss of $90.1m flagged in the most recent 12 months of results.
On the sentiment side, analysts are described as being in good agreement, with a consensus price target of $386.36 that sits 36.9% above the market price. A separate SWS DCF output places future cash flow value at $283.56 per share, almost exactly in line with where Onto Innovation trades today.
Putting those pieces together, the most popular narrative presents Onto Innovation as a high-growth AI packaging enabler that could merit a higher long term valuation anchor. At the same time, the current fair value models and high P/E based checks highlight an expensive entry point and leave investors weighing strong growth forecasts against already full expectations.
Result: Fair Value of $380 (UNDERVALUED)
Still, Onto Innovation’s story can unwind quickly if advanced packaging demand slows, or if export controls tighten and crimp China related equipment sales.
Find out about the key risks to this Onto Innovation narrative.
Another View: Onto Innovation Through the P/E Lens
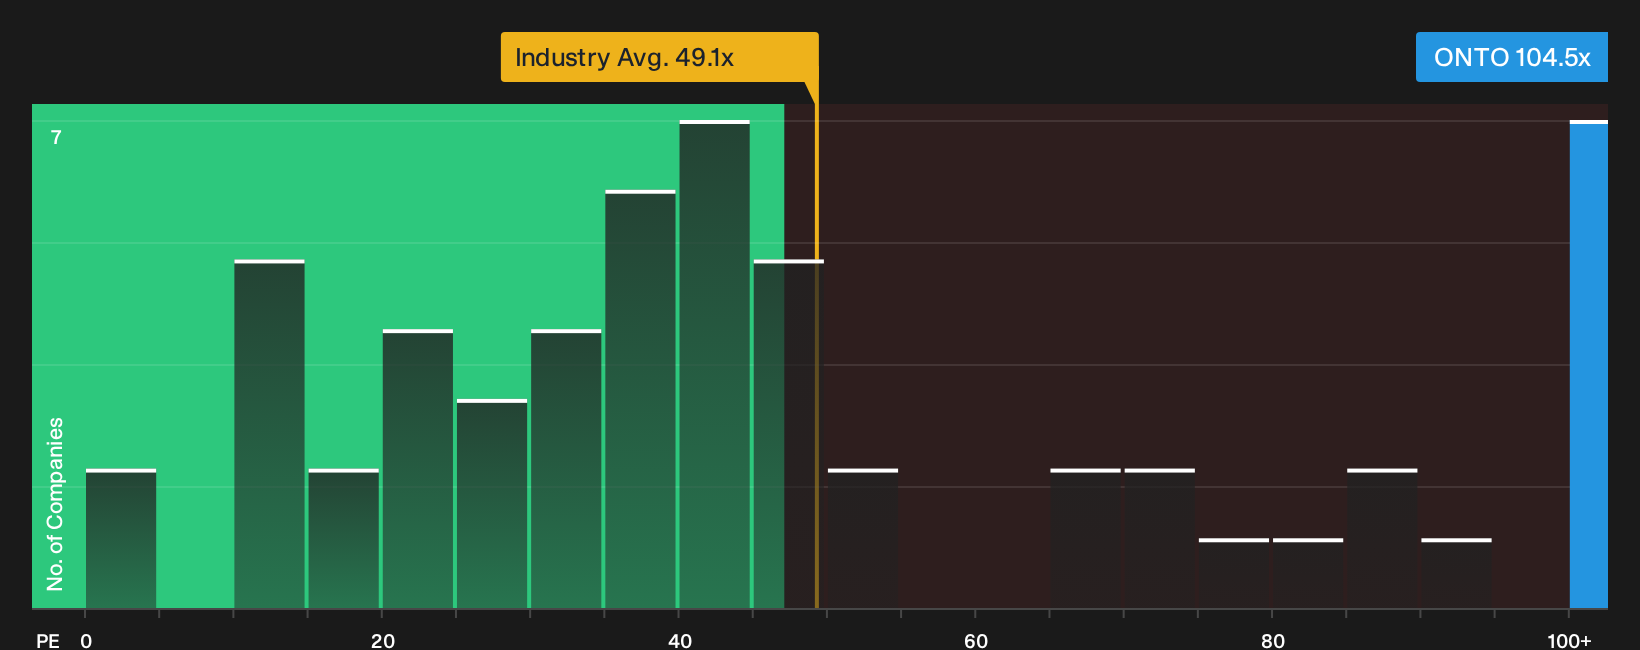
Onto Innovation looks very different when you swap narrative fair values for simple earnings multiples. The stock trades on a P/E of 104.5x, while the fair ratio sits at 46.7x and the US Semiconductor industry average sits near 49x. That is a wide gap. It signals that even small disappointments on the growth story could hit sentiment hard, because the market may have already priced in a lot of good news.
For investors weighing that kind of valuation risk against the AI packaging potential, it can be useful to stress test the numbers with a full breakdown of the earnings multiple, peer set and fair ratio assumptions. From there, you can ask whether this premium still feels comfortable at your own risk level.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Onto Innovation after all that, or feeling pressed to take a side quickly? Weigh the excitement against the concerns by starting with the 3 key rewards and 3 important warning signs.
Looking for more ideas beyond Onto Innovation?
Do not stop with Onto Innovation when there are other compelling setups on offer. Use the screeners below to quickly uncover fresh candidates worth a deeper look.
- Target resilient businesses that pair strong fundamentals with clean finances by scanning the list of solid balance sheet and fundamentals (23 results) for potential portfolio anchors.
- Hunt for mispriced opportunities where quality and valuation align by running the 30 high quality undervalued stocks before the crowd catches on.
- Prioritise sleep-at-night holdings by filtering for companies in the 31 resilient stocks with low risk scores that aim to keep volatility and risk in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com