
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
RB Global (RBA) Expands Its Buyback, Is The Stock Still Below Fair Value?
RB Global (RBA) drew fresh attention on September 15, 2026, after announcing a larger equity buyback. The amended normal course issuer bid now allows repurchases of up to 14,224,129 shares, or 7.6% of outstanding stock.
RB Global’s larger buyback comes at a time of recent share price weakness, with the stock down 28.29% over the past 90 days and 19.81% year to date, while the 5-year total shareholder return of 48.05% points to a stronger longer-run record.
Scan beyond RB Global and see how other companies responding to share price pressure and capital returns stack up in the 30 high quality undervalued stocks.
RB Global has authorized a larger buyback while the share price trades at a steep discount to both analyst targets and estimated fair value. Is this simply a market overreaction, or a warning investors should heed as they look at valuation next?
Most Popular Narrative: 35% Undervalued
RB Global last closed at $82.83, while the most followed valuation narrative pegs fair value at $127.73. The buyback lands against a backdrop where the shares are framed as materially underpriced relative to modeled cash flows and future earnings power.
Continued expansion of value-added services such as data analytics, transportation, and financial solutions is increasing service revenue, improving overall earnings quality, and contributing to margin expansion through higher-margin offerings.
Investments in digital innovation, such as optimizing multi-channel auction formats and advanced technology integrations, are expected to drive operational efficiency, higher transaction frequencies, and improved EBITDA margins.
See why 3 investors see RB Global as 35% undervalued.
Result: Fair Value of $127.73 (UNDERVALUED)
Still, the RB Global story can be knocked off course if weaker transaction volumes or tougher integration of recent deals weigh on revenue and earnings expectations.
Find out about the key risks to this RB Global narrative.
Another View on RB Global’s Valuation
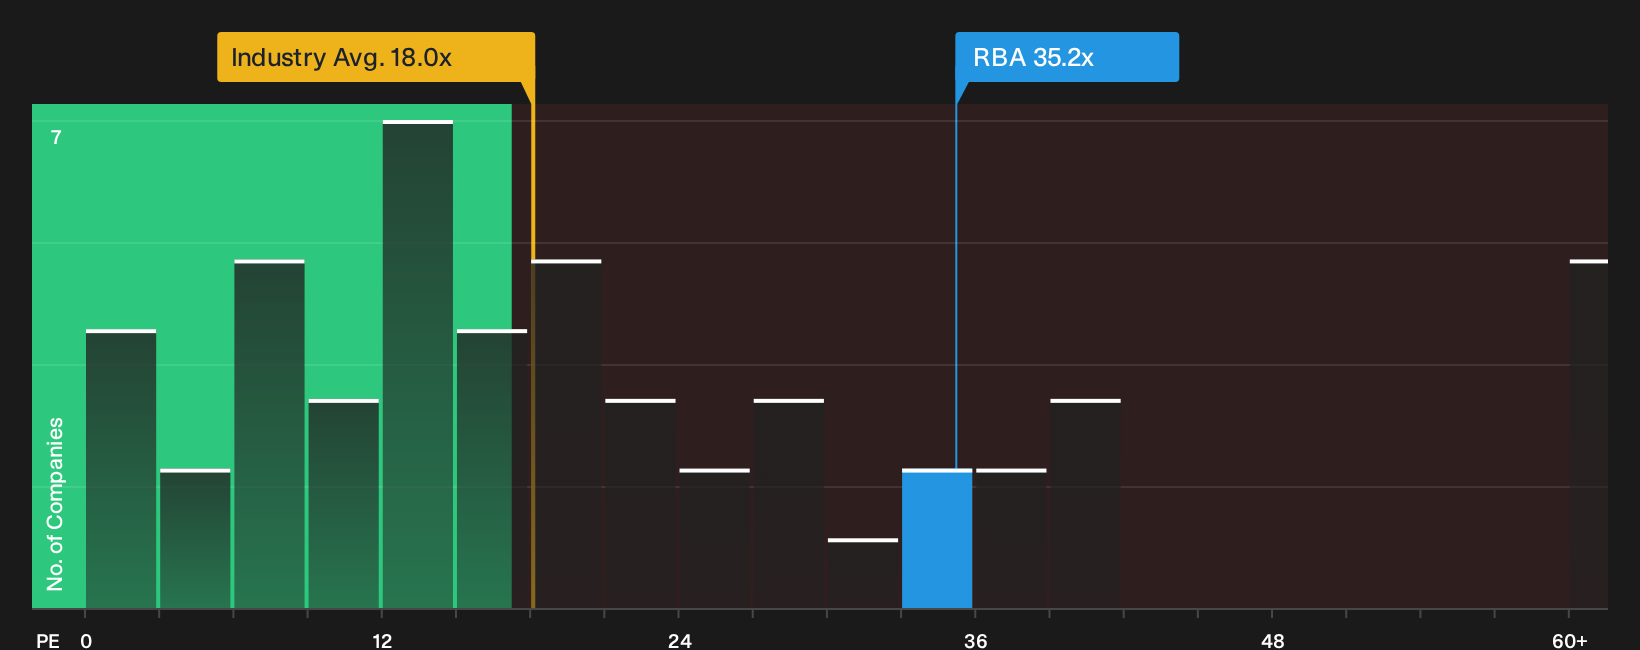
The story looks very different when you swap fair value models for simple pricing math. RB Global trades on a P/E of 35.2x, compared with 34x for close peers and 18x across the wider US Commercial Services group, while the fair ratio points to 28.6x instead.
That gap means the stock already carries a richer earnings tag than both sector and fair ratio benchmarks, even as the wider narrative frames it as undervalued. The question for investors is whether the growth and quality story justifies paying up on this measure, or if it narrows from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on RB Global’s value case and risk profile can pull you in opposite directions. Move quickly, review the data independently, and weigh the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond RB Global?
If RB Global has your attention, do not stop here. Broaden your watchlist and pressure test your thesis against other opportunities using focused stock screeners.
- Chase value opportunities that pair quality fundamentals with pricing pressure by scanning the 30 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by zeroing in on companies with robust finances in the list of solid balance sheet and fundamentals (23 results).
- Seek out potential future leaders before the crowd catches on by reviewing the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com