
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Has Teekay Tankers (TNK) Run Too Far After Hormuz Reopening Hopes?
Rumors that the Strait of Hormuz could reopen soon, after severe disruption linked to the Iran war, have shifted sentiment toward tanker operators and pushed Teekay Tankers (NYSE:TNK) lower following a sharp run.
For investors who have watched Teekay Tankers climb sharply this year, the latest pullback sits in a different context. The 1-day share price return is down 1.11% and the 7-day share price return is down 6.05%. The 90-day share price return is 34.52% and the year-to-date share price return is 83.57%, while the 5-year total shareholder return is about 7x. This points to notable long-term momentum even as near-term sentiment cools with the Hormuz headlines.
Scan beyond Teekay Tankers and see how other shipping and energy carriers are reacting to the same headlines with the hand picked list of solid balance sheet and fundamentals (23 results)
Teekay Tankers has run far ahead of many tanker peers, and the current price now sits slightly above the average analyst target while still well below some intrinsic value estimates. Where does fair value really land after this Hormuz driven swing?
Most Popular Narrative: 1% Overvalued
Teekay Tankers last closed at $94.54, just above the most followed fair value estimate of $93.80, which leans on a 7.24% discount rate and assumes softer earnings ahead.
Analysts expect earnings to reach $258.6 million (and earnings per share of $9.03) by about September 2029, down from $592.0 million today. The analysts are largely in agreement about this estimate.
See why 32 investors see Teekay Tankers as 1% overvalued.
Result: Fair Value of $93.80 (OVERVALUED)
Still, Teekay Tankers faces two clear pressure points: slowing projected oil demand growth and ongoing fleet renewal risks that could weigh on utilization and earnings.
Find out about the key risks to this Teekay Tankers narrative.
Another View: Teekay Tankers Through The Earnings Lens
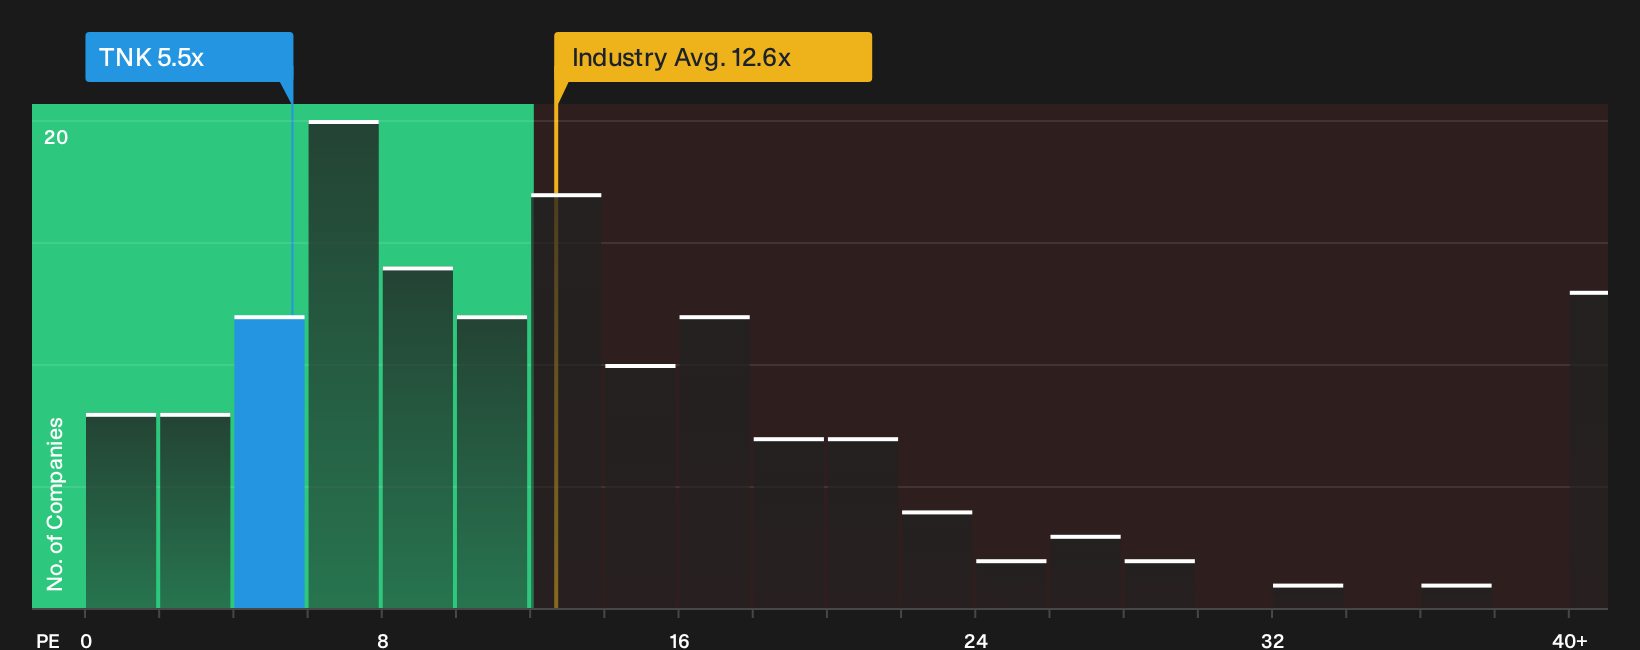
That 1% overvaluation call looks very different when you shift focus from discounted earnings forecasts to what Teekay Tankers actually trades on today. The stock changes hands at a P/E of 5.5x, compared with 12.7x for the wider US Oil and Gas group and 13.7x for close peers.
The fair ratio sits at 6.9x, above the current multiple but still below sector and peer averages. That gap suggests the market is pricing in meaningful earnings risk already, even as the SWS DCF model flags potential value upside. Which signal do you trust more when Hormuz headlines are this loud?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Teekay Tankers is mixed following the Hormuz headlines and the ongoing valuation debate. Consider reviewing the balance of risks and rewards while sentiment is still evolving through the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Teekay Tankers?
Do not stop with Teekay Tankers. Fresh ideas from diversified screeners can help you spot opportunities and avoid concentration risk as headlines keep shifting.
- Target resilient compounding potential by scanning a broad range of financially strong businesses with the 31 resilient stocks with low risk scores.
- Hunt for compelling value opportunities by checking companies that pair quality fundamentals with appealing prices through the 30 high quality undervalued stocks.
- Stack potential income streams by reviewing reliable payout candidates curated in the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com