
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Sectra (OM:SECT B) Hospital Imaging Rollouts
- Sectra reported that its digital pathology module is now live at four hospitals in France’s PACA region and that its cloud enterprise imaging contract in Denmark has been extended to cover the merged Region Østdanmark through 2037.
- These rollouts show Sectra scaling one shared imaging platform across multiple hospitals, which can concentrate implementation costs and deepen long-term, recurring service relationships with public health systems.
- We will examine how Sectra's investment narrative around recurring cloud imaging services is shaped by this wider regional deployment momentum.
Sectra Investment Narrative Recap
To own Sectra, you need to believe that hospitals keep consolidating imaging and diagnostics on shared, long-term IT platforms and that recurring cloud services offset lumpier license and hardware demand. The PACA pathology go live and the Danish cloud extension both support that recurring service angle. For the next year, execution on these large deployments looks more important than new order headlines.
The biggest swing factor remains how cleanly Sectra manages its shift toward as-a-service delivery without pressuring margins or creating choppy revenue, especially given exposure to large single contracts. Implementation-heavy rollouts in France and Denmark could raise near term costs and delay revenue recognition if projects slip. If they stay on schedule, the news is supportive but not transformational.
The cloud extension in Region Østdanmark is the clearest operational mirror to the PACA pathology rollout. One shows Sectra scaling a managed imaging service across a merged Danish region through 2037. The other shows a shared pathology setup spreading across eight PACA hospitals with completion planned during 2027. Together they describe the same execution test.
For catalysts, both contracts push Sectra further into multi-year, multi-site rollouts, which directly ties into the recurring revenue story that many investors focus on. The risk sits on the other side of that coin. These are resource-intensive deployments that can weigh on margins and add timing noise to reported figures if hospital networks or infrastructure are not ready on schedule.
Sectra's current earnings of SEK 563.8 million sit against analyst expectations for SEK 1.2 billion of earnings and SEK 5.6 billion of revenue by 2029, which implies forecast annual revenue growth of 15.6% and an earnings increase of about SEK 636 million from today's level.
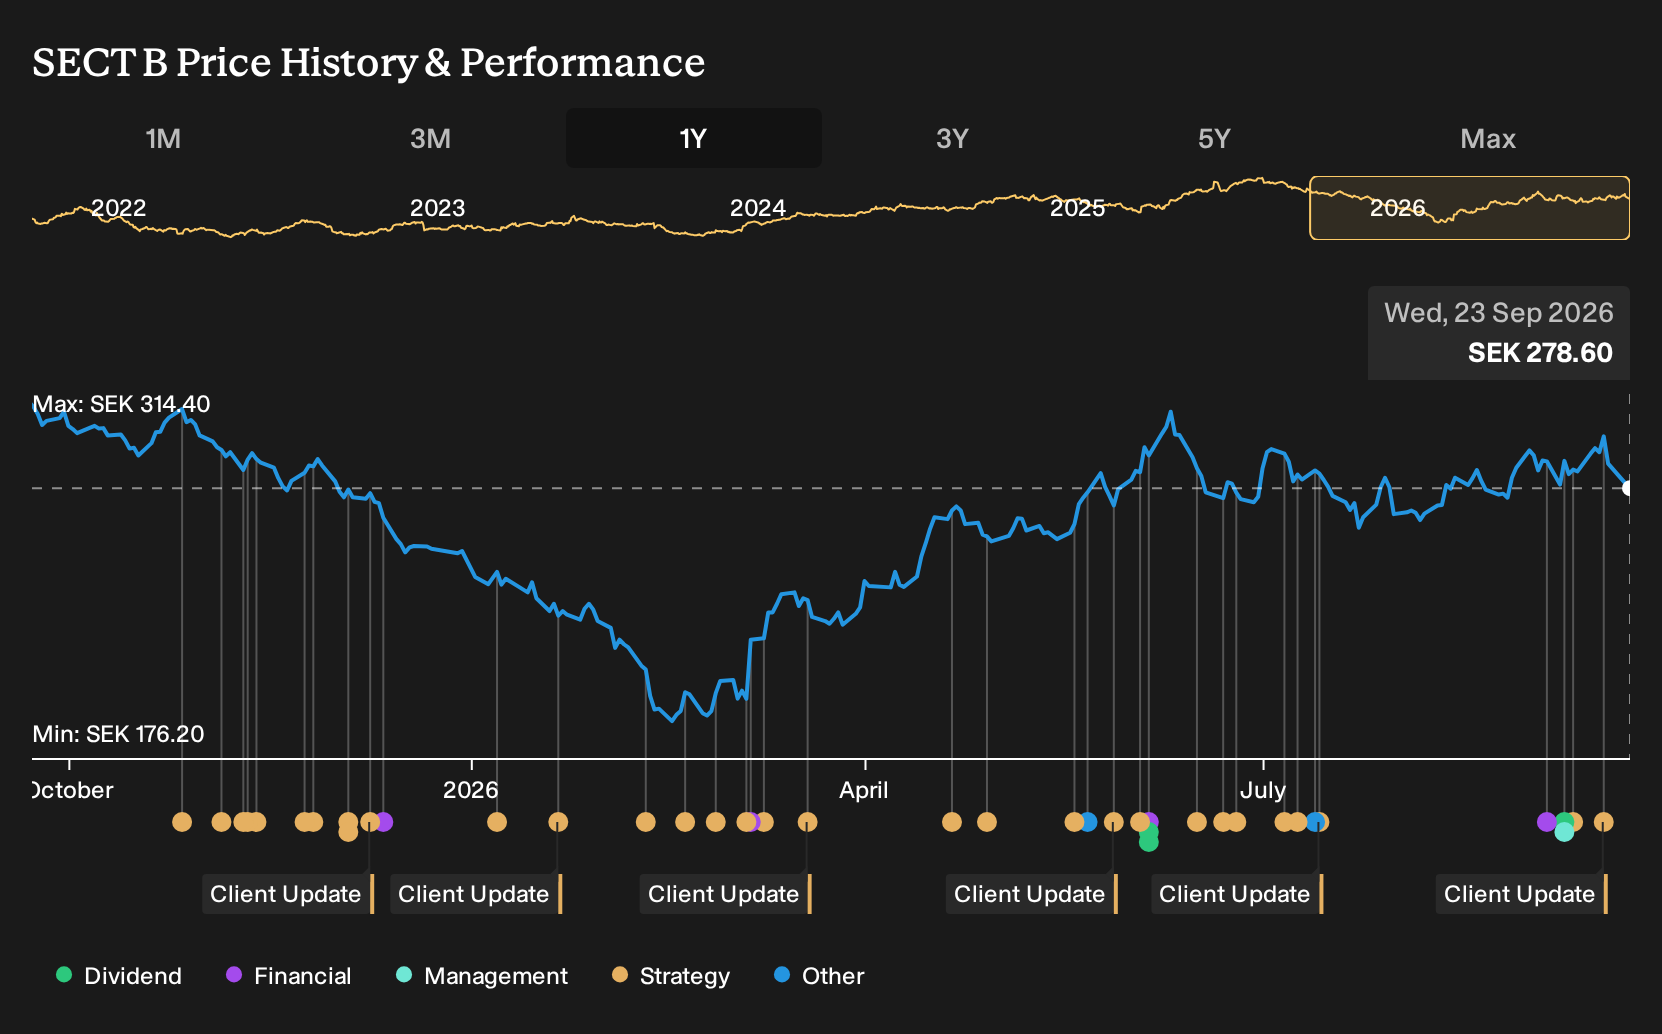
Uncover why Sectra's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view puts hyperscale cloud costs at the center of the Sectra story. If Azure pricing and imaging data size keep outpacing pricing power, bearish analysts argue that gross margins could compress even if revenue reaches about SEK 5.8b and earnings about SEK 1.3b by 2029. That group set a SEK 220 target before this PACA and Region Østdanmark news. This means their story is much more cautious than the SEK 340 consensus. Use that spread to stress test your own view and see how fresh regional wins might shift expectations in either direction.
Explore 3 other Sectra fair value estimates, including one that suggests as much as 34% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Sectra research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sectra. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sectra's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sectra?
If the Sectra story has sharpened your thinking on healthcare technology, it can help to pressure test that framework against a wider watchlist built from different business models and balance sheet profiles.
The Simply Wall St screener makes that easier by letting you filter for traits that actually match your approach, rather than just focusing on what is in the headlines.
- If you care most about paying less for quality, start with a curated set of value candidates through the 171 high quality undervalued stocks.
- For readers who prioritize resilience and capital protection, focus your research on companies flagged in the 229 resilient stocks with low risk scores.
- If you want to combine solid finances with room for the story to develop, scan the 618 high quality undiscovered gems and build a bench of future watchlist ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com