
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ACM Research (ACMR) Jumps On China Debate As Undervalued View Holds
ACM Research (ACMR) is back in focus after a sharp price move related to renewed debate over its significant exposure to China’s semiconductor sector, potential export control risk, and ongoing R&D spending.
The current US$80.67 share price comes after a 6.42% 1 day share price return and a 24.45% 7 day share price return. However, the 90 day move is down 24.51%, so ACM Research now sits with strong year to date share price momentum of 79.75% alongside a very large 3 year total shareholder return of 357.83%, which dwarfs its 133.17% 5 year total shareholder return.
Scan beyond ACM Research and compare its surge and China exposure with a hand picked set of 85 AI infrastructure stocks that are shaping the semiconductor equipment build out behind AI demand.
After a surge like this, the debate around ACM Research shifts to something simple. Is the recent jump just the market finally catching up, or has most of the upside already played out in the price?
Most Popular Narrative: 29.9% Undervalued
The most followed narrative currently pegs ACM Research at a fair value of $115.14 versus the $80.67 last close, which frames the recent rally as only part of the move that narrative backers expect.
Advanced digitalization and AI adoption are driving a surge in demand for next-generation semiconductor manufacturing, with ACM's differentiated cleaning and plating solutions (such as its proprietary N2 bubbling and SPM tools) positioned to capture increased orders as foundries invest in more complex 3D NAND, DRAM, and logic nodes, supporting long-term revenue growth.
See why 90 investors see ACM Research as 30% undervalued.
Result: Fair Value of $115.14 (UNDERVALUED)
Still, the bullish ACM Research story hinges on China holding up and on high R&D spending translating into commercially successful tools rather than just higher costs.
Find out about the key risks to this ACM Research narrative.
Another View On ACM Research’s Valuation
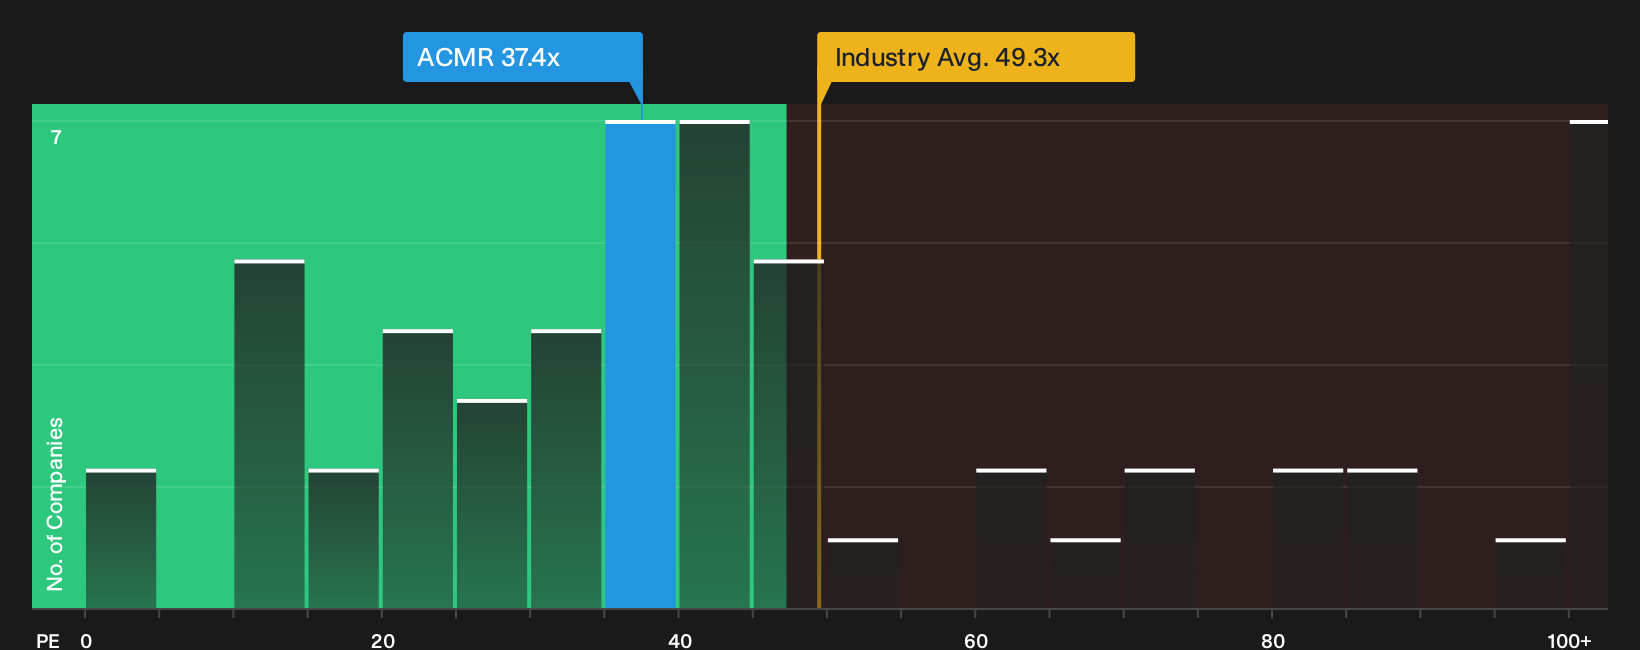
On simple P/E maths, ACM Research does not look obviously cheap. The stock trades on 37.4x earnings, which is lower than the US Semiconductor sector at 49.1x and well below peer averages of 88.8x, yet it sits above a fair ratio of 34.4x that our work suggests the market could gravitate toward over time.
That mix points to some valuation cushion versus the wider industry but also a risk that the multiple compresses toward the fair ratio if expectations ease. The real question for you is whether current growth and China exposure justify paying above that 34.4x line.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ACM Research for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on ACM Research so far. If you want to move quickly from headline moves to your own view of the balance between risk and upside, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more ACM Research investment ideas?
If you like how ACM Research puts complex themes into focus, do not leave potential opportunities on the table when a few targeted screens can surface fresh ideas fast.
- Hunt for mispriced quality and see which companies line up as 30 high quality undervalued stocks before momentum and sentiment crowd the trade.
- Target resilience first and build a watchlist from a list of solid balance sheet and fundamentals (23 results) so weaker balance sheets do not quietly raise your risk.
- Go off the beaten path and track a 16 high quality undiscovered gems before wider attention closes the window on early entry.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com