
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Cronos Group Stock Leads 3 Canadian Penny Stocks To Watch
Canadian penny stocks with healthier balance sheets are getting fresh attention as US interest rates rise and borrowing becomes more expensive worldwide. Higher yields reward patience, but they also punish weaker businesses that rely heavily on cheap debt. That puts financially sound, low-priced shares in a very small club. This article highlights three such Canadian penny stocks, screened for stronger fundamentals, that some investors are watching more closely today.
The three stocks below are just a small sample, and the full screen surfaced 346 more financially fit penny stock opportunities with equally compelling narratives that are not covered here.
If you want to identify, analyze, and focus on the ideas that best match your risk tolerance and goals, head straight to the Financially Fit Penny Stocks screener
Cronos Group (TSX:CRON)
Cronos Group is a cannabis consumer products business that fits the Financially Fit Penny Stocks theme through its focus on branded dried flower, oils, vapes, edibles, and tinctures. It generates about $179 million from cultivation, manufacturing, and marketing activities and carries a market value near $1.8b.
Cronos Group appeals to theme-focused penny stock investors because it couples a branded cannabis product engine with a balance sheet that allows it to stay on the front foot rather than simply trying to survive.
"Cronos' substantial cash reserves and zero debt enable aggressive deployment into R&D, strategic investments (such as the recent High Tide convertible loan and warrant package), and innovation in biosynthetic and next-generation cannabinoids. This creates new intellectual property-driven revenue streams with structurally higher gross margins and diversifies long-term earnings potential."
The real tension for Cronos Group now is how that financial firepower translates into future pricing power and margin resilience if one key assumption shifts.
If that assumption is starting to shift in your mind, read the full narrative for Cronos Group to see how Cronos Group’s cash engine could accelerate or stall from here.

Omai Gold Mines (TSXV:OMG)
Omai Gold Mines is a Toronto based explorer focused on its 100% owned Omai gold prospecting license in Guyana, a single gold and precious metals project that fits the Financially Fit Penny Stocks theme as a low priced, asset backed junior valued around $1.9b.
Investors looking at Omai Gold Mines are really looking at one thing: a penny tier explorer with full ownership of a large Guyanese gold project that already has a PEA, resource growth drilling and ETF inclusion on the board, alongside forecast losses, no near term revenue and one unresolved funding question that could redefine how much of any future mine shareholders actually keep.
That funding swing question is where your thesis really moves, so run Omai Gold Mines through the analysis report for Omai Gold Mines to see what the market might be missing.

McChip Resources (TSXV:MCS)
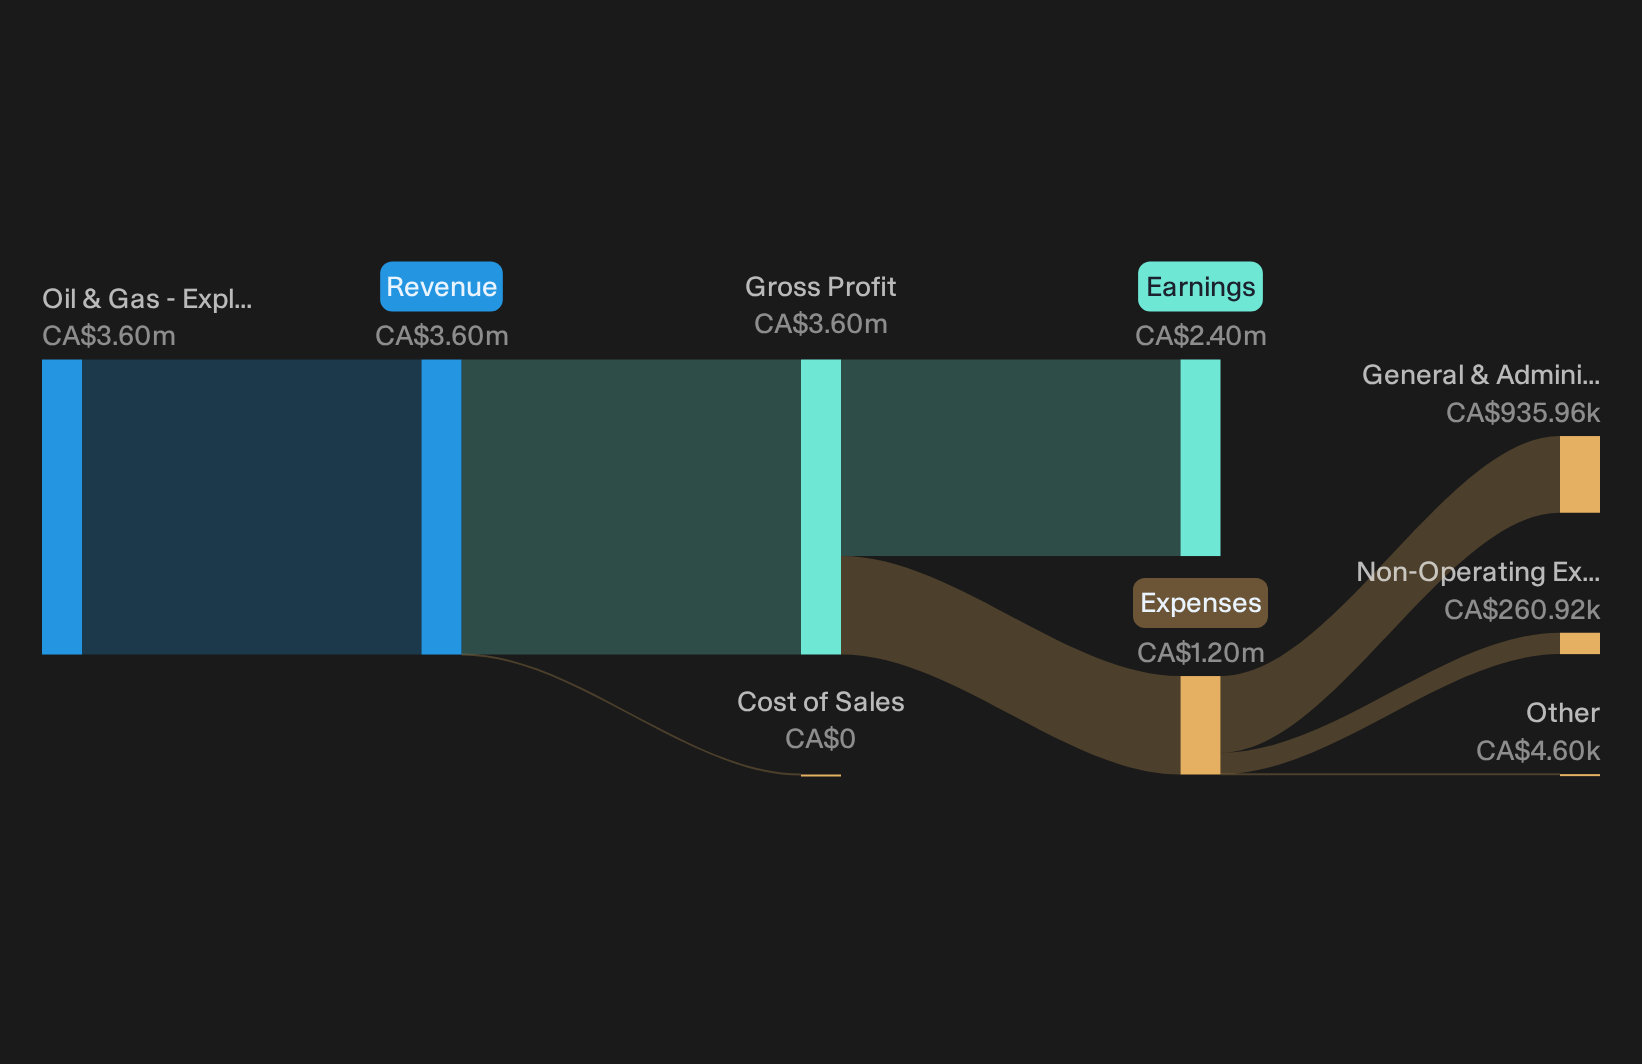
McChip Resources is a Toronto based natural resources investor with interests in oil and gas, minerals, and a Saskatchewan potash project that ties it to fertilizer markets. The business generated about CA$4 million from oil and gas exploration and production in Canada and carries a market cap near CA$4 million.
McChip Resources sits in the Financially Fit Penny Stocks bucket as a tiny, resource focused vehicle whose Saskatchewan potash exposure provides a concrete asset link to commodity demand. Recent losses and tight free cash flow keep risk high, so the appeal largely depends on how one currently unseen pressure around capital and payouts is resolved.
That hidden capital pressure makes it worth running McChip Resources through the 2 key rewards and 3 important warning signs to see what might be quietly compounding in your favour.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Stocks can break out, momentum can build, and prices can be flying before the crowd even looks. Use curated screens while it matters and get in early.
- Spot established cash generators before sentiment flips and run them through the 5 high quality undervalued stocks to filter for quality balance sheets and earnings strength that are under the radar for now.
- Ride structural power demand trends by scanning the 39 power grid technology and infrastructure stocks focused on grid technology and infrastructure players that could catch the next leg of capital flows.
- Surf real business traction in AI instead of hype by zeroing in on the 38 profitable AI stocks that aren't just burning cash and focusing on companies already funding growth with their own cash.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com