
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Technip Energies (ENXTPA:TE) Following The SABIC Deal And The Undervalued Narrative
Technip Energies stock reaction to new SABIC licensing role
Technip Energies (ENXTPA:TE) just took on a wider role in petrochemicals after agreeing to become the worldwide licensor of SABIC’s Low-Density Polyethylene Clean Tubular Reactor technology.
The move builds on a collaboration dating back to 1996 and gives the French engineering group a central position in rolling out this established CTR process across global polyolefins projects.
Technip Energies shares trade at €29.82 after a 1-day share price return of 1.77%. However, momentum has cooled over recent months, with the 90-day share price return down 12.35% and the 1-year total shareholder return falling 24.10%. This contrasts with a much stronger 5-year total shareholder return of 157.13%, which points to a still resilient long-run story behind the current pullback.
Scan beyond Technip Energies and review hand-picked peers in large, capital-intensive projects with the 39 power grid technology and infrastructure stocks for potential opportunities related to the energy and infrastructure buildout cycle.
The SABIC licensing deal leans toward business traction, while the share price tells a softer sentiment story. Which side carries more weight in Technip Energies’ current valuation setup?
Most Popular Narrative: 26% Undervalued
On the most followed narrative, Technip Energies screens as undervalued, with a fair value of €40.47 versus the last close at €29.82. This puts the SABIC licensing deal against a backdrop of already discounted expectations.
Significant recent growth in decarbonization-related orders (now nearly 40% of total intake and over €5 billion in the last 18 months), combined with global net-zero commitments and increasing government incentives for clean energy infrastructure (like CCUS and blue hydrogen), indicates substantial forward demand that should support backlog expansion and sustained top-line revenue growth.
See why 24 investors see Technip Energies as 26% undervalued.
Result: Fair Value of €40.47 (UNDERVALUED)
Still, heavy reliance on LNG and hydrocarbons, together with project timing and policy risks around key decarbonization contracts, could quickly challenge the Technip Energies undervaluation story.
Find out about the key risks to this Technip Energies narrative.
Another View on Technip Energies valuation
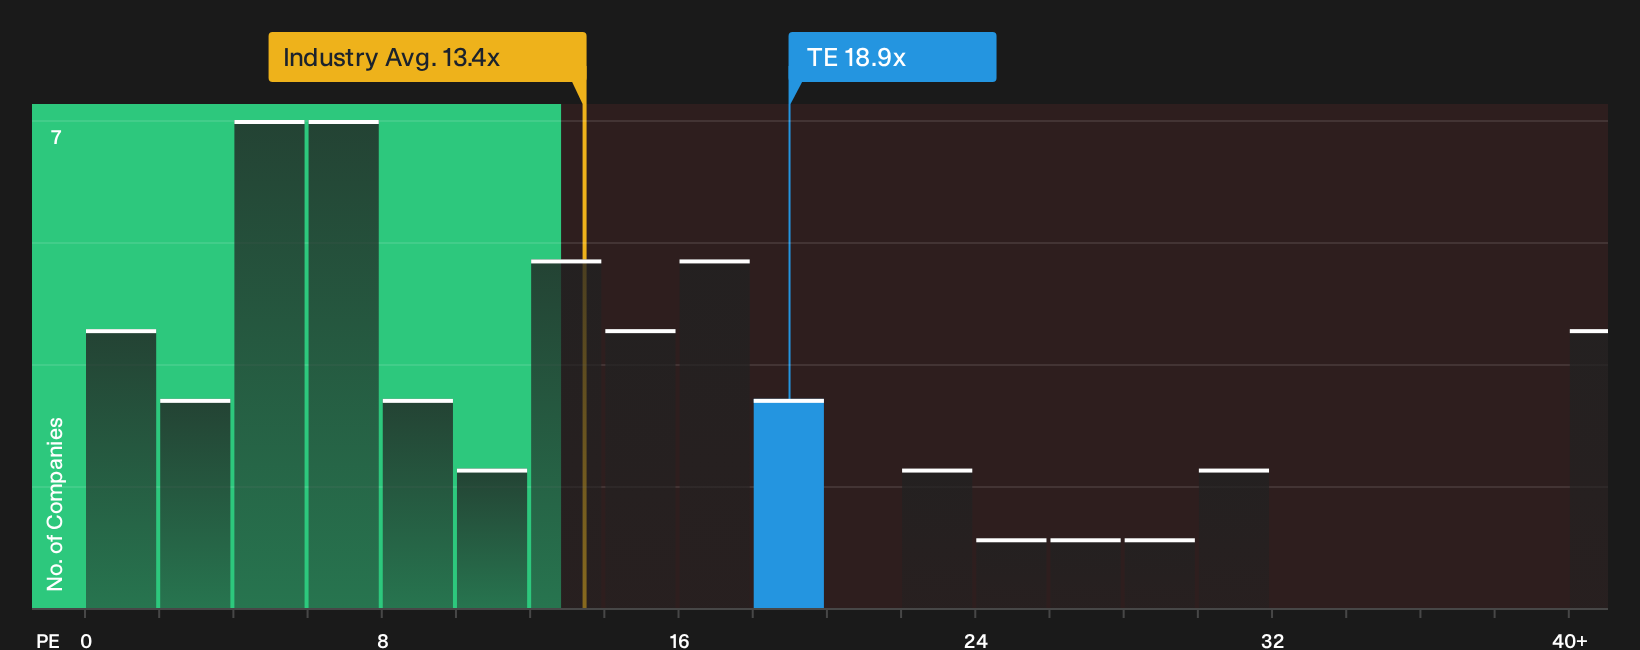
The first narrative leans on fair value estimates and analyst targets that suggest Technip Energies is undervalued. The picture changes once the focus shifts to the P/E ratio, which sits at 18.9x.
That multiple is only fractionally above the fair ratio of 18.8x. However, it is much higher than both the European Energy Services industry on 13.7x and a peer average of 12.3x. This points to a stock that already carries a meaningful premium, so the question becomes whether investors are being paid enough for that valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Technip Energies story so far. If you want to move fast and ground your own view in data, start with the 3 key rewards and 1 important warning sign.
Looking for more Technip Energies style investment ideas?
If Technip Energies has sharpened your focus on valuation and risk, use the Simply Wall Street Screener to quickly spot other opportunities before they move without you.
- Hunt for potential mispriced quality by reviewing the broader market through the 171 high quality undervalued stocks that filters for companies with both strength and room for rerating.
- Zero in on resilience and capital preservation by scanning the 229 resilient stocks with low risk scores that highlights businesses with steadier profiles when conditions get choppy.
- Target financial sturdiness by checking the list of solid balance sheet and fundamentals (198 results) that surfaces companies with stronger fundamentals and healthier balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com