
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
We Think Solstice Minerals (ASX:SLS) Can Easily Afford To Drive Business Growth
Just because a business does not make any money, does not mean that the stock will go down. For example, Solstice Minerals (ASX:SLS) shareholders have done very well over the last year, with the share price soaring by 614%. But while history lauds those rare successes, those that fail are often forgotten; who remembers Pets.com?
So notwithstanding the buoyant share price, we think it's well worth asking whether Solstice Minerals' cash burn is too risky. For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). Let's start with an examination of the business' cash, relative to its cash burn.
Does Solstice Minerals Have A Long Cash Runway?
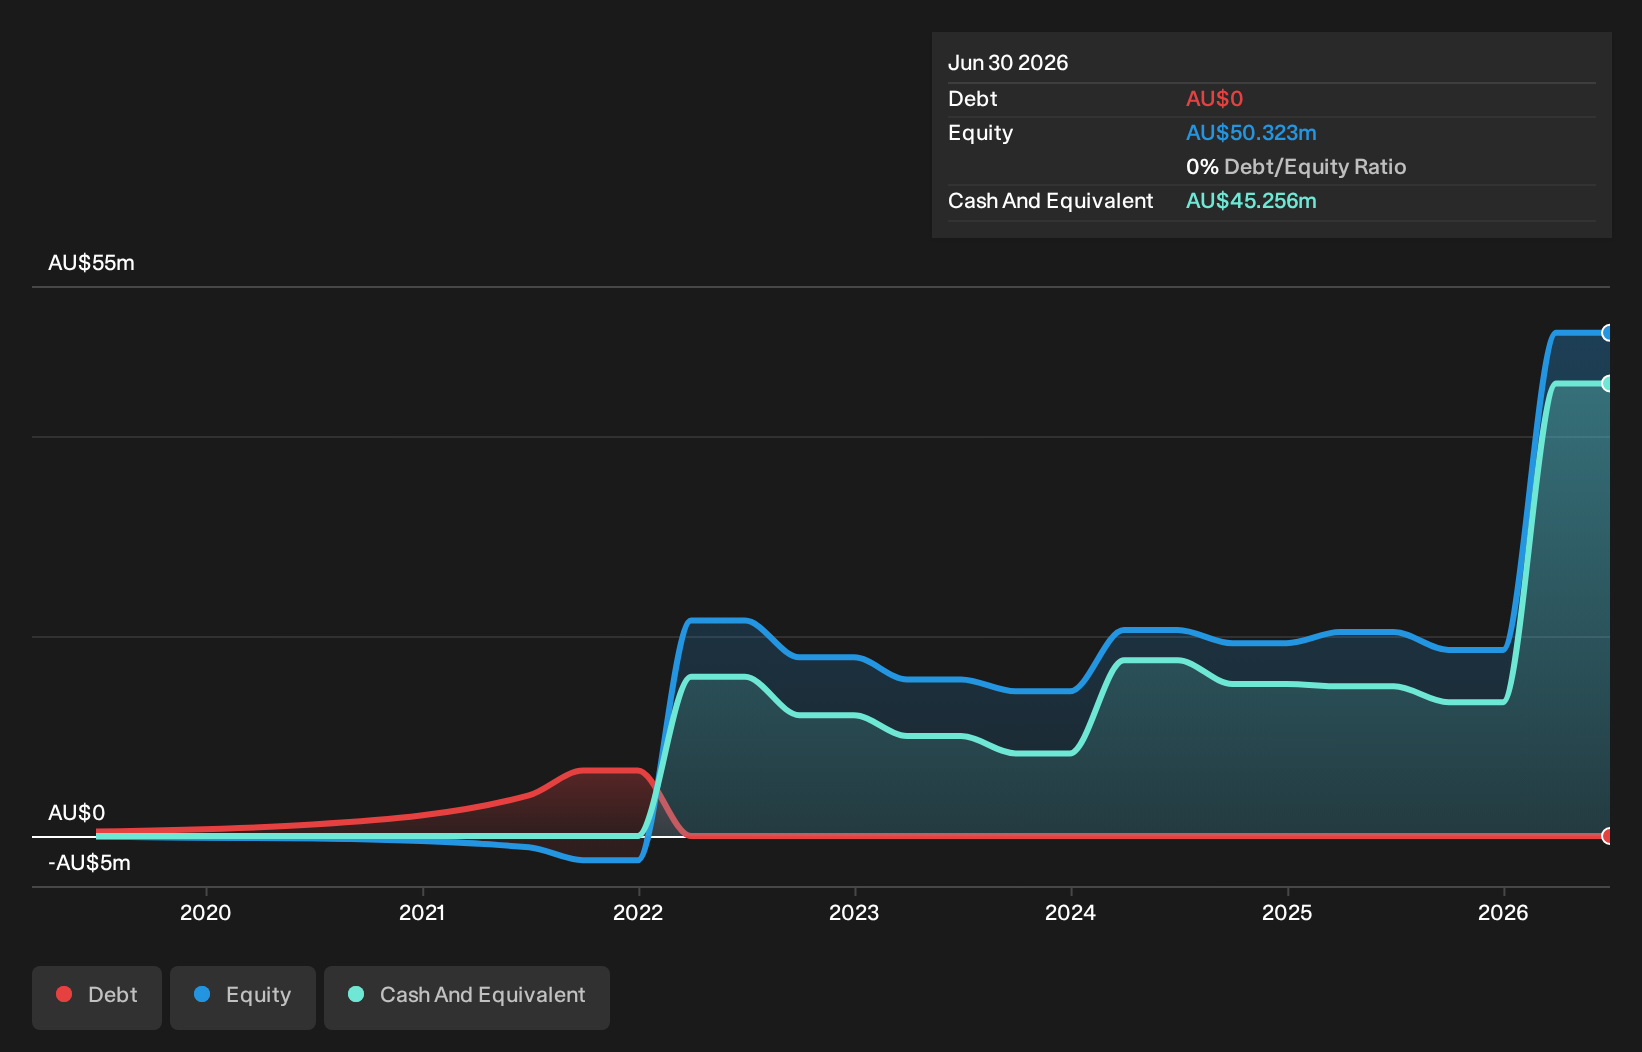
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. When Solstice Minerals last reported its June 2026 balance sheet in September 2026, it had zero debt and cash worth AU$45m. Looking at the last year, the company burnt through AU$6.7m. Therefore, from June 2026 it had 6.7 years of cash runway. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. Depicted below, you can see how its cash holdings have changed over time.
See our latest analysis for Solstice Minerals
How Is Solstice Minerals' Cash Burn Changing Over Time?
Solstice Minerals didn't record any revenue over the last year, indicating that it's an early stage company still developing its business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. With the cash burn rate up 45% in the last year, it seems that the company is ratcheting up investment in the business over time. That's not necessarily a bad thing, but investors should be mindful of the fact that will shorten the cash runway. While the past is always worth studying, it is the future that matters most of all. So you might want to take a peek at how much the company is expected to grow in the next few years.
How Easily Can Solstice Minerals Raise Cash?
While Solstice Minerals does have a solid cash runway, its cash burn trajectory may have some shareholders thinking ahead to when the company may need to raise more cash. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
Solstice Minerals' cash burn of AU$6.7m is about 1.5% of its AU$456m market capitalisation. So it could almost certainly just borrow a little to fund another year's growth, or else easily raise the cash by issuing a few shares.
Is Solstice Minerals' Cash Burn A Worry?
It may already be apparent to you that we're relatively comfortable with the way Solstice Minerals is burning through its cash. In particular, we think its cash runway stands out as evidence that the company is well on top of its spending. While its increasing cash burn wasn't great, the other factors mentioned in this article more than make up for weakness on that measure. Looking at all the measures in this article, together, we're not worried about its rate of cash burn; the company seems well on top of its medium-term spending needs. On another note, we conducted an in-depth investigation of the company, and identified 3 warning signs for Solstice Minerals (2 can't be ignored!) that you should be aware of before investing here.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.