
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Reset Might Change The Case For Investing In New Hope Stock (ASX:NHC)
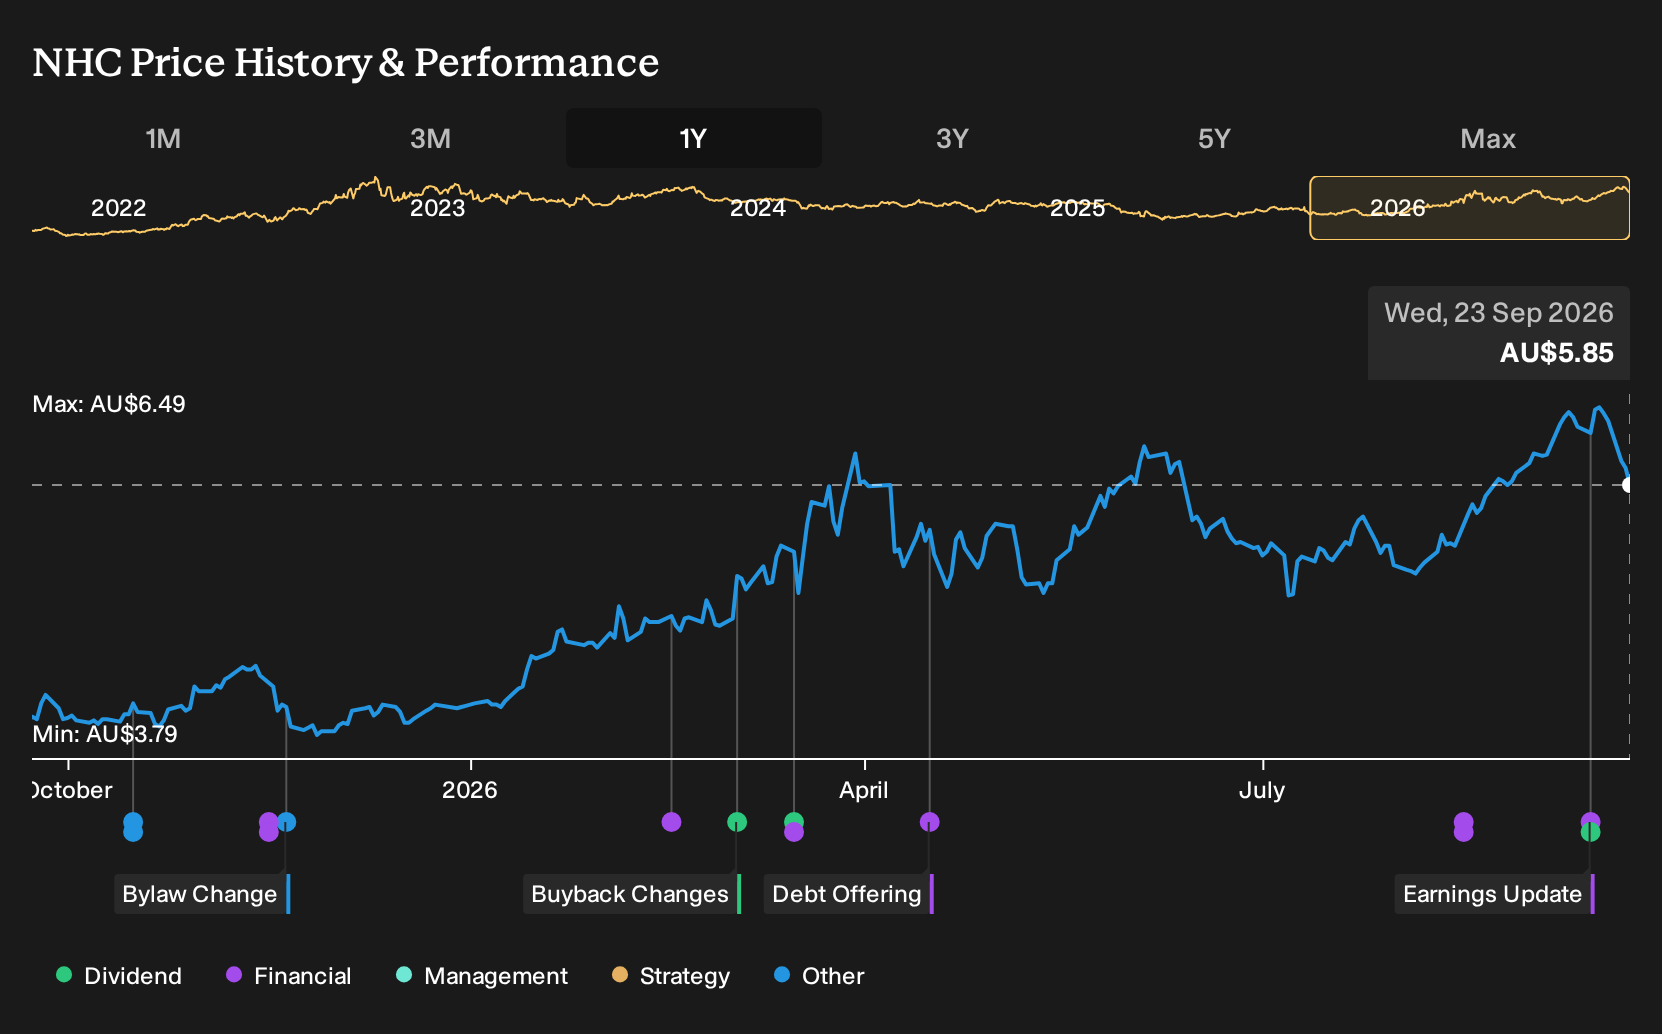
- New Hope Corporation Limited released full year results to July 31, 2026, with revenue of A$1,803.97 million and net income of A$160.96 million, and declared a cash dividend of A$0.30 per share that went ex dividend on September 21, 2026.
- The sharp step down in net profit and earnings per share compared with the prior year shows that earnings power has shifted, even as New Hope continues to return cash to investors through dividends.
- We will assess how New Hope's reduced full year earnings, together with the A$0.30 dividend, shape the longer term investment narrative for the company.
Compare New Hope's reset earnings power with other income focused opportunities by scanning our hand picked 3 dividend fortresses for ideas with similar cash return profiles.
New Hope Investment Narrative Recap
To hold New Hope, you need to be comfortable owning a coal producer that is trying to balance heavy industry headwinds with disciplined operations and cash returns. The latest full year result shows much thinner earnings power, with net income of A$160.96 million and basic EPS from continuing operations of A$0.191, so near term investor focus naturally shifts to cost control and volume reliability.
The biggest short term swing factor is whether New Hope can keep production, pricing and logistics steady enough to protect margins in a sector facing decarbonisation pressure. The key risk right now is that lower profitability combines with regulatory and ESG constraints, which could limit flexibility on future projects and stress the economics of existing assets.
The most relevant update for that thesis is the A$0.30 per share cash dividend for the year to July 31, 2026, which went ex dividend on 21 September 2026. That payout is sizeable against A$0.191 in basic EPS from continuing operations, so it leans heavily on past cash generation and the balance sheet rather than current earnings alone.
For you, the question is whether New Hope can keep funding this kind of distribution while facing thinner margins and long term coal demand pressure. The announced dividend highlights the reward side of the story, but the flagged concern that the yield is not well covered by earnings or free cash flow underlines how closely income investors may want to watch future results and capital allocation.
New Hope Earnings Outlook Versus Today
New Hope's narrative projects A$2.0b revenue and A$375.0 million earnings by 2029. That profile lines up with 8.7% yearly revenue growth and an earnings increase of about A$221.6 million from A$153.4 million today.
Uncover why New Hope's fair value indicates a 7% potential downside to its current price, suggesting a premium that may not hold.
Exploring Other Perspectives
One alternate view on New Hope leans heavily on the coal price catalyst. The most optimistic analysts were pencilling in A$2.1b of revenue and A$452.4 million of earnings by 2029, well above consensus, before this dividend and earnings update. You can treat this news as a fresh test of those upbeat assumptions.
Explore 3 other New Hope fair value estimates, including one that suggests potential upside of as much as 119% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your New Hope research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for New Hope. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate New Hope's overall financial health at a glance.
Looking For More Ideas Beyond New Hope?
If New Hope has sharpened your focus on income, risk and balance sheet strength, it can be useful to line it up against other listed businesses using the Simply Wall St Screener.
- For investors prioritising resilient income and capital preservation, compare New Hope's profile with a curated 7 resilient stocks with low risk scores that may better match your comfort with downside risk.
- If you are hunting for strong cash returns with room for capital appreciation, broaden your watchlist with our carefully filtered 6 high quality undervalued stocks that share similar quality traits.
- Income focused readers who want to keep New Hope on the radar but widen the search can scan a hand picked 3 dividend fortresses that targets dependable distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com