
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Clariane (ENXTPA:CLARI) Just Gave Investors Something To Think About
Clariane (ENXTPA:CLARI) has signed a new €700 million unsecured revolving credit facility with a five year maturity. This replaces its previous syndicated line and adds an accordion option up to €900 million.
Set against this new €700 million facility, Clariane’s recent share price performance has been mixed, with the stock edging up 1.5% year to date but declining over the past quarter. The 1 year total shareholder return is down 8% and the 5 year total shareholder return has fallen sharply, despite a positive 3 year total shareholder return. This suggests short term caution from investors, even as longer term holders have seen pockets of recovery.
Capitalize on the balance sheet story around Clariane by scanning a curated list of solid balance sheet and fundamentals (198 results) that may better match the kind of financing resilience highlighted by this new credit facility.Clariane now has fresh liquidity in place and a business that generates €5,353.822 million of revenue, yet the share price has fallen sharply over five years. Is that operational scale already fairly reflected in today’s €3.99 stock price?
Most Popular Narrative: 14% Undervalued
On the Simply Wall St narrative, Clariane carries a fair value of €4.66 against a last close of €3.99, which casts the fresh €700 million credit line in a different light for anyone weighing the risk and reward trade off.
The refinancing and restructuring of debt to extend maturities and normalize access to debt markets may increase interest expenses or limit financial flexibility, potentially affecting future earnings. Clariane plans to reduce Wholeco leverage below 5x by 2026. Continued emphasis on deleveraging could limit opportunistic investments or growth initiatives, potentially slowing revenue growth.
See why 8 investors see Clariane as 14% undervalued.
Result: Fair Value of €4.66 (UNDERVALUED)
Still, if Clariane’s disposal program trims future revenue streams or if French pricing pressure persists on margins, the optimistic narrative around higher future P/E assumptions could quickly be challenged.
Find out about the key risks to this Clariane narrative.
Another View on Clariane’s Valuation
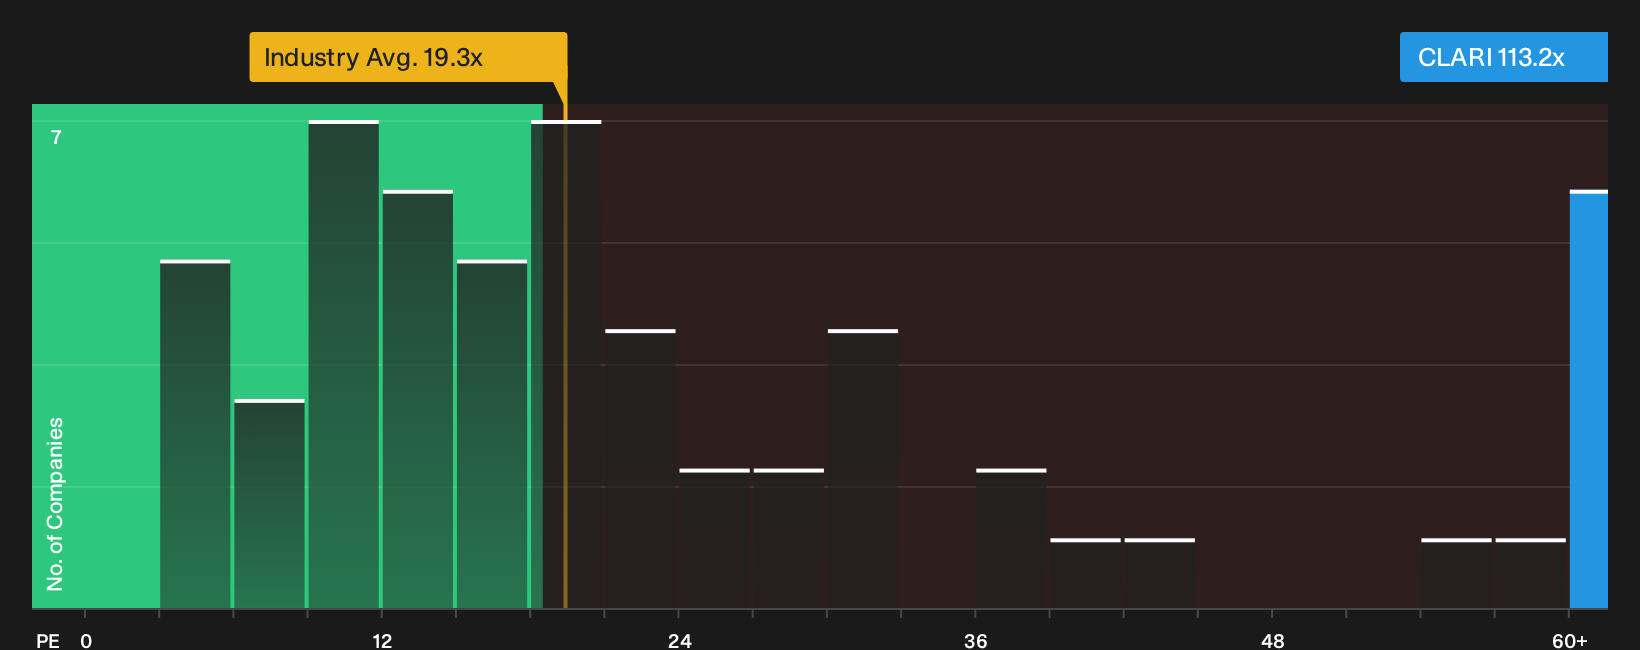
The first story around Clariane focuses on a fair value of €4.66, yet the current P/E of 113.2x paints a very different picture. The wider European Healthcare sector trades at 19.3x and peers average 14.3x, while the fair ratio sits at 27.4x. That gap points to rich expectations. If earnings or sentiment slip, how much room is there before the valuation resets?
See what the numbers say about this price in our valuation breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mixed signals around Clariane’s valuation and balance sheet? Take a closer look at the data now, pressure test the bullish and cautious cases, and check the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Clariane?
If Clariane has sharpened your focus on valuation, balance sheet strength, and income potential, broaden your watchlist now with curated ideas selected from the Simply Wall St screener.
- Target resilient wealth creation by reviewing companies that screen as 172 high quality undervalued stocks before valuations shift and opportunities narrow.
- Strengthen your income stream by checking out businesses tagged as 161 dividend fortresses that may support more dependable cash returns.
- Prioritise financial resilience by scanning the 229 resilient stocks with low risk scores that may offer steadier performance when conditions become more challenging.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com