
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Alibaba (BABA) New AI Chip Launch
- Alibaba Group Holding recently unveiled its Zhenwu V900 AI accelerator chip, which it says offers roughly 3x the performance of its predecessor, alongside plans to scale Qwen models to up to 10 trillion parameters and build more than 20 gigawatts of global data center capacity by 2032.
- The push into proprietary AI chips and massive cloud infrastructure suggests Alibaba is trying to keep more of the AI economics in house, reducing dependence on external suppliers and tying hardware, models, and cloud services into a single commercial engine.
- This analysis examines how Alibaba's investment narrative is being reshaped by the Zhenwu V900 AI chip and the 20 gigawatt data center plan.
See how Alibaba’s AI buildout compares with other potential breakouts in infrastructure-heavy tech by reviewing the hand picked 85 AI infrastructure stocks across global markets.
Alibaba Group Holding Investment Narrative Recap
To own Alibaba Group Holding today, you need to believe the heavy spending on AI chips, cloud infrastructure and quick commerce can eventually outweigh the hit to margins and free cash flow. The near term story is about execution on a huge capex plan while core commerce keeps throwing off enough cash to fund it.
The most important short term catalyst remains traction in Alibaba Cloud and AI services, which management is backing with RMB 380b of AI and cloud investment and a 20 gigawatt data center goal. The biggest current risk is that these AI and quick commerce bets stretch profitability longer than expected while regulatory scrutiny and legal actions stay in the background.
The Zhenwu V900 launch and the plan to exceed 20 gigawatts of global data center capacity by 2032 sit at the center of that thesis. Alibaba is committing more than US$53b over three years to support this build, with Citi now assuming higher capital spending from fiscal 2027 to 2029 as AI workloads scale.
For you as a shareholder, the operational question is simple: Can Alibaba turn proprietary chips, massive cloud regions across Europe, the Middle East and Asia, and Qwen models into durable AI and cloud revenue fast enough to offset weaker margins, slower China consumption and ongoing regulatory and class action risk.
What Alibaba’s AI Spending Implies For The Numbers
Alibaba Group Holding's current AI push sits against analyst models that already bake in faster activity. Consensus assumes revenue rises by 12.5% per year over the next three years as cloud, AI services and quick commerce scale on top of the existing retail engine.
On profitability, the group is modeled to move from a 7.0% margin today to 11.9% in three years, which would signal a very different earnings mix if it plays out. That path leans heavily on higher value cloud and AI workloads eventually outweighing the drag from heavy capex and early stage quick commerce spending.
On the bottom line, analysts expect earnings to reach CN¥176.3b by 2029, up from CN¥73.3b today. That implies an earnings increase of roughly CN¥103b from current levels, even before considering the wide range between the most optimistic and most cautious forecasts.
Alibaba Group Holding's narrative projects CN¥1,487.6b revenue and CN¥176.3b earnings by 2029. This requires 12.5% yearly revenue growth and an earnings increase of roughly CN¥103b from earnings today of CN¥73.3b.
Uncover how Alibaba Group Holding's fair value indicates a 68% potential upside to its current price, which could narrow quickly if sentiment turns.
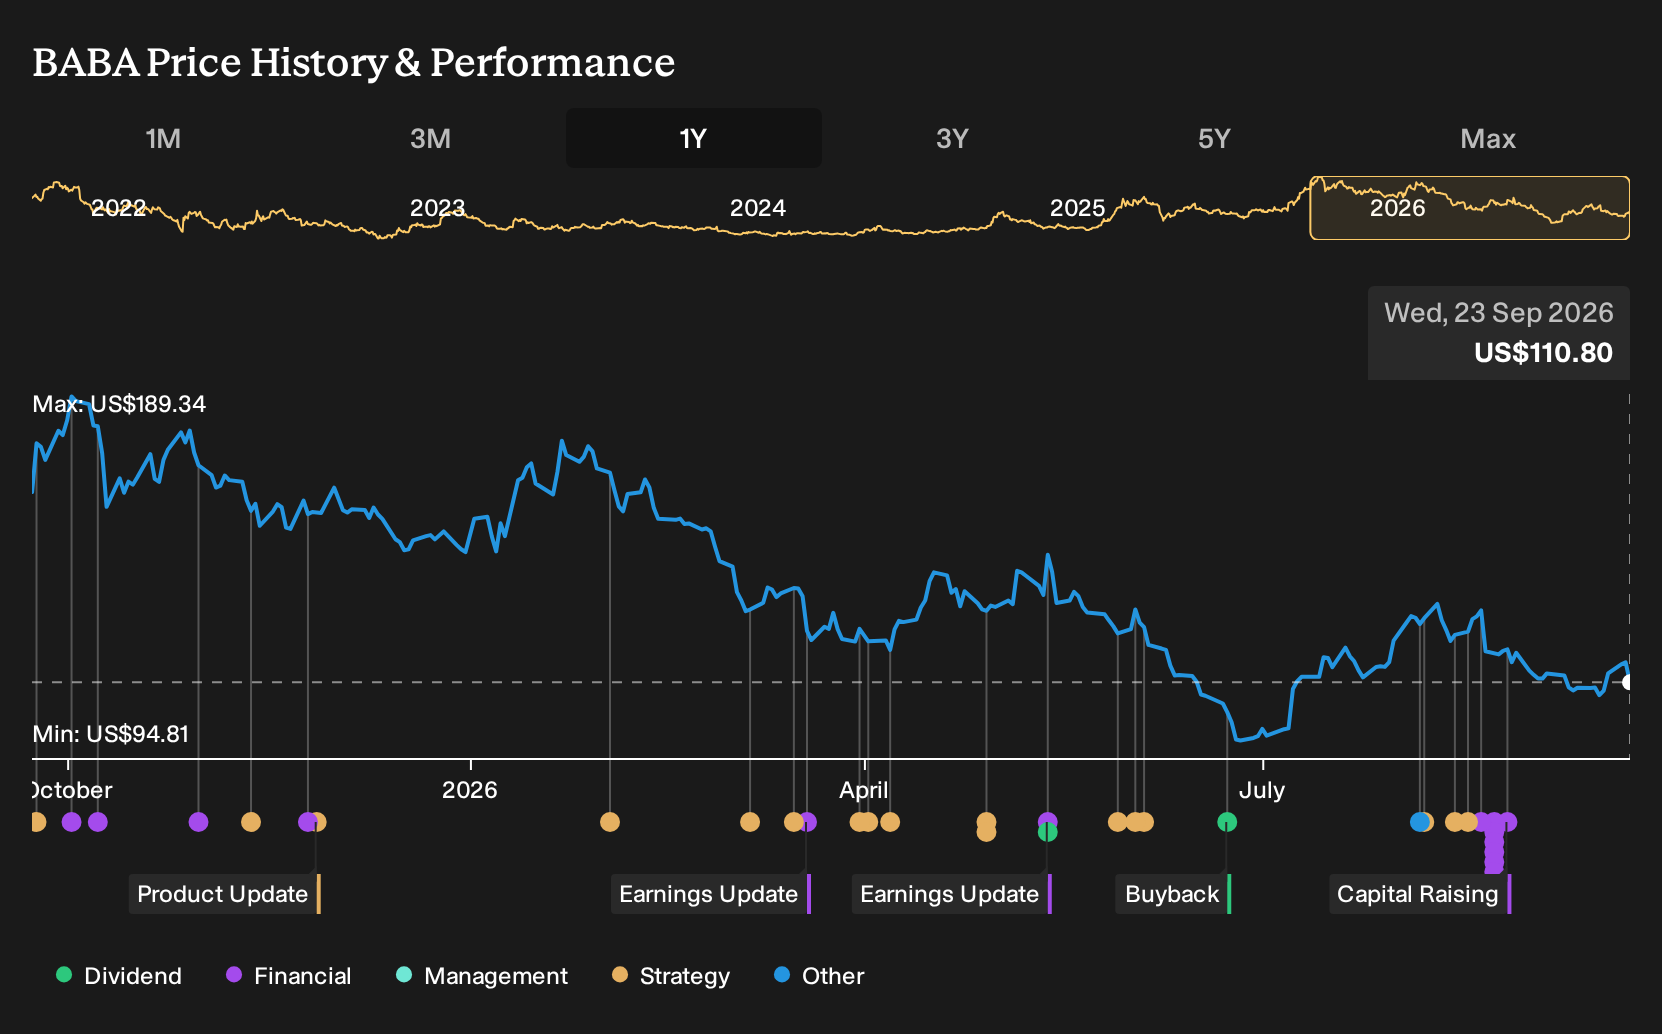
Exploring Other Perspectives
One alternate angle you might weigh focuses less on Alibaba’s AI upside and more on execution risk. The most optimistic analysts, working before this chip and 20 gigawatt plan, were already baking in CN¥1,687.4b of revenue and CN¥362.0b of earnings by 2029. If this new spending plan reshapes those forecasts, both enthusiasm and caution could widen.
Explore 22 other Alibaba Group Holding fair value estimates, including one that suggests up to 129% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own research and judgment.
- A great starting point for your Alibaba Group Holding research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alibaba Group Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alibaba Group Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alibaba Group Holding
If the Alibaba Group Holding story has sharpened your thinking about AI, cash generation and balance sheet strength, it can help to widen the lens and compare it with other opportunities using the Simply Wall St Screener.
- For investors who want income that can potentially keep pace with inflation, review 7 dividend fortresses that combine higher yields with fundamentals you can scrutinize in detail.
- If capital preservation and steadier return profiles matter most to you, scan through 31 resilient stocks with low risk scores that score well on resilience and financial risk metrics.
- To hunt for under the radar opportunities with solid business quality, check out 16 high quality undiscovered gems that pair fewer analyst eyes with strong underlying financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com