
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Are Higher Earnings Estimates Altering The Investment Case For Affiliated Managers Group Stock?
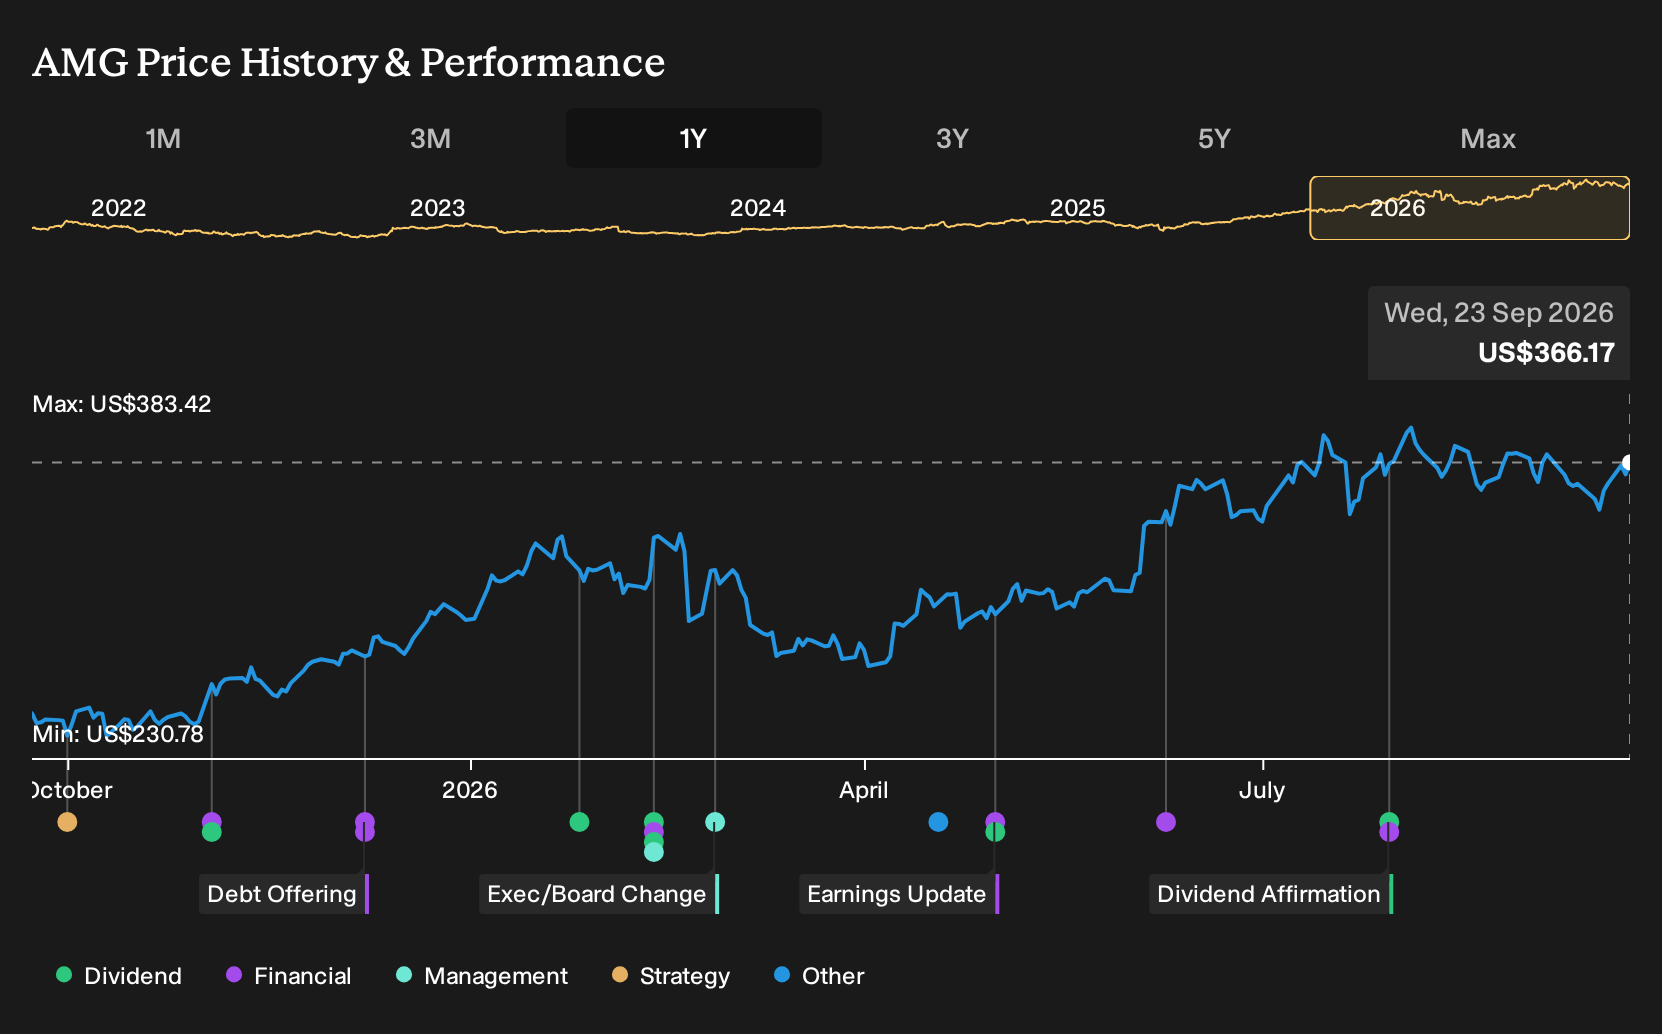
- Affiliated Managers Group recently saw full year earnings estimates move 5.2% higher over three months, while the business carried a Zacks Rank of #2 and outpaced both its Finance sector and Financial Investment Management industry return benchmarks year to date.
- This mix of upgraded earnings expectations and clear outperformance versus sector and industry peers points to improving fundamentals at key affiliates rather than sentiment driven momentum alone.
- We will look at how Affiliated Managers Group's investment narrative is affected by higher earnings estimates and its sector beating performance.
Affiliated Managers Group Investment Narrative Recap
To own Affiliated Managers Group, you need to be comfortable with a story that leans heavily on alternative assets and specialist affiliates. The recent earnings estimate move and year-to-date outperformance suggest those affiliates are executing well today. That supports the near-term catalyst, which is continued fee generation from alternatives and differentiated strategies if clients keep allocating to these products.
The biggest operational risk right now is still concentration. Earnings are tied to a handful of large boutiques and to fundraising cycles in private markets that can swing sharply from year to year. The latest news does not remove that risk. It just shows the model is working in the current backdrop.
With no fresh corporate announcements tied directly to this move in expectations, the most relevant context is the existing trend in Affiliated Managers Group's alternative platform. Affiliates exposed to private markets and liquid alternatives remain central to how AMG earns its fees, given higher pricing in those areas compared with more traditional strategies.
That focus links directly to the key catalysts and risks you are weighing. Strong organic inflows into alternatives and tax-aware strategies can support earnings, yet any slowdown in private markets fundraising or fee pressure would matter quickly. The recent estimate revision and relative share price strength highlight how sensitive AMG remains to that operating mix.
Affiliated Managers Group Forecasts and Analyst Assumptions
Affiliated Managers Group's narrative projects US$2.8b revenue and US$749.4 million earnings by 2029. This rests on revenue expanding at 7.3% per year and an earnings decline of US$106.9 million from US$856.3 million today.
For you as an investor, that mix of higher sales and lower profitability means analysts see growth in fee volume but also pressure on economics per dollar of revenue. The forecast drop in profit margin from 37.7% to 26.7% suggests more of each dollar is expected to be absorbed by affiliate payouts, compensation or other costs.
Affiliated Managers Group is also modeled to reduce its share count by 7% a year over the next three years. That shrinking equity base can support earnings per share even if total profit trends down, which helps explain why some analysts still see upside even with lower absolute earnings.
The projected P/E shift from 11.5x today to 15.7x on those 2029 earnings indicates the current research view relies on a higher multiple in the future. For you that translates to a simple test: you would need to be comfortable with a scenario where earnings are smaller than today, yet the market is willing to pay more for each dollar of those earnings.
Consensus price targets around US$433.29, with a range between US$330 and US$512, point to a wide spread in how analysts interpret these same cash flow paths and risk factors. Rather than treating that range as a forecast, use it as a reminder that assumptions around alternative asset flows, fee levels and capital returns to shareholders drive very different outcomes for Affiliated Managers Group.
Uncover why Affiliated Managers Group's fair value indicates an 18% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on Affiliated Managers Group puts much more weight on the risk that alternatives fall out of favour and clients shift harder toward low cost passive funds. Those more cautious analysts were working off revenue of about US$2.6b and earnings around US$856.0 million by 2029. That is close to flat profit versus today and helped underpin a US$360 price view before this latest earnings upgrade. Use that gap against the consensus US$2.8b revenue path as a prompt to explore how differently future fee pools and affiliate demand can be framed, and how this fresh news could eventually sway those opposing stories.
Explore another Affiliated Managers Group fair value estimate, including one that suggests it could be worth just $355.32.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A useful starting point for your Affiliated Managers Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could factor into your investment decision.
- See our latest analysis for Affiliated Managers Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Affiliated Managers Group's overall financial position at a glance.
Looking for more Affiliated Managers Group style ideas?
If the Affiliated Managers Group story has sharpened your thinking about earnings momentum, fee models and risk, it can be useful to cast a wider net. The Simply Wall St Screener lets you quickly filter the market for other stocks that fit the kind of profile you prefer, whether that is quality, income, resilience or potential mispricing.
- For investors hunting for quality at a sensible entry point, consider scanning a curated list of solid balance sheet and fundamentals (23 results) that can help you focus on companies with stronger financial footing.
- If predictable income matters most, filter for businesses with robust payouts using a targeted 7 dividend fortresses and see which ones currently offer the yields you want to research further.
- When the priority is skewing your watchlist toward resilience, you can narrow the field to companies with steadier profiles by starting with a 31 resilient stocks with low risk scores aligned to your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com