
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Waters (WAT), Why Is Fresh Attention Building Around It?
Everlywell partnership puts Waters in focus
Waters (WAT) moved into the spotlight after Everlywell selected its technology for an at home HPV cervical cancer screening partnership, tying the laboratory tools specialist directly to expanding preventive care access in the U.S.
Recent action around Waters reflects that this Everlywell deal lands on top of a busy stretch, with a new BD FACSDiscover A7 Cell Analyzer launch and an investor conference appearance in September. The 90-day share price return of 11.59% and 1-year total shareholder return of 43.71% point to building momentum that markets appear to link to both product announcements and shifting expectations around the diagnostics and biosciences portfolio.
Capitalize on the attention around Waters and this Everlywell deal by reviewing a hand-picked list of solid balance sheet and fundamentals (23 results) that could benefit from similar diagnostics and life sciences demand.After a 1-year total return of 43.71% and a share price near US$420, investors in Waters now face a cleaner question: Is most of the upside already priced in, or does the recent momentum still leave room ahead on valuation?
Most Popular Narrative: 4% Undervalued
On the most followed view of Waters, a fair value of about $439.70 sits modestly above the recent $420.57 share price. As a result, the Everlywell news is landing on a stock that this framework still sees as slightly below its modeled future cash and earnings profile using an 8.24% discount rate.
Recurring revenues are accelerating (up 11% this quarter), underpinned by expanding service plan attachments and e-commerce adoption, which enhances revenue stability and net margins, setting up the combined company for more resilient earnings across CapEx cycles.
See why 14 investors see Waters as 4% undervalued.
Result: Fair Value of $439.70 (UNDERVALUED)
Still, Waters faces real pressure if the BD deal underdelivers on the planned synergy targets, or if weaker academic and pharma funding drags on instrument demand.
Find out about the key risks to this Waters narrative.
Another View on Waters: rich sales multiple, different message
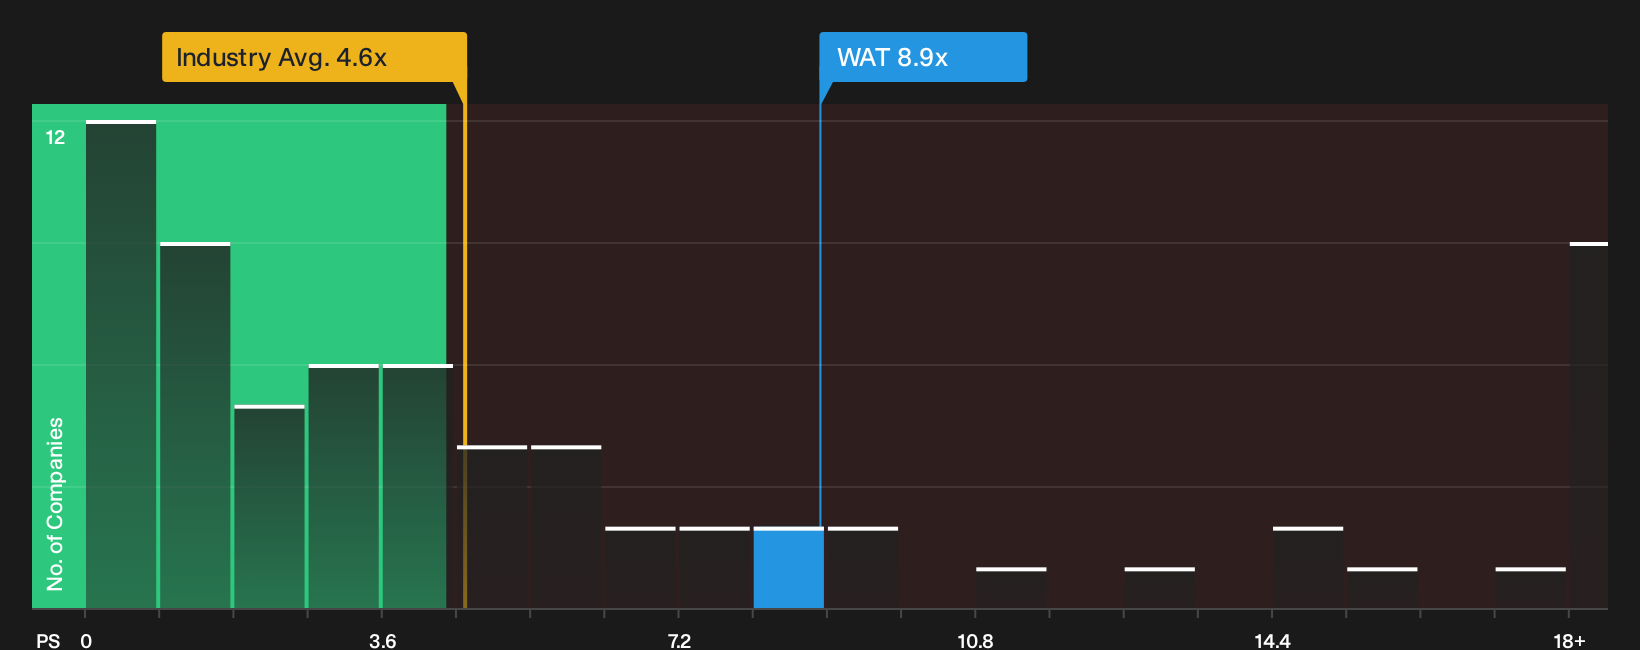
The SWS DCF model points to upside for Waters, yet the stock tells a different story when judged on its P/S ratio. At 8.9x sales, WAT trades above a fair ratio of 7.5x and well ahead of both the US Life Sciences group at 4.6x and peers at 6.2x. That gap means investors are paying a clear premium for the story. The open question is whether you see that as justified strength or valuation risk waiting for a reset.
To pressure test that sales-based view against the detailed assumptions behind future earnings, take a closer look at the full valuation breakdown, including how pricing compares across similar businesses, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Waters, with both concerns and bright spots in the story, make this a moment to move quickly and test the thesis yourself using 2 key rewards and 3 important warning signs.
Looking for more Waters investment ideas?
If you like the Waters story but want a wider watchlist, use the Simply Wall St Screener to surface focused opportunities that fit your preferred risk and return profile.
- Target resilient compounders by scanning a curated 31 resilient stocks with low risk scores that aims to keep downside in check while still offering meaningful upside potential.
- Hunt for mispriced quality by reviewing a focused 16 high quality undiscovered gems that highlights strong fundamentals the wider market may be ignoring.
- Build a more durable portfolio by filtering for a disciplined 7 dividend fortresses that prioritizes income strength alongside business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com