
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top 3 Indian Growth Stocks To Watch In September 2026
Global inflation is expected to linger according to the OECD, which keeps interest rates and borrowing costs in focus for Indian investors. In this kind of world, businesses that are financially sound and projected to grow earnings strongly can appear more attractive than lower quality momentum trades. This article highlights three Indian high growth potential stocks from our screener that analysts expect to deliver robust profit expansion over the next few years.
The three stocks discussed next are a small sample. The full screen surfaces 136 more Indian companies that combine strong forecast earnings growth with balance sheets that analysts view as acceptable for that kind of expansion.
If you want to move beyond this short list and quickly identify your own highest conviction ideas, head straight into the Healthy high growth potential screener to filter and analyze the broader set of healthy high growth prospects.
Monolithisch India (NSEI:MONOLITH)
Overview: Monolithisch India produces ramming mass refractory consumables that line induction furnaces for steel, metallurgy and foundry customers in India and Nepal.
Operations: The business generates approximately ₹1,538 million in revenue from producing ramming mass and related refractory products for furnace operators.
Market Cap: ₹26.3b
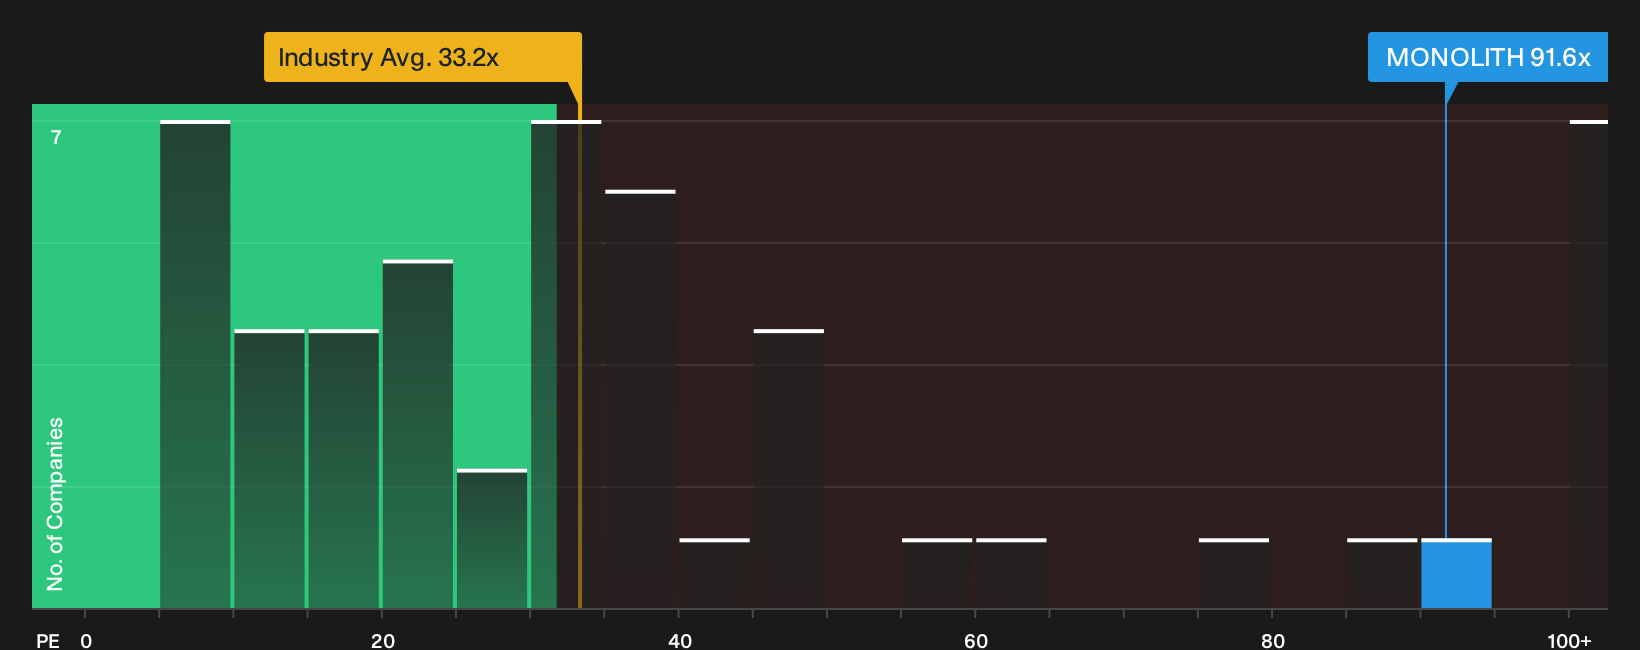
Monolithisch India is linked to the Healthy high growth potential theme, with ramming mass earnings forecast to advance 35.58% a year and quarterly profit expected to rise to ₹100.71 million, alongside a 21.9% ROE and widening margins. However, the high 91.6x P/E suggests that potential future returns may depend significantly on factors that could influence how this growth story develops.
That kind of rich P/E only makes sense if the story holds together across the full analysis report for Monolithisch India so you can judge what might be priced in.
Shaily Engineering Plastics (BSE:501423)
Overview: Shaily Engineering Plastics manufactures precision injection moulded plastic components and drug delivery devices for global pharmaceutical customers, alongside diversified consumer, automotive and industrial products.
Operations: The business generates about ₹10,246 million in revenue from customised plastic and other material components across its various product categories.
Market Cap: ₹147.6b
Shaily Engineering Plastics appeals within the Healthy high growth potential screener because its pharma focused CDMO and complex drug delivery devices are aligned with the global shift toward outsourced, high precision manufacturing for injectable therapies.
"Although the GLP-1 opportunity is expanding rapidly worldwide and Shaily has onboarded a large roster of generic players across multiple countries, delays in regulatory approvals or slower than expected generic capture from innovators could cap utilization of its expanded pen capacity and temper healthcare revenue growth."
Future earnings depend heavily on how one pressure point in its healthcare device mix ultimately filters through to pricing power and volume stability.
When so much hinges on that healthcare mix, full narrative for Shaily Engineering Plastics shows how GLP-1 exposure, capacity bets and non-pharma contracts could be quietly reshaping Shaily Engineering Plastics.

Timex Group India (BSE:500414)
Overview: Timex Group India designs, manufactures, and sells branded wristwatches across multiple fashion and luxury labels. The company aligns with the Healthy high growth potential theme through watch-led earnings expansion.
Operations: Timex Group India generates about ₹8,486 million in revenue from manufacturing and trading watches and providing related after sales services.
Market Cap: ₹73.6b
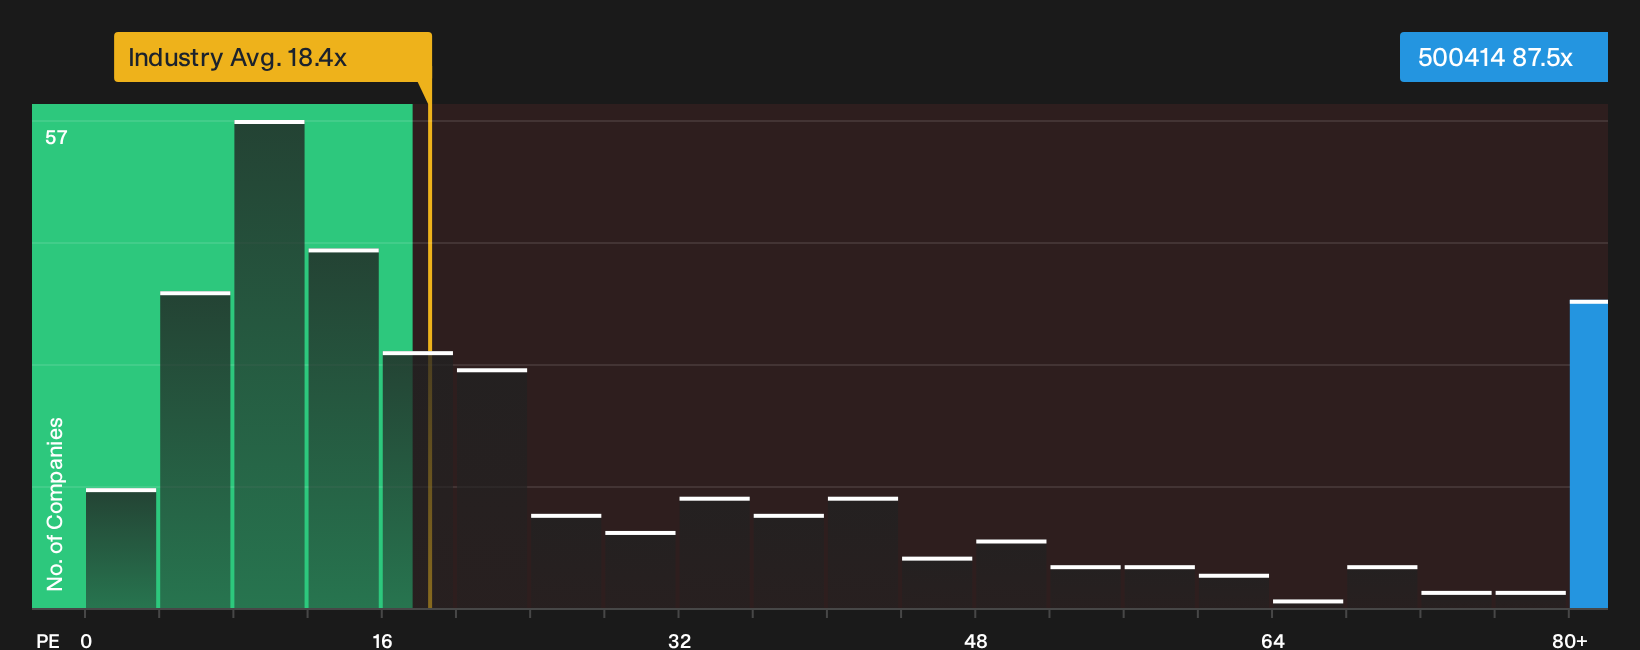
Timex Group India lines up neatly with the Healthy high growth potential theme, with earnings forecast to grow about 31.8% per year and revenue expected to rise around 24.8% annually, supported by improving profit margins and a high projected ROE. However, the rich 87.5x P/E means the investment outcome increasingly depends on how one key pressure point in its branded watch growth story is resolved.
If that pressure point has your attention, review the 2 key rewards and 1 important warning sign to see what might be accelerating or stalling the Timex Group India story.
Seeking Alternatives Before The Crowd
Fresh opportunities rarely stay quiet for long. Some are already building breakout momentum while others are still under the radar for now. Consider acting early instead of reacting too late.
- Identify resilient compounders at an earlier stage by scanning a curated list of solid balance sheet and fundamentals (198 results) that filters for sturdy finances before the crowd focuses on the same names.
- Gain exposure to structural themes by checking the curated 39 power grid technology and infrastructure stocks while policy, capital expenditure and earnings expectations are still being incorporated into prices.
- Explore potential turnaround energy names by reviewing a hand picked 36 elite gold producer stocks before capital flows and sentiment move away from less-followed operators.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com