
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Elite Australian Dividend Stocks To Own In September 2026
With the 10 year US Treasury yield hitting its highest level since 2007, income seekers are suddenly spoiled for choice. Cash and bonds offer chunky payouts, which means Australian dividend stocks need to work harder to earn a place in your portfolio. That pressure creates opportunity. In this article you will see three high yielding Australian companies that combine income strength with disciplined dividend habits.
The three stocks covered below are just a sample, and the full Dividend Powerhouses idea surfaced 39 more companies with yields above 3% and equally compelling income stories that are not discussed here.
If you want to go straight to the source and identify, filter and analyze those opportunities in one place, head into the Dividend Powerhouses (3%+ Yield) screener.
BHP Group (ASX:BHP)
Overview: BHP Group is a global resources company that mines iron ore, copper and coal, which fund its sizable dividend stream.
Operations: BHP generates most revenue from Copper at about US$29.0b and Iron Ore at about US$23.9b, with smaller Coal contribution.
Market Cap: A$315.5b
For income investors, BHP Group offers a mix of scale, iron ore and copper cash generation, and a dividend profile built around free cash flow rather than financial engineering.
"Strong pipeline of copper and potash projects positions BHP to benefit from a global surge in decarbonization efforts and electrification initiatives, with rising demand for critical minerals expected to drive higher future revenues."
What matters next is how one unresolved cost pressure shapes the balance between those cash flows and future payout headroom.
That cost pressure is exactly where income resilience can either accelerate or stall, so read the full narrative for BHP Group to see how BHP Group balances payouts, projects and risk.

Evolution Mining (ASX:EVN)
Overview: Evolution Mining runs producing gold and gold copper mines in Australia and Canada, using that output to fund regular dividends above 3%.
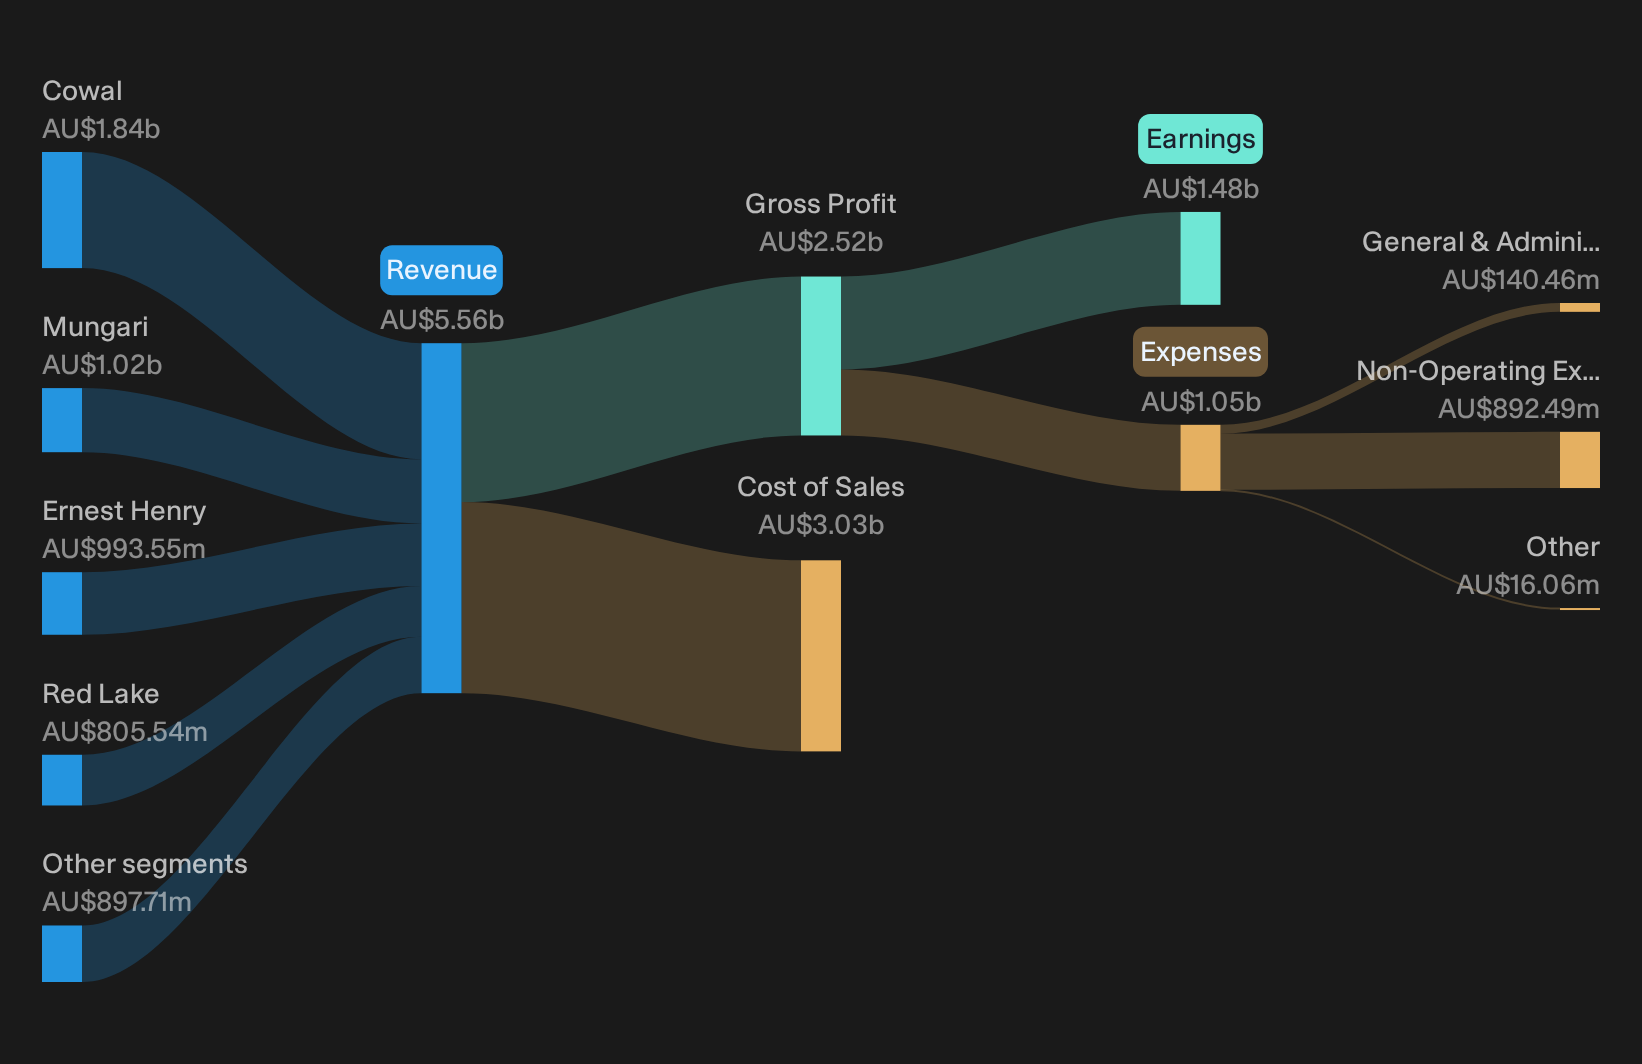
Operations: Evolution Mining earns most revenue from Cowal at about A$1.8b, Ernest Henry at about A$1.0b and Mungari at about A$1.0b, with additional contribution from Red Lake, Northparkes and smaller assets.
Market Cap: A$28.3b
Evolution Mining fits this income screen because its operating gold portfolio generates cash that currently supports a covered, policy-backed dividend stream.
"Rising compliance and labor costs, coupled with declining ore grades, may erode margins and challenge long-term earnings projections."
The key factor for assessing how resilient that payout may be over the next few years is how quietly building cost pressure reshapes unit economics.
As those unit costs rise, read the full narrative for Evolution Mining to see how Evolution Mining could still convert operational pressure into accelerating dividend and project momentum.
Commonwealth Bank of Australia (ASX:CBA)
Overview: Commonwealth Bank of Australia provides everyday banking, business finance, wealth services and insurance to households and companies in Australia and overseas.
Operations: Commonwealth Bank of Australia earns most revenue from Retail Banking Services at about A$13.4b and Business Banking at about A$9.7b, with New Zealand and Institutional Banking and Markets contributing smaller streams.
Market Cap: A$252.5b
For income investors, Commonwealth Bank of Australia matters because those everyday banking relationships generate cash flows that support franked dividends above 3% and place it in the Dividend Powerhouses screener.
"Growing competitive intensity in both digital payments and deposit products, as digital disruption accelerates and fintechs increase their activity, threatens to affect Commonwealth Bank of Australia's (CBA) traditional profit pools, putting pressure on net interest margins and fee-based revenues."
What really shapes the long term dividend story is how one slow building pressure on those core earnings pools ultimately settles.
As that pressure on core earnings builds, read the full narrative for Commonwealth Bank of Australia to see whether Commonwealth Bank of Australia's dividend engine is quietly strengthening or starting to decouple.

Seeking Fresh Alternatives For Income?
Fresh ideas move first. Once momentum builds, prices can move quickly and clear entry points may diminish before the crowd catches on, so scan these under the radar picks and consider acting early.
- Identify early breakouts in quality operators before attention increases by scanning the 16 high quality undiscovered gems while information may still provide a first move advantage.
- Follow the momentum of infrastructure demand by filtering potential beneficiaries through the 39 power grid technology and infrastructure stocks while these stories remain under the radar for now.
- Review cash generative miners tied to enduring themes by using the curated 36 elite gold producer stocks before any shift in sentiment changes your opportunity set.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com