
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Credit Acceptance (CACC) Settles Multistate Case, Is The Stock Still Undervalued?
Credit Acceptance (CACC) is back on investor screens after a multistate settlement that wraps up years of litigation and locks in concrete consumer relief, disclosure, and oversight obligations.
The latest settlement headlines have coincided with some pressure on Credit Acceptance’s share price, which is down 7.95% on a 1 month share price return and 10.99% on a 3 month share price return. However, the year-to-date share price return of 22.30% and 1-year total shareholder return of 14.39% indicate momentum that has cooled rather than completely reversed.
Scan how Credit Acceptance compares with other lenders facing regulatory pressure by reviewing a curated set of 31 resilient stocks with low risk scores that pair stronger balance sheets with tighter risk controls.For Credit Acceptance, a sharp pullback after a long run raises a simple fork in the road. Are you seeing fundamentals being reassessed, or sentiment finally cooling on a complex story?
Most Popular Narrative: 12% Undervalued
On the most followed view, Credit Acceptance trades below an implied fair value of $628.33, compared with a last close of $555.13. This puts the current debate squarely on whether that gap reflects risk or opportunity.
"A record-high loan portfolio despite recent origination and collection headwinds, combined with active share repurchases, positions the company for strong per-share earnings growth if collections stabilize and loan performance improves as projected."
See why 3 investors see Credit Acceptance as 12% undervalued.
Result: Fair Value of $628.33 (UNDERVALUED)
Still, Credit Acceptance faces real swing factors, including weaker loan performance in recent vintages and tougher competition that could pressure both cash flows and future returns.
Find out about the key risks to this Credit Acceptance narrative.
Another View On Credit Acceptance Valuation
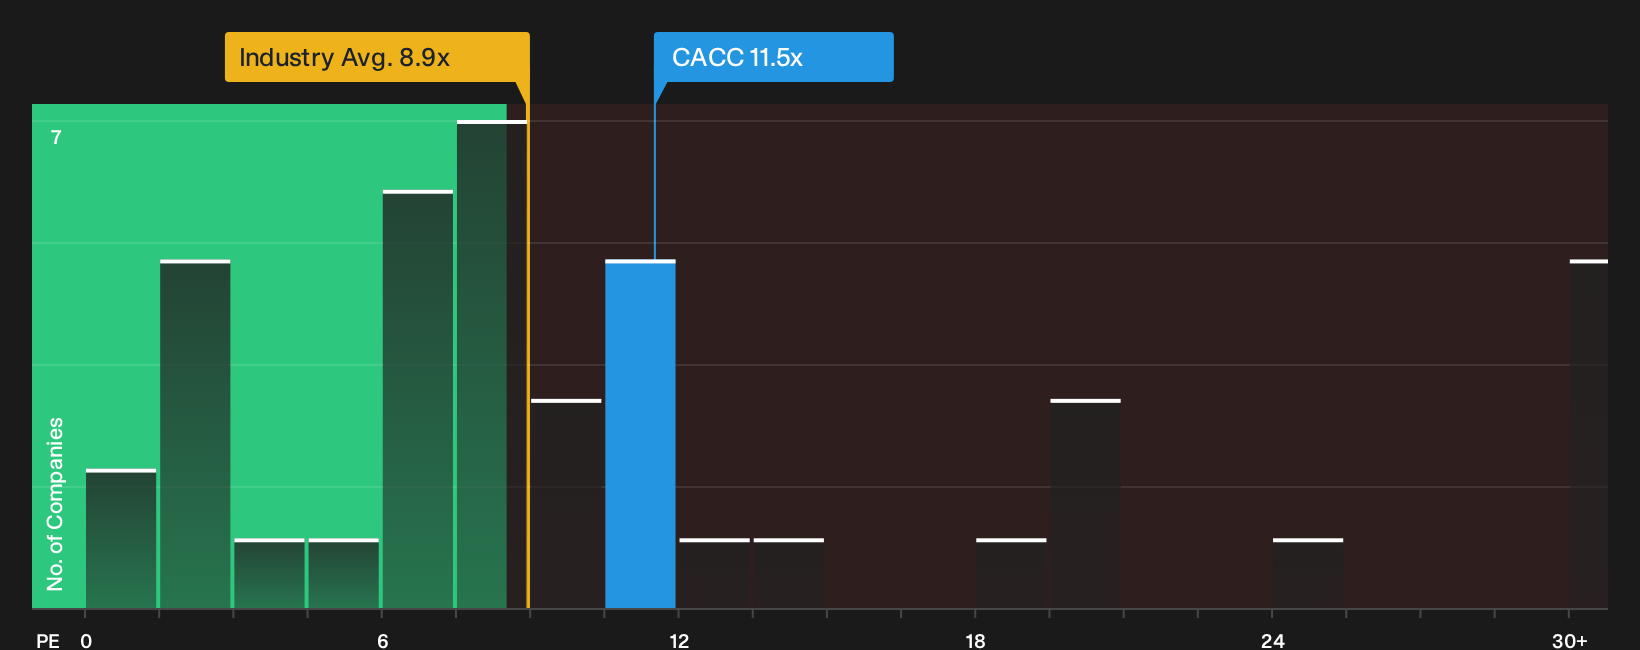
That 12% upside narrative looks very different once you look at how Credit Acceptance is priced against its peers. The stock trades on an 11.5x P/E, above both the US Consumer Finance industry at 8.9x and its peer average of 10.3x, yet below a fair ratio estimate of 13.8x. Is the market already paying up for quality, or still leaving room for a re-rating toward that fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on Credit Acceptance after the settlement and valuation debate are understandable, so move quickly, review both sides of the data, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Credit Acceptance?
Do not stop at Credit Acceptance alone. Use this pullback as a prompt to refresh your watchlist with ideas that match your risk and return goals.
- Target potential mispricing by scanning a focused pool of quality candidates through the 30 high quality undervalued stocks.
- Strengthen your downside protection by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (23 results).
- Focus on income opportunities via the 7 dividend fortresses to identify stocks with dividend-paying histories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com