
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Arizona Packaging Expansion Means For Amkor Technology (AMKR) Shareholders
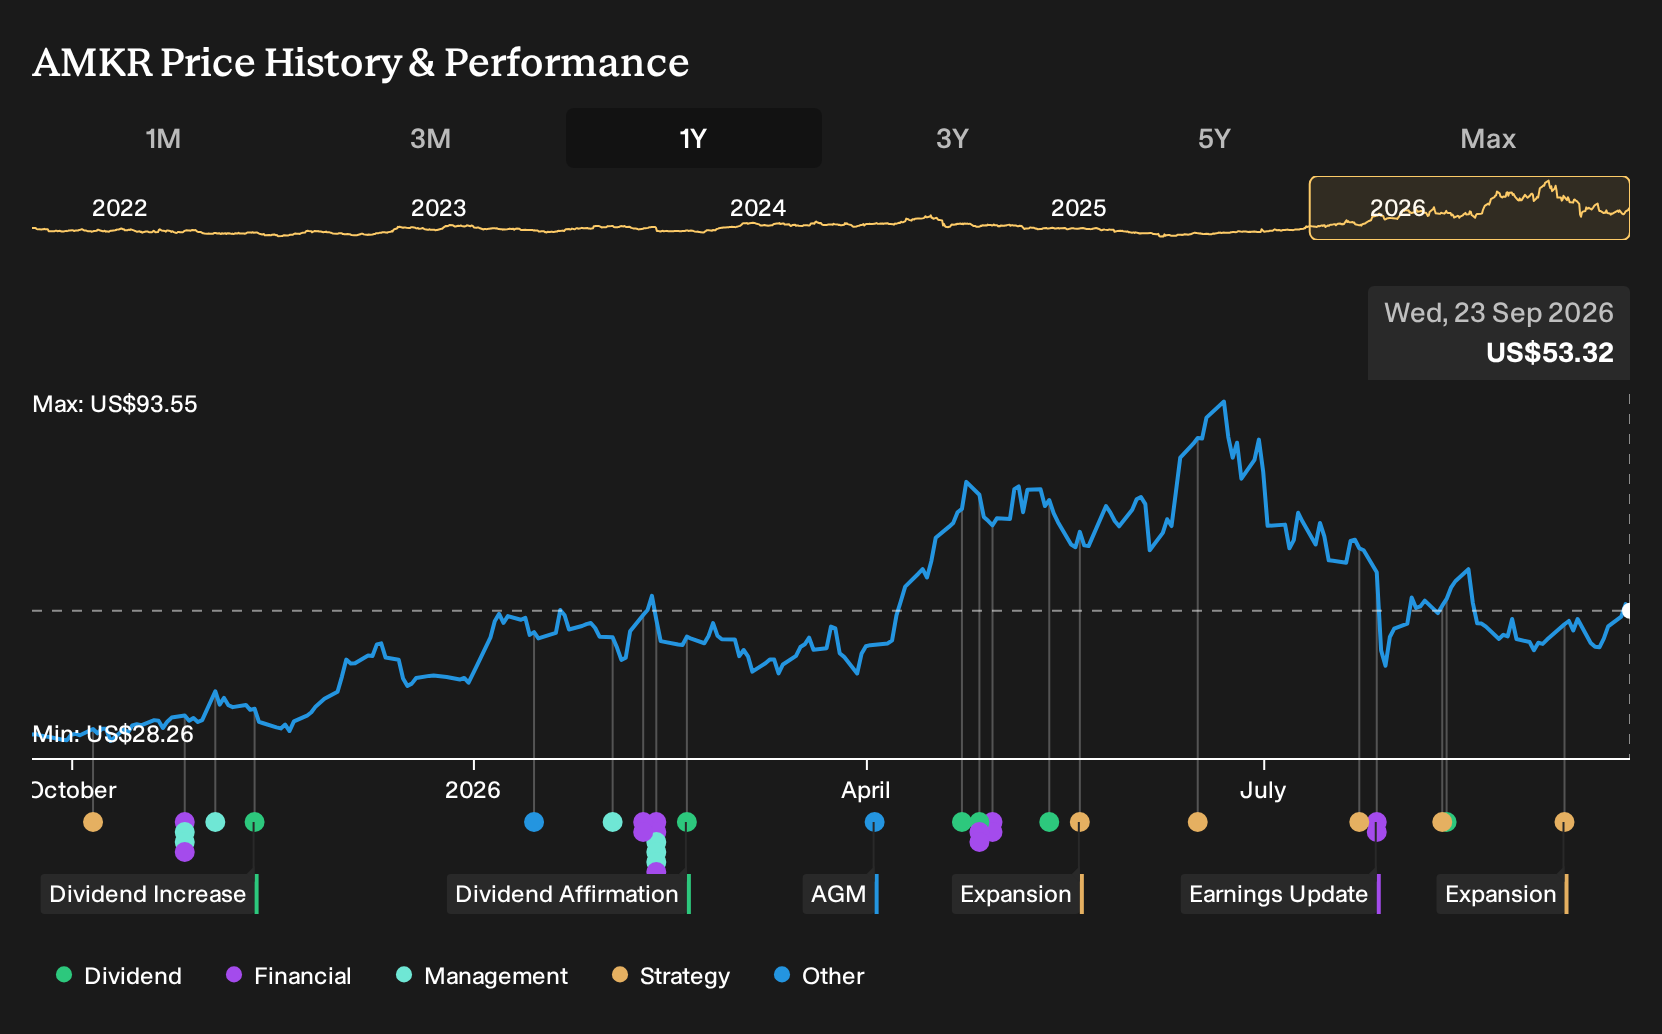
- Amkor Technology recently confirmed phase 2 of its Arizona advanced packaging and test campus, which is intended to become the first high volume U.S. OSAT facility focused on advanced semiconductor packaging and to support domestic chip supply chains.
- The expansion signals that Amkor Technology is committing further capital and headcount to meet strong customer demand for high value packaging, reinforcing its push to secure long term advanced capacity in the United States alongside its Asian footprint.
- We will now explore how Amkor Technology's investment narrative could be reshaped by the Arizona advanced packaging expansion and added U.S. capacity.
Amkor Technology Investment Narrative Recap
To be a shareholder in Amkor Technology, you need to believe that outsourced advanced packaging and test will stay central to AI computing, automotive electronics and complex smartphones. The Arizona build out fits that view, since it raises U.S. capacity in high value packaging. In the short term, the key swing factor is how quickly that new footprint gets filled with profitable AI and advanced programs.
The biggest risk is simple. Heavy spending on Arizona and other sites could leave Amkor Technology with underused factories and pressure on margins if demand falls short of expectations. Supply chain shifts, the SiP move to Vietnam and any prolonged softness in Communications could all make that utilization question harder.
The Arizona phase 2 announcement is the clearest recent marker for that thesis. It ties directly to the advanced packaging catalyst that many investors focus on, because it creates the first high volume U.S. OSAT facility dedicated to these services and deepens the link between Amkor Technology and large chip customers that want domestic packaging capacity.
This same decision also sits next to the identified risks. Added U.S. and global capacity, funded with sizeable capex and convertible debt, will only help returns if loading stays healthy and customer programs ramp as planned. For anyone following Amkor Technology, the Arizona campus has effectively become the real world test of both the upside potential and the utilization risk at the same time.
What The Amkor Technology Consensus Is Baking In
Amkor Technology's analyst narrative points to revenues of US$10.0b and earnings of US$904.8m by 2029. That outlook lines up with an assumed 10.4% yearly revenue growth rate and implies an earnings increase of about US$349m from US$555.5m today.
Uncover why the indicator from Amkor Technology's fair value shows a 43% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
One alternate take on Amkor Technology focuses on potential upside from AI projects ramping faster than expected. The most optimistic analysts were penciling in about US$10.7b of revenue and US$1.2b of earnings by 2029, well above consensus. Those views were set before the Arizona expansion news, so treat them as moving pieces and compare several angles before deciding what this story means for you.
Explore 4 other Amkor Technology fair value estimates, including one that suggests as much as 82% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Amkor Technology research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amkor Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amkor Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amkor Technology?
Once you have a view on Amkor Technology, it can help to widen the lens and compare it with other stocks that share similar strengths or appeal to a different part of your portfolio. The Simply Wall St Screener lets you do that quickly by filtering the market down to what actually fits your checklist.
- If you care most about valuation support and balance sheet strength, start with a curated set of companies trading on what our models flag as attractive prices through the 30 high quality undervalued stocks.
- If resilience and downside protection are higher on your list, focus on businesses with steadier risk profiles using a tailored group of 31 resilient stocks with low risk scores that could help smooth portfolio volatility.
- If you want quality with room to grow, scan a focused pool of stocks with solid fundamentals that are not widely followed yet through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com