
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top 3 Canadian Dividend Stocks To Watch In September 2026
With US Treasury yields at their highest level since 2007, reliable income from Canadian dividend payers suddenly looks far more interesting. Higher bond yields make every dollar of income compete harder for your attention, so stocks offering more than a 3% yield, backed by solid coverage and steady growth, can appeal. This article walks through three high-yield Canadian dividend stocks from that universe that may be worth a closer look.
The three stocks in this article are just a sample set, and the full screen surfaced 17 more dividend payers with similarly robust coverage and compelling narratives that are not covered here. To identify and analyze the highest conviction ideas for your watchlist, head straight into the Dividend Powerhouses (3%+ Yield) screener.
Sun Life Financial (TSX:SLF)
Sun Life Financial leans on its life insurance and wealth-management engines to generate recurring premiums and fee income that can support a 3%+ dividend. This places it squarely in the Dividend Powerhouses theme for investors who prioritise steady cash returns.
Sun Life Financial runs a broad mix of insurance, wealth and health solutions across Canada, the U.S. and Asia, with revenue anchored in Canada at about CA$15.7b and supported by the U.S. at CA$13.0b, Asia at CA$2.6b and Sun Life Asset Management at CA$7.7b, giving the group a market value near CA$63.3b.
"Growing use of private credit, real assets and alternative strategies among institutional and wealth clients is aligning with Sun Life Asset Management's capabilities in direct lending, private credit and infrastructure. This can support fee-related earnings and broaden the mix of recurring revenue."
What really matters now is how one quiet shift in capital allocation ultimately feeds through to earnings power and dividend headroom.
That quiet shift in capital makes the full narrative for Sun Life Financial especially worth your time, because it maps how recurring fees and capital decisions could be decoupling from headline markets.

Whitecap Resources (TSX:WCP)
Whitecap Resources is a Calgary based producer of crude oil and natural gas that uses its Western Canadian fields to generate the cash flow behind its 3%+ yield. It has about CA$7.2b in exploration and production revenue and a market value near CA$22.0b.
For income investors, Whitecap Resources brings something different to this dividend screen, because the payout is tied directly to cash coming out of the ground rather than a utility style tariff or a bank fee stream.
"Acceleration of debottlenecking at Kaybob toward productive capacity of 115,000 to 120,000 BOE per day by year end 2026 brings forward the shift to a free cash flow mode, which can support higher funds flow, stronger net margins and, in time, higher earnings power per share."
The real test now is how one unseen cost and volume pressure ultimately shapes the cash available for that monthly dividend cheque.
Those moving pieces of cost and volume pressure make the full narrative for Whitecap Resources the next step if you want to see how Whitecap Resources balances risk with accelerating payout potential.

North West (TSX:NWC)
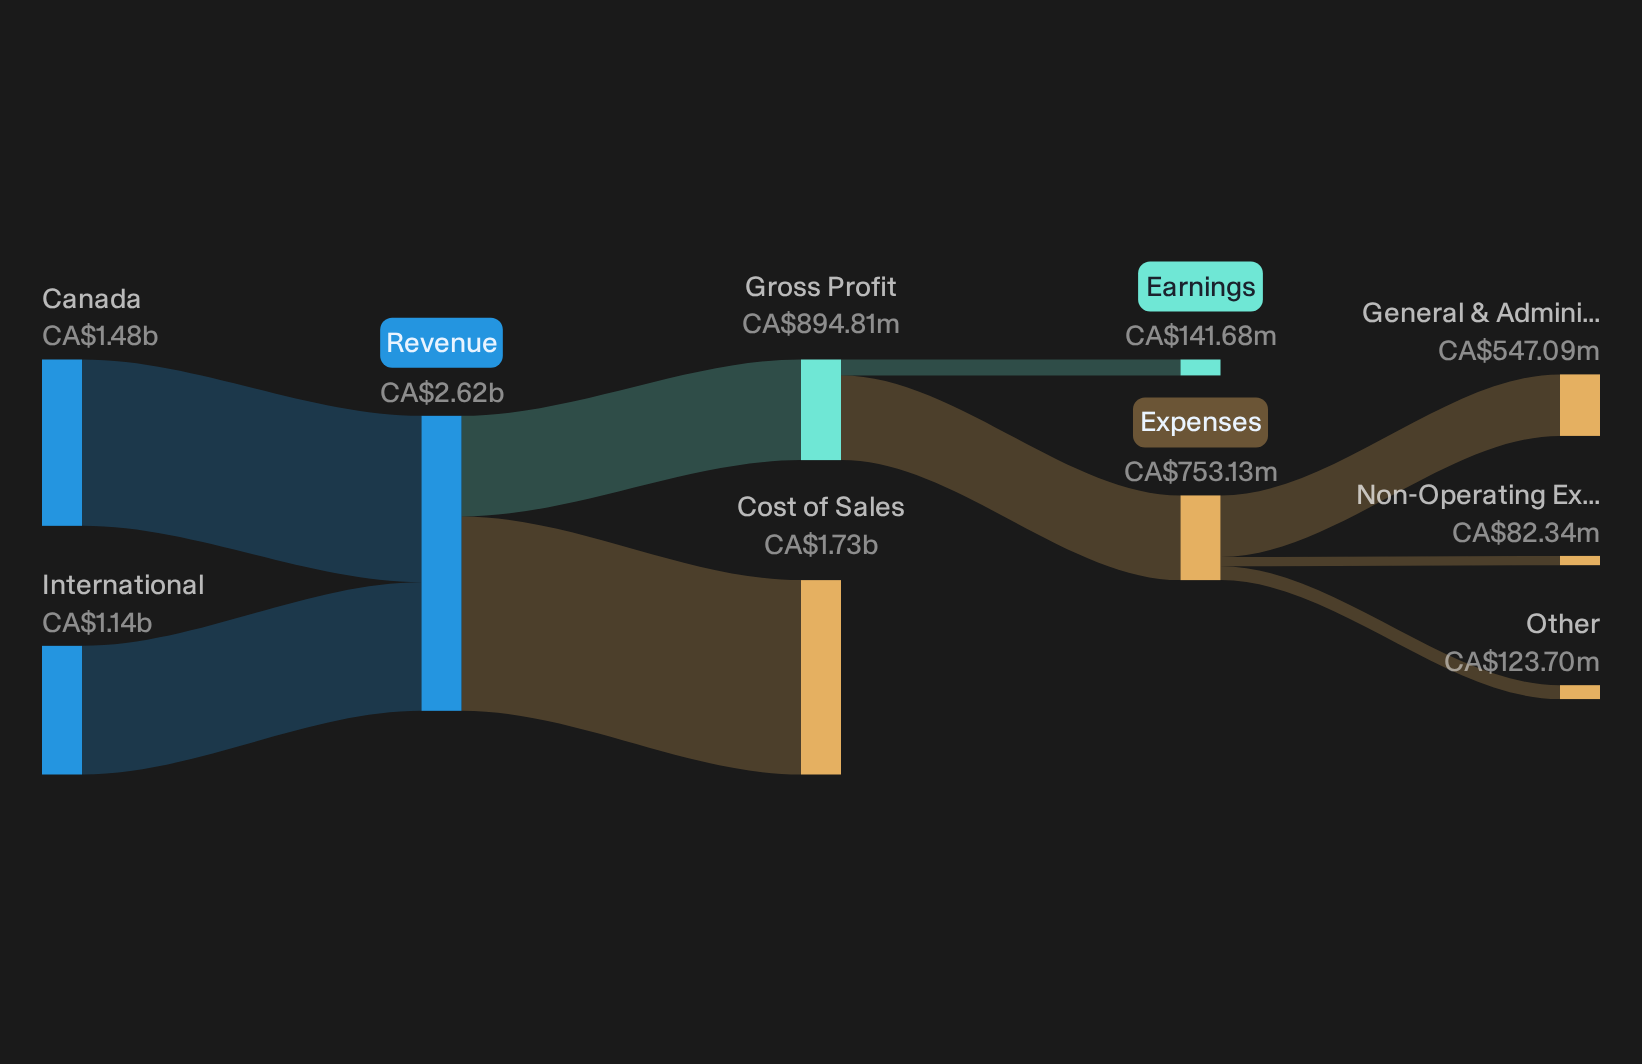
The North West Company runs grocery, general merchandise and fuel outlets like Northern, NorthMart and Giant Tiger in remote communities. In these locations, everyday essentials help keep cash flow steady enough to back a 3%+ dividend. The company generates about CA$1.5b of sales in Canada and CA$1.1b internationally, with a market value near CA$2.5b.
North West offers a 3.19% yield supported by recurring income from essential retail in under-served regions, a P/E of 17.6x below consumer peers and net profit margins around 5.4%. Dividend appeal rests on that steady cash generation, depending on how one unseen pressure in freight and wage costs plays out.
Those shipping and wage pressures make the analysis report for North West a smart next step if you want to see what could quietly reshape North West's dividend engine.
Curious About What You Might Be Missing?
Fresh ideas often move first. Breakout momentum, flying under the radar for now, can be noticed quickly once the crowd arrives. Scan new stock angles before the edge drops and consider acting while opportunities are still less visible.
- Identify resilient dividend engines and stress test your income plan with a curated 1 dividend fortresses before yields in other areas draw more market attention.
- Focus on real earnings momentum instead of headlines by using a hand picked 6 high quality undervalued stocks while these valuations still appear to be under the radar.
- Consider positioning ahead of potential infrastructure developments by scanning a focused 39 power grid technology and infrastructure stocks before the market fully prices in that theme.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com