
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dropbox (DBX) Following Q2 Results Looks Fully Valued Despite Margin Strength
Dropbox (DBX) moved back into focus after its Q2 report, as the company slightly outpaced revenue expectations and delivered stronger operating income and billings than analysts had projected.
Despite the post-earnings pop, Dropbox’s recent momentum has cooled, with the share price down 9.33% over the past week and 1.89% over the past month. However, a 36.44% three-month share price return and 27.07% year-to-date share price gain contrast with a more modest 9.12% one-year total shareholder return. This suggests that enthusiasm around recent results and shifting perceptions of risk has been much stronger in the short run than over longer holding periods.
Scan the productivity software space for other potential breakouts by reviewing our hand-picked list of 30 high quality undervalued stocks that share some of Dropbox's demand tailwinds.
Bulls point to Dropbox’s cash generation and recent share price strength. Bears focus on flat revenue and a premium to the average analyst target. Which story does the current valuation actually support next?
Most Popular Narrative: 5% Overvalued
Dropbox closed at $34.22 against a most-followed fair value estimate of $32.60. The narrative currently treats the stock as slightly ahead of that anchor, while still assuming the business can support higher profitability over time.
Persistent emphasis on operational efficiency via infrastructure optimization, disciplined hiring, and lower marketing spend has resulted in sustained improvements in non-GAAP operating margins and free cash flow, enhancing the company's ability to invest in long-term growth areas while also supporting increasing earnings and cash flow per share. Increasing focus on data security, privacy, and third-party integrations with platforms like Slack, along with ongoing investments in backend improvements, aligns Dropbox with evolving industry-wide regulatory demands and enterprise expectations, strengthening its competitive positioning for large, security-conscious customers, and providing a foundation for stable enterprise revenue and longer-term margin improvement.
See why 10 investors see Dropbox as 5% overvalued.
Result: Fair Value of $32.60 (OVERVALUED)
Still, revenue and annual recurring revenue are both in decline. Competitive pressure on pricing could challenge Dropbox's ability to defend current margins.
Find out about the key risks to this Dropbox narrative.
Another View: Dropbox Through Earnings Multiples
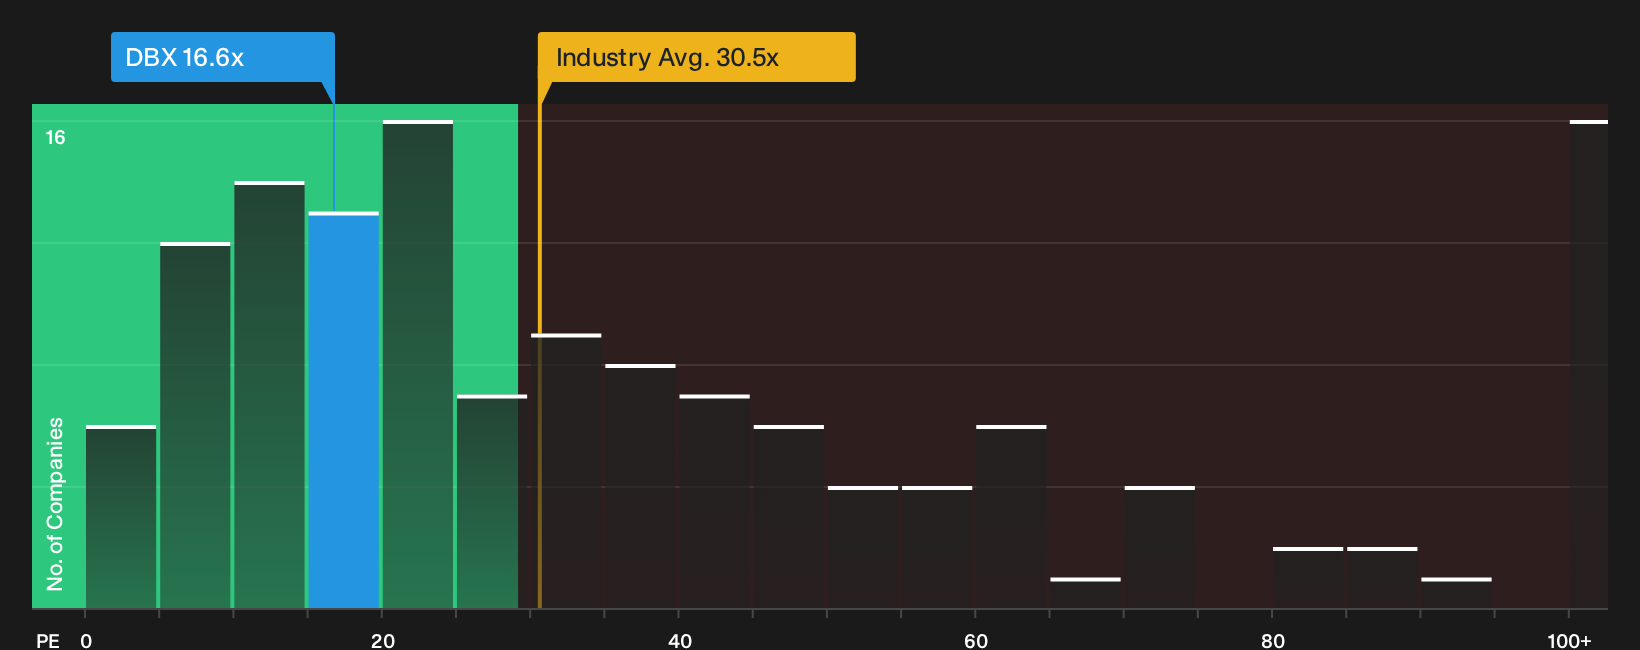
While the most popular narrative tags Dropbox as about 5% overvalued versus a $32.60 fair value, the market’s own P/E math paints a different picture. At 16.8x earnings, DBX trades well below both the US Software industry at 30.5x and peers at 35.3x, and even under the 22.5x fair ratio.
That gap suggests investors currently price in more risk than those benchmarks imply, which could either reflect justified caution on shrinking revenue or a window where expectations are unusually low. Which story you believe has more weight in your portfolio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Dropbox valuation can be useful. Let that tension push you to inspect the numbers for yourself, then test your thesis against 2 key rewards and 3 important warning signs.
Want more ideas beyond Dropbox?
Do not stop at a single ticker. Use the screener to quickly spot fresh setups, compare quality, and pressure-test where Dropbox sits in your watchlist.
- Hunt for mispriced opportunities by scanning a focused set of 30 high quality undervalued stocks that pair solid fundamentals with compressed expectations.
- Prioritize resilience by filtering for 30 resilient stocks with low risk scores that aim for steadier returns and less emotionally draining volatility.
- Target future leaders by zeroing in on 16 high quality undiscovered gems that have strong balance sheets and are still off most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com