
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Watsco (WSO) Just Gave Investors Something To Think About
On 14 September, Watsco (WSO) agreed to buy The Granite Group, a plumbing and HVAC distributor with about US$500 million in annual sales across seven Northeast states, and also lifted its annual dividend.
These moves come after a mixed stretch for Watsco’s stock. The share price is up 7% over the past week and 4.7% over 30 days, but down 21.1% across three months, and its 1-year total shareholder return has declined 13.9%.
Compare Watsco's acquisition driven story with other potential HVAC and infrastructure suppliers by scanning our hand picked list of list of solid balance sheet and fundamentals (23 results).
Bulls see Watsco using Granite Group to scale higher margin distribution, while bears point to the recent share price slump and modest value score. Which story do the current valuation markers lean toward?
Most Popular Narrative: 14% Undervalued
Watsco closed at $325.37, while the most followed narrative pegs fair value at $379.20 using an 8.2% discount rate. The gap rests on how confidently investors view margin recovery, cash strength and the Granite Group acquisition working together.
Watsco maintains a strong balance sheet with $430 million in cash, no debt, and over $3 billion in equity, allowing them to strategically respond to market conditions and invest in growth opportunities, which could lead to enhanced long-term revenue and earnings.
See why 11 investors see Watsco as 14% undervalued.
Result: Fair Value of $379.20 (UNDERVALUED)
Still, that narrative can unravel if tariffs squeeze pricing power or if the A2L product transition disrupts refrigerant supply and crimps Watsco’s margins.
Find out about the key risks to this Watsco narrative.
Another View on Watsco’s Valuation
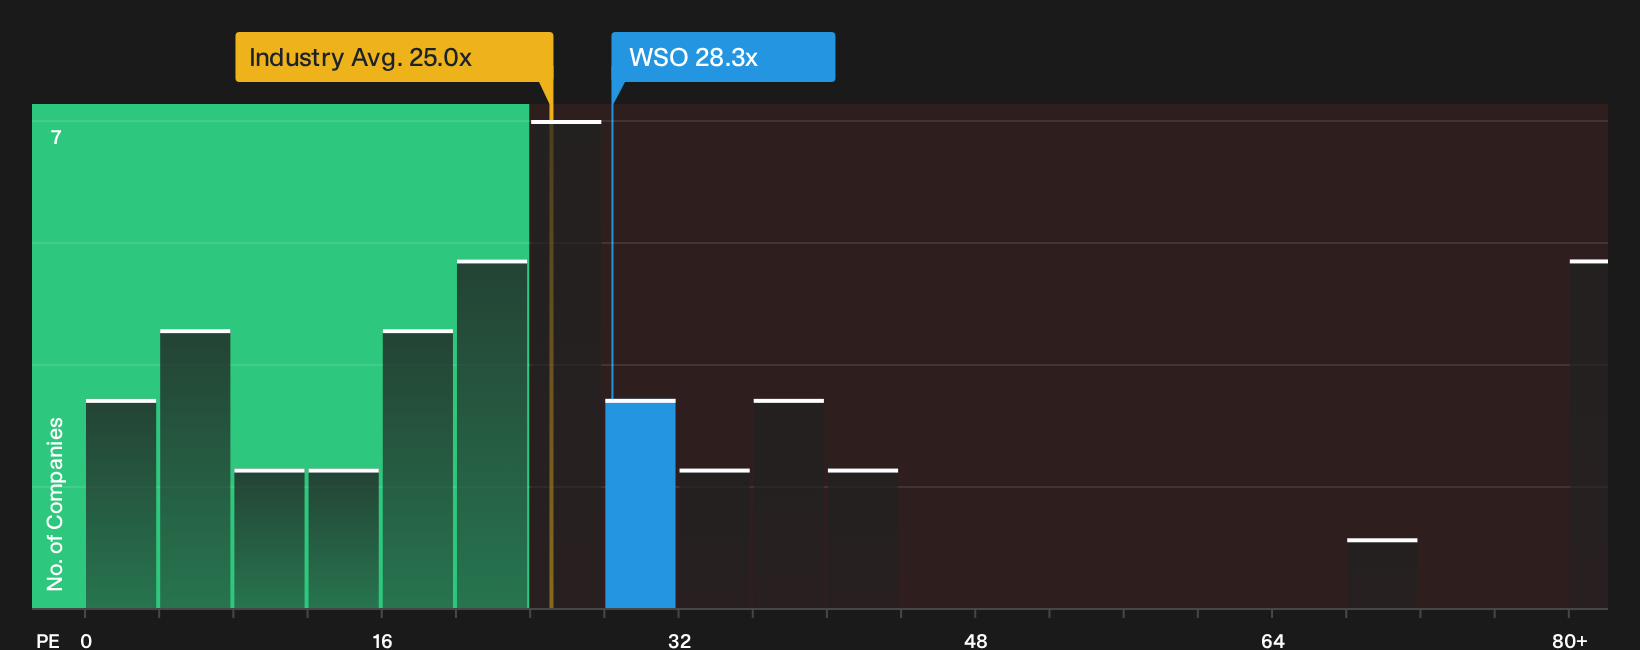
The first story paints Watsco as 14% undervalued using a fair value of $379.20. Yet the current P/E of 28.3x sits above both the US Trade Distributors average of 24.4x and the 25.8x fair ratio, which signals investors are already paying a premium. Is that premium justified if margins stay under pressure?
To see how that premium lines up with the underlying numbers and where the valuation gap could close from here, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Watsco’s value can either paralyze you or push you to check the underlying data and form a clear stance. If you want a quick snapshot of both the upside case and the main concerns that investors are watching, start with 2 key rewards and 1 important warning sign.
Looking for more Watsco style investment ideas?
If you stop with Watsco, you risk missing other opportunities that fit your goals, risk profile, and income needs across the wider market.
- Chase value opportunities by scanning a curated set of 29 high quality undervalued stocks that combine quality fundamentals with prices that still look reasonable on key metrics.
- Build a steadier income stream by reviewing 7 dividend fortresses that focus on higher yields backed by underlying financial strength.
- Guard your capital by checking out 30 resilient stocks with low risk scores filtered for balance sheets and risk scores that aim to limit unpleasant surprises.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com