
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Did DICK'S Sporting Goods (DKS) Shares Move Today?
Multiple class action lawsuits targeting DICK'S Sporting Goods (DKS) and its Foot Locker acquisition have pushed legal risk to the foreground after allegations of misleading disclosures around inventory issues and growth expectations.
The share price reaction has been harsh. DICK'S Sporting Goods has a 1-day share price return of 8.34% and a 7-day gain of 8.26%. However, the 30-day share price return is down 26.90% and the 90-day move is down 43.47% as investors reassess growth and legal risk following the Foot Locker update and recent debt offerings.
Pressure test DICK'S Sporting Goods against peers facing legal or sentiment overhangs by scanning our hand picked list of 30 resilient stocks with low risk scores for potentially steadier alternatives.
So is the sharp reset in DICK'S Sporting Goods mainly a verdict on its Foot Locker execution and legal overhang, or has sentiment overshot where the fundamentals and current valuation actually sit?
Most Popular Narrative: 19% Overvalued
DICK'S Sporting Goods closed at $133.94, while the most followed valuation story pins fair value closer to $112.77. This puts the recent selloff in a different light.
Management's structural response to the guidance revision rests on a consistent rhetorical architecture: the DICK'S business is performing; the headwinds are real but temporary; the investments being made today are exactly the right investments. Each claim is internally defensible. Taken together, they produce a framework in which virtually any near-term result can be framed as consistent with long-term strategy. That is not an accusation, it is a description of how the communication is built.
See why 1 investors see DICK'S Sporting Goods as 19% overvalued.
Result: Fair Value of $112.77 (OVERVALUED)
Still, the Foot Locker earnings revision and the sharper promotional pressure in footwear could both undermine the DICK'S Sporting Goods narrative if they persist or deepen.
Find out about the key risks to this DICK'S Sporting Goods narrative.
Another View On DICK'S Sporting Goods Valuation
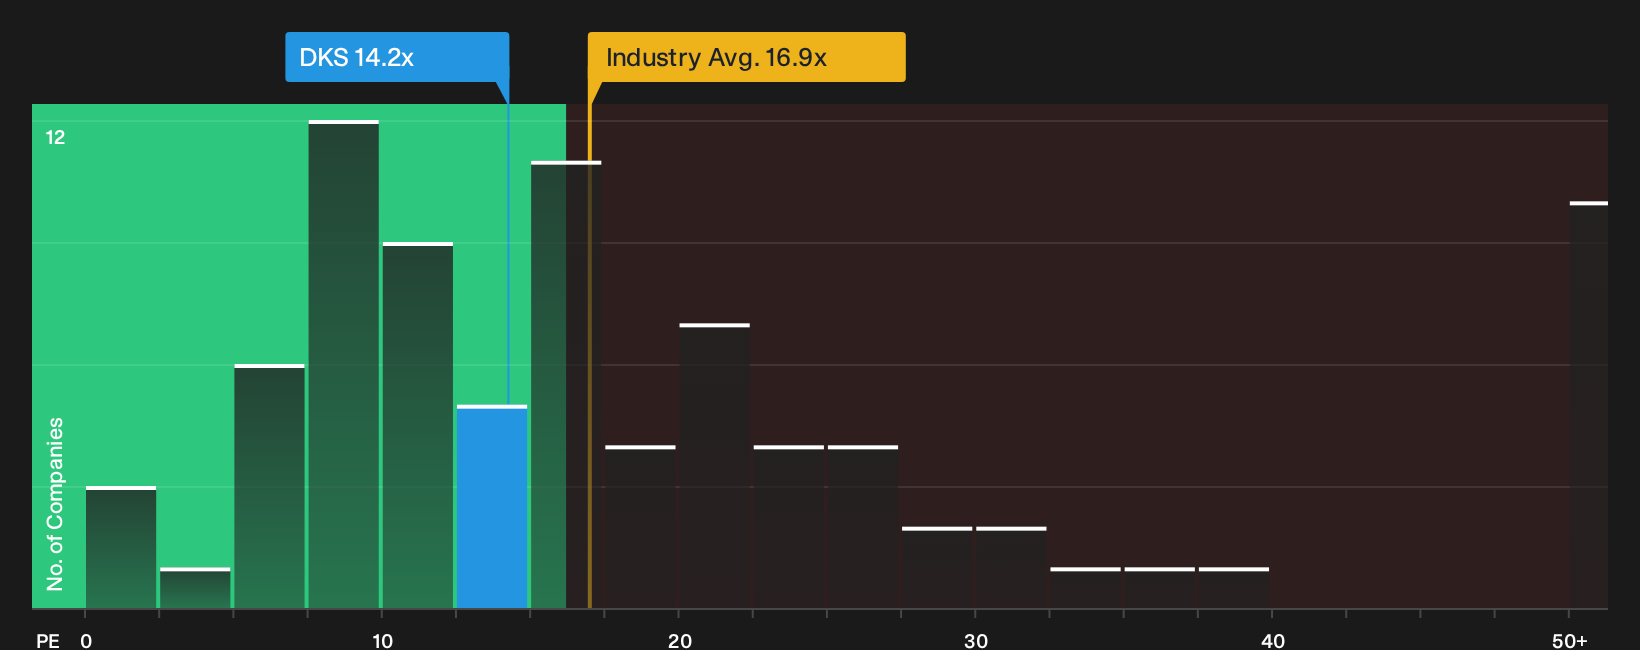
The fair value analysis that points to DICK'S Sporting Goods at $112.77 and describes the shares as overvalued contrasts with a very different message from the market multiple. The P/E sits at 14.2x, compared with 16.9x for the US Specialty Retail group and 21.5x for peers, while the fair ratio is 18.9x. That gap suggests investors are already accounting for substantial Foot Locker and earnings risk, so the question becomes whether legal and execution concerns justify such a discount or whether sentiment has moved too far.
For a closer look at what the numbers imply, including how that P/E discount could matter if the market moves toward the fair ratio, check out the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on DICK'S Sporting Goods so far. If you want to move quickly and shape your own view, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond DICK'S Sporting Goods?
Do not stop your research with DICK'S Sporting Goods alone. Broaden your watchlist with focused stock ideas that fit your risk tolerance and return goals.
- Target potential value opportunities by scanning the 29 high quality undervalued stocks that pair lower valuations with stronger fundamentals.
- Lock in potential income streams by reviewing the 7 dividend fortresses that concentrate on higher yielding payouts.
- Strengthen your downside protection by searching through the list of solid balance sheet and fundamentals (23 results) for financially resilient businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com