
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To ASM (ENXTAM:ASM) First PECVD Carbon Launch
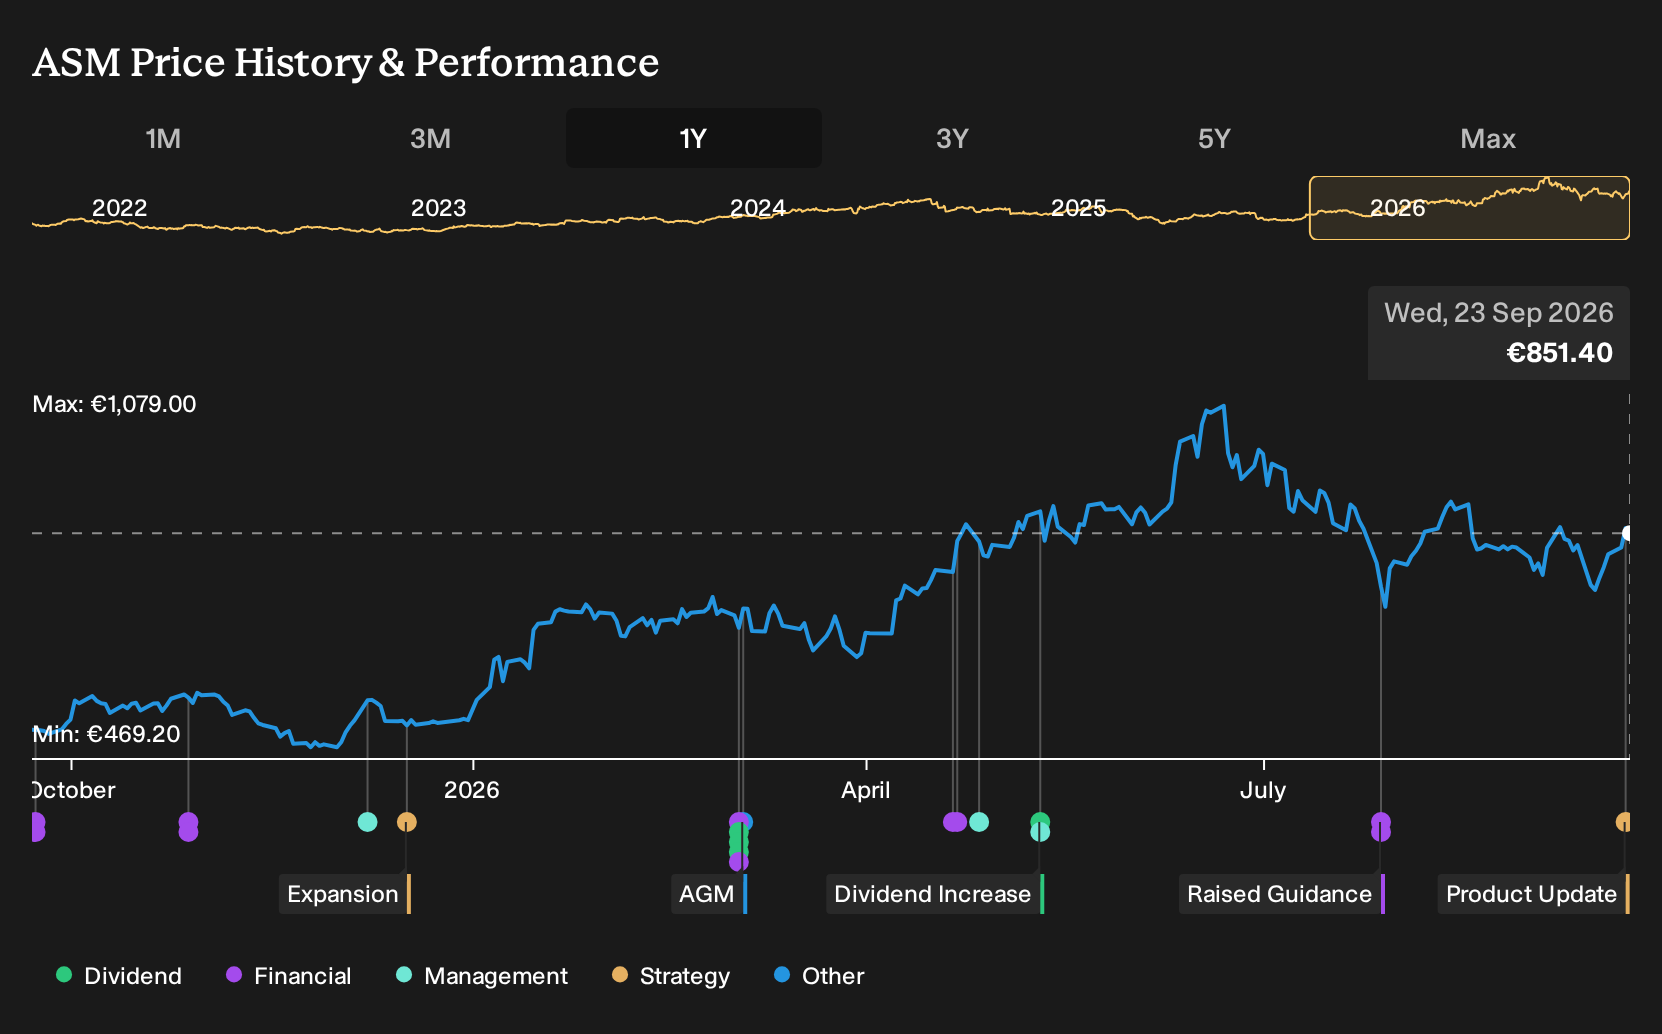
- ASM International recently launched XP8 Vertos Flowable Carbon, described as the market's first PECVD flowable carbon film that combines gap fill and planarization in a single process and is already targeted at high volume manufacturing across both logic and memory devices.
- The new Vertos Flowable Carbon process folds multiple patterning and planarization steps into one PECVD system, which could influence ASM International's cost profile, manufacturing throughput, and competitive positioning in advanced semiconductor patterning tools.
- Attention now turns to how ASM International's investment narrative could be reshaped by XP8 Vertos Flowable Carbon consolidating crucial patterning steps.
Scan how ASM International’s Vertos launch fits into the broader chip-equipment story by comparing it with hand-picked 85 AI infrastructure stocks that help power advanced computing and high-volume manufacturing.
ASM International Investment Narrative Recap
To own ASM International, you need to believe that its leadership in deposition and patterning tools will keep attracting orders as chipmakers move to more complex 3D structures. The XP8 Vertos Flowable Carbon process fits that thesis because it extends the toolkit into a new patterning niche and aims to simplify high volume manufacturing flows.
The near term swing factor still looks like order momentum and visibility, especially with the book to bill ratio expected below 1 and China related uncertainty hanging over demand. Vertos may help on future tenders, but the biggest current risk remains concentration in a few leading edge logic and foundry customers.
The share buyback that ran from July 1 to September 14, 2026 is the clearest second data point to put next to the Vertos launch. ASM International repurchased 185,522 shares for €150 million, equal to 0.38% of the equity, and then closed the plan on September 14.
For you as a shareholder, that program reinforces the picture of a business returning cash while still funding products like XP8 Vertos Flowable Carbon aimed at AI, high bandwidth memory and gate all around driven spending. Execution risk does not go away, especially with volatility in China and end markets such as power or immature memory. However, the combination of new tools and completed repurchases ties the current catalyst story directly to both the income statement and the share count.
ASM International's current analyst narrative points to revenues of €6.7b and earnings of €1.8b by 2029, based on a projected 25.8% yearly revenue growth rate. That path would require earnings to rise by about €0.7b from €1.1b today to reach the 2029 consensus level.
Discover how ASM International's fair value indicates a 32% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle focuses on upside from faster AI and advanced-node spending. The most optimistic analysts were already modelling revenue of €8.1b and earnings of €2.3b by 2029 before the XP8 Vertos news. You now have a choice: treat ASM International as roughly on track with consensus, or explore whether Vertos could pull reality closer to that higher bar.
Explore 4 other ASM International fair value estimates, including one that suggests potential upside of as much as 70% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ASM International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ASM International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ASM International's overall financial health at a glance.
Looking For More Ideas Beyond ASM International?
If you want to pressure test your ASM International thesis against other opportunities, it helps to scan a broader set of businesses with clear financial filters. The Simply Wall St Screener can point you toward different angles that match how you like to invest.
- If capital preservation sits high on your list, start with a group of companies that score well on stability. You can do this by reviewing 229 resilient stocks with low risk scores that have historically shown lower overall risk on key metrics.
- If durable cash generation matters more to you, widen the lens to a list of solid balance sheet and fundamentals (198 results) where balance sheets and fundamentals both look robust on core checks.
- If you are hunting for under-covered stories, scan a 620 high quality undiscovered gems that pair strong fundamentals with relatively low attention from the wider market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com