
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Devon Energy (DVN) Stock Still Looks Cheap Following Its 69% Run
Devon Energy has put up a strong longer term share price run, and with the stock recently around US$46.93 the key issue is how firmly that level rests on its earnings power rather than just sentiment around the sector.
- Over the past 5 years the share price has gained 69.3%, which puts more pressure on current earnings to carry a bigger share of the valuation story.
- The business is heavily tied to commodity driven cash generation, so any shift in realized prices or operating discipline can quickly change how much of today's valuation is supported by ongoing profits.
- There is a second opinion on Devon Energy worth weighing. See what analysts think Devon Energy's shares could be worth.
The stock's next move may depend on whether the present earnings base can comfortably support the valuation investors are paying for Devon Energy today.
If you want context for Devon Energy's earnings-driven story, compare it with companies in the 29 high quality undervalued stocks
Is Devon Energy a Bargain on Earnings?
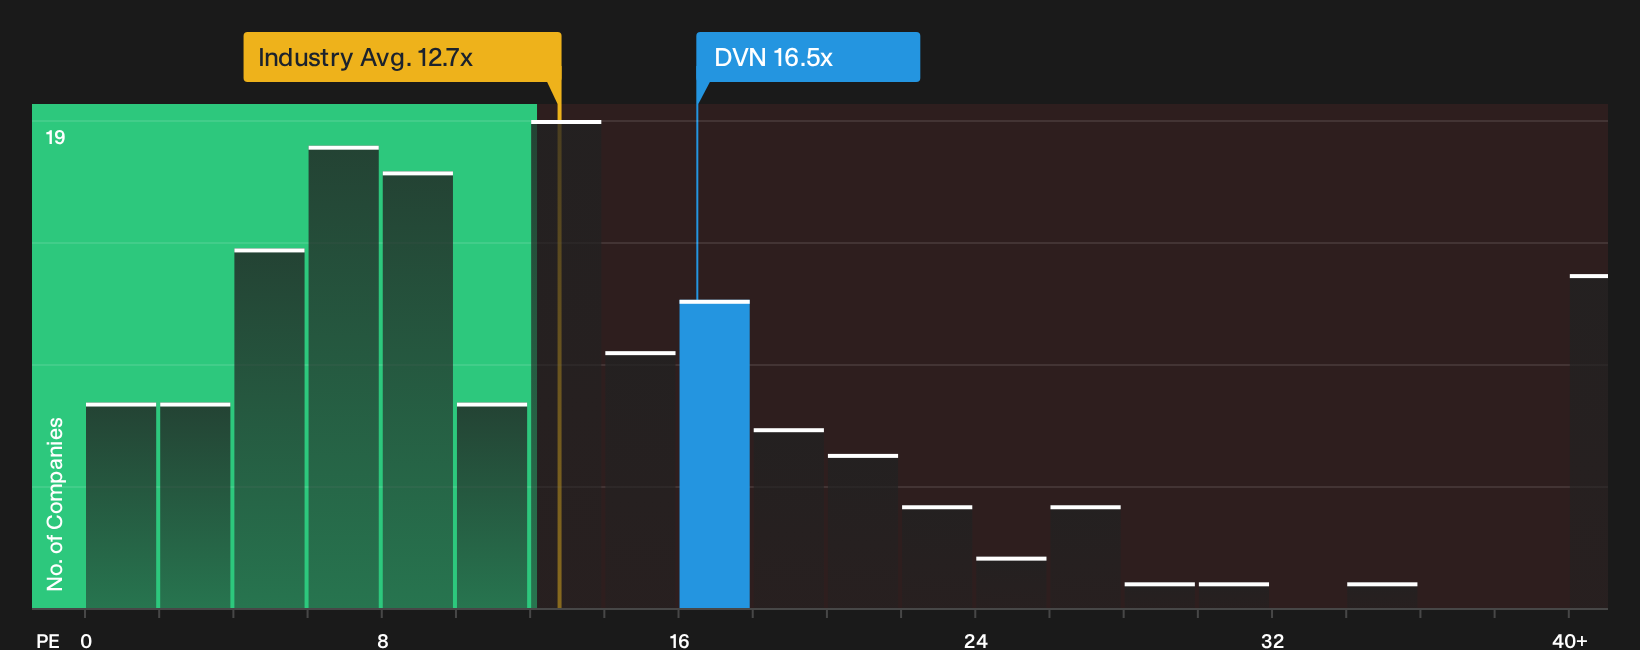
The P/E ratio is a useful fit for Devon Energy because earnings are closely tied to the cash it can pull from its producing assets year in, year out. At roughly 16.5x, the current P/E sits very close to the peer average of about 16.9x. It also stands above the wider Oil and Gas sector on roughly 12.7x, which suggests the market is willing to pay a richer price for each dollar of Devon Energy's earnings than for the sector overall.
The fair-value framework that blends Devon Energy's growth profile, margins, scale and risk points to a higher P/E than where the stock trades today, which implies the current multiple screens as undervalued on this model rather than stretched. For a holder, the key question is whether the earnings base that supports this P/E can be sustained through cycles or whether commodity swings could change the picture. Explore the numbers behind Devon Energy's P/E valuation.
The Devon Energy Narrative: What Would Justify Today's Price?
Narratives pick up where Devon Energy's P/E puzzle leaves off by spelling out which specific paths for future growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than it does today. Each narrative ties its number to a clear view on how Devon Energy's profitability, reinvestment choices and risk profile might evolve, giving you something concrete to revisit on Simply Wall St's Community page as new information comes through.
One of the top community narratives on Devon Energy: 21% undervalued
"Devon's enhanced use of AI and real-time data analytics in drilling and production is driving sustainable structural improvements in operational efficiency and capital allocation…"
Discover why this Narrative puts Devon Energy at 21% undervalued.
One more Devon Energy check that belongs beside the earnings story
Price multiples only tell part of the picture for Devon Energy, because separate fundamental checks flag potential pressure points that investors may want to weigh before leaning on the current valuation. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com