
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rio2 (TSX:RIO) Rallies As The Undervalued Narrative Faces A Valuation Test
Rio2 (TSX:RIO) has drawn fresh attention after recent share price moves, with the miner’s returns over the past month and past 3 months significantly exceeding its single-day gain of 8.3%.
For context, Rio2’s recent momentum builds on a much longer run, with a 1 year total shareholder return of 126.74% and an exceptionally high 3 year total shareholder return that signals investors have already repriced the business in a significant way.
Scan beyond Rio2’s recent surge and line up other resource stocks showing strong momentum and fundamentals with the curated 36 elite gold producer stocks.
Bulls point to Rio2’s strong multi year shareholder returns and headline valuation discount, while bears see momentum running ahead of fundamentals. Which side does the current valuation actually support?
Most Popular Narrative: 35% Undervalued
Against a last close of CA$3.90, the most followed narrative on Rio2 points to a fair value of CA$6.00, framing the recent rally as only a partial catch up to intrinsic value.
Rio2 appears significantly undervalued relative to its long‑term earnings potential. Based on the platform’s future estimates, the company is expected to generate US$562.2 million in earnings by 2030, supported by strong revenue growth reaching US$5.85 billion. Applying a conservative 16.86× P/E multiple to these projected earnings results in an implied 2030 market capitalization of US$9.48 billion, or US$5.98 per share.
When this valuation is discounted back to 2025 at 6.46% per year, the intrinsic value becomes US$4.37 per share. Converted at the current USD/CAD exchange rate of 1.3725, this corresponds to a fair value of approximately CA$6.00 per share.
See why 3 investors see Rio2 as 35% undervalued.
Result: Fair Value of CA$6.00 (UNDERVALUED)
Still, the Rio2 story leans heavily on long range forecasts and on successful execution at projects like Fenix Gold, so permitting setbacks or weaker than modeled earnings could quickly compress that perceived valuation gap.
Find out about the key risks to this Rio2 narrative.
Another View: Rio2 Through The P/E Lens
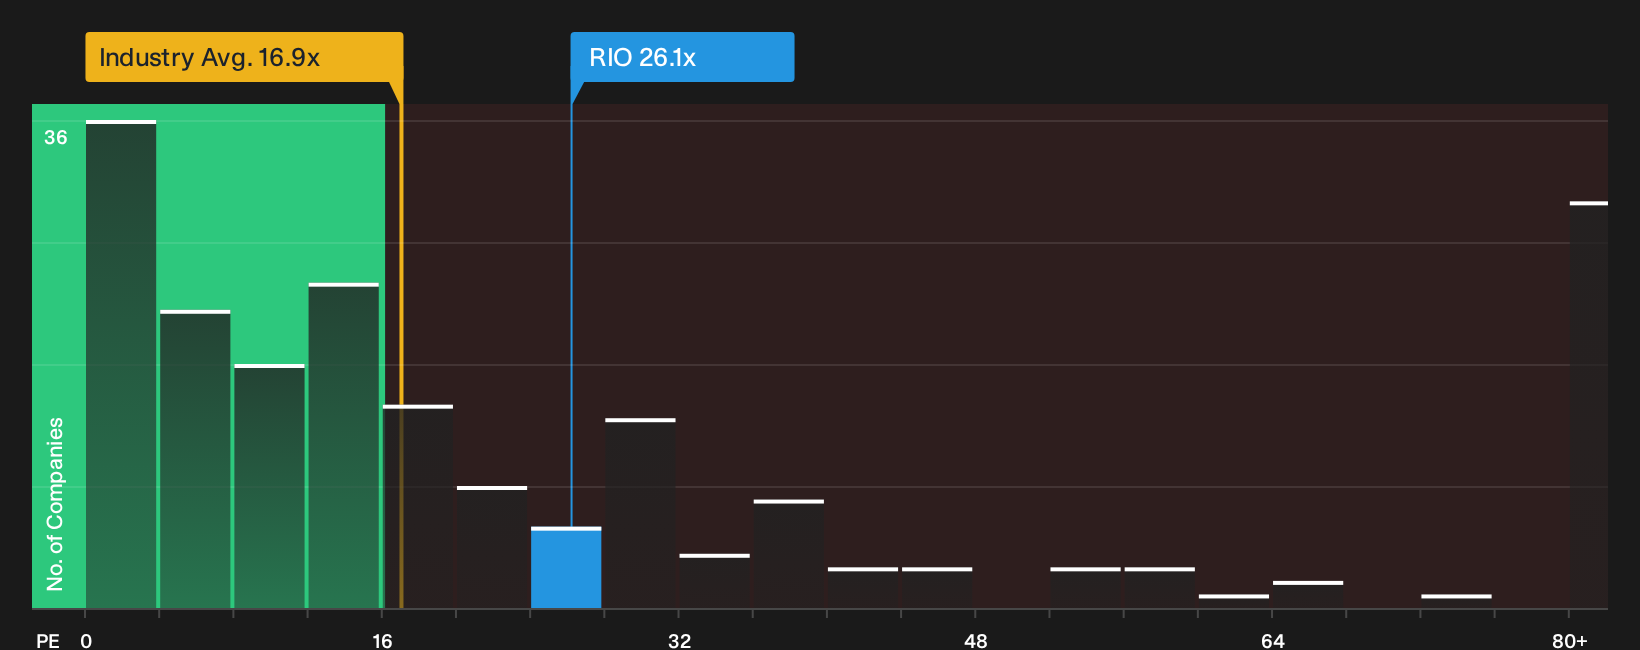
Rio2 looks very different when you swap the narrative model for a simple earnings multiple. The stock trades on a 26.1x P/E, which is cheaper than peers at 43.2x, but richer than both the Canadian metals and mining industry at 16.5x and its own fair ratio of 18.8x. That mix of relative discount and fair ratio premium raises a simple question for investors: Is this a margin of safety or a sign that expectations already run hot?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Rio2 pulling such strong historical returns and carrying mixed signals on valuation, it makes sense to stress test the story yourself and move quickly from headline to hard data. Weigh the upside and the downsides side by side with 4 key rewards and 1 important warning sign.
Looking for more Rio2-sized opportunities?
Rio2 may already be on your radar, but skipping other high potential ideas could mean missing the next stock that fits your portfolio just as well.
- Target stability first and uncover a focused 8 resilient stocks with low risk scores built around resilient businesses that aim to mute the worst of market swings.
- Chase quality at a discount by scanning through the 7 high quality undervalued stocks that combines strong fundamentals with pricing that leaves room for upside.
- Spot hidden potential early and work through a curated 9 high quality undiscovered gems before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com