
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
The Elite Portfolio: Why Savvy Investors Are Backing These Overlooked Stocks
Key Points
Ferrari boasts nearly unmatched pricing power and brand image in the global auto industry.
Its margins dwarf those of its competitors and are similar to those of luxury businesses.
BYD's vertical integration is impressive and gives the company many benefits amid the competition.
Investors might not be able to find two automakers more different than Ferrari (NYSE: RACE) and Chinese electric vehicle (EV) juggernaut BYD (OTC: BYDDY). The two contrast significantly: Ferrari focuses on ultra-luxury supercars in high-end niche markets, and BYD has made a name for itself by undercutting competitors globally through vertical integration.
Despite their strategic differences, both have compelling advantages that bode well for savvy investors and both are widely trailing the broader S&P 500 over the past year. Here's why some investors back these companies, and why potential investors should take a deeper look.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Win on Sunday, sell on Monday
The first thing savvy investors understand about Ferrari is how unique it is in the automotive industry, which is known for being low-margin, capital-intensive, and subject to economic downturns. Those narratives bounce off Ferrari just as ineffective bullets bounce off Superman. The first example of this can be found in Ferrari's margins compared to the broader industry; it's simply operating on an entirely different level.

RACE Operating Margin (TTM) data by YCharts
Not only does Ferrari's operating margin dwarf the competition, but you'll notice in the graph that its margins have consistently improved over the past decade. This tells investors that Ferrari's economic moat and competitive advantages are strengthening. Ferrari has nearly unmatched pricing power and can even generate demand for vehicles priced into the millions of dollars for special variants such as the F80.
Further, the ultra-luxury vehicle maker boasts a high rate of repeat and loyal customers, often because to get in line to purchase more rare editions, you need a track record of prior purchases. It's not all that simple to just buy a Ferrari.
Ferrari also boasts high barriers to entry because the company's historic racing division consistently passes down racing technology to use in its street-legal vehicles, with a long list of patents and engine technology that few can replicate, or have the brand name to sell into retail markets.
One reason Ferrari's stock lost momentum was the unveiling of its first-ever full-electric vehicle, the Luce. The Luce design faced an onslaught of criticism and jokes, with even former Ferrari Chairman and President Luca di Montezemolo suggesting the company remove the prancing horse logo from the new supercar. Then Ferrari did what it essentially always does and sold out of its entire production target for 2026 within a couple of months, according to the Financial Times.
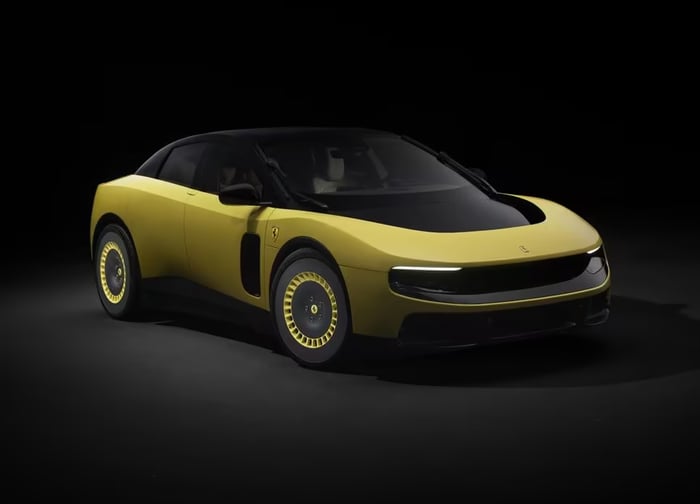
Ferrari's Luce. Image source: Ferrari.
Many investors might skip over the automotive industry due to its low margins, but savvy investors know that Ferrari flips the negative automotive narratives on their head, continues to have impressive competitive advantages, and will have no issue amid the transition to EVs.
All about vertical integration
Another unique automotive stock that savvy investors are backing is the juggernaut EV and hybrid maker out of China: BYD. Already, the EV maker's growth has been explosive, surpassing Tesla last year in EV sales (not including BYD's hybrids), and when adding its hybrid sales, passing Detroit icons Ford Motor Company and General Motors to become the fifth-best-selling automaker by volume in the world.
BYD isn't resting on its achievements and, if anything, is making another aggressive push with the target of catching Toyota Motor's global sales volume of about 11.3 million vehicles, by 2031. Make no mistake, this will be a tall task, but BYD has posted strong growth globally despite a domestic Chinese market that is stuck in a brutal price war and decelerating. BYD has managed to ramp up its exports and get its foot in the door of key markets overseas, and expects its exports to nearly double in 2026 compared to the prior year.
Perhaps the most distinctive aspect of BYD for savvy investors is its extensive vertical integration. Legacy automakers have historically relied on large networks of third-party suppliers, but BYD took a different approach and produces almost all of its vehicle components in-house, giving it a cost advantage and ability to undercut the competition across the globe.
Further, manufacturing its own lithium iron phosphate (LFP) batteries as well as its own semiconductors, electric motors, drivetrains, and electronic control systems gives it protection from global supply chain disruptions, which the industry has seen recently in microchips and other speed bumps.
Both are long-term buys
While Ferrari and BYD operate at wildly different ends of the automotive spectrum, both have compelling advantages, whether it's pricing power and brand image or extensive vertical integration and mass-market volume growth potential. Due to Ferrari's Luce backlash and the ongoing price war in China hindering BYD's domestic sales, both are lagging the broader market gains over the past year. But that won't last forever, and savvy investors are taking notice.
Daniel Miller has positions in Ford Motor Company and General Motors. The Motley Fool has positions in and recommends Ferrari and Tesla. The Motley Fool recommends BYD Company and General Motors. The Motley Fool has a disclosure policy.