
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Burry Buy In Require Action From Zoetis Stock Investors?
- Zoetis, the large animal health specialist, has seen demand expectations stay muted and returns on capital remain unchanged, keeping operational momentum subdued.
- Despite that slower backdrop, Michael Burry has reportedly increased his position in Zoetis, arguing the business looks undervalued and overlooked without AI or COVID-linked excitement.
- We will now assess how Zoetis' investment narrative is affected when a high profile value investor leans into an out of favor sector.
Zoetis Investment Narrative Recap
To own Zoetis, you need to believe in steady animal health demand and the company’s ability to keep monetising its broad portfolio, from parasiticides to pain management, even while industry growth expectations stay modest. The near term story is about execution, not excitement. Flat demand forecasts and unchanged returns on capital keep the burden on management to defend share and pricing in core therapies.
The biggest short term swing factor remains how well Zoetis converts under-treated pet conditions and international markets into real prescription volume. Competitive pressure in dermatology and parasiticides, plus hesitancy around newer pain products, sits on the other side of the ledger as the key operational risk.
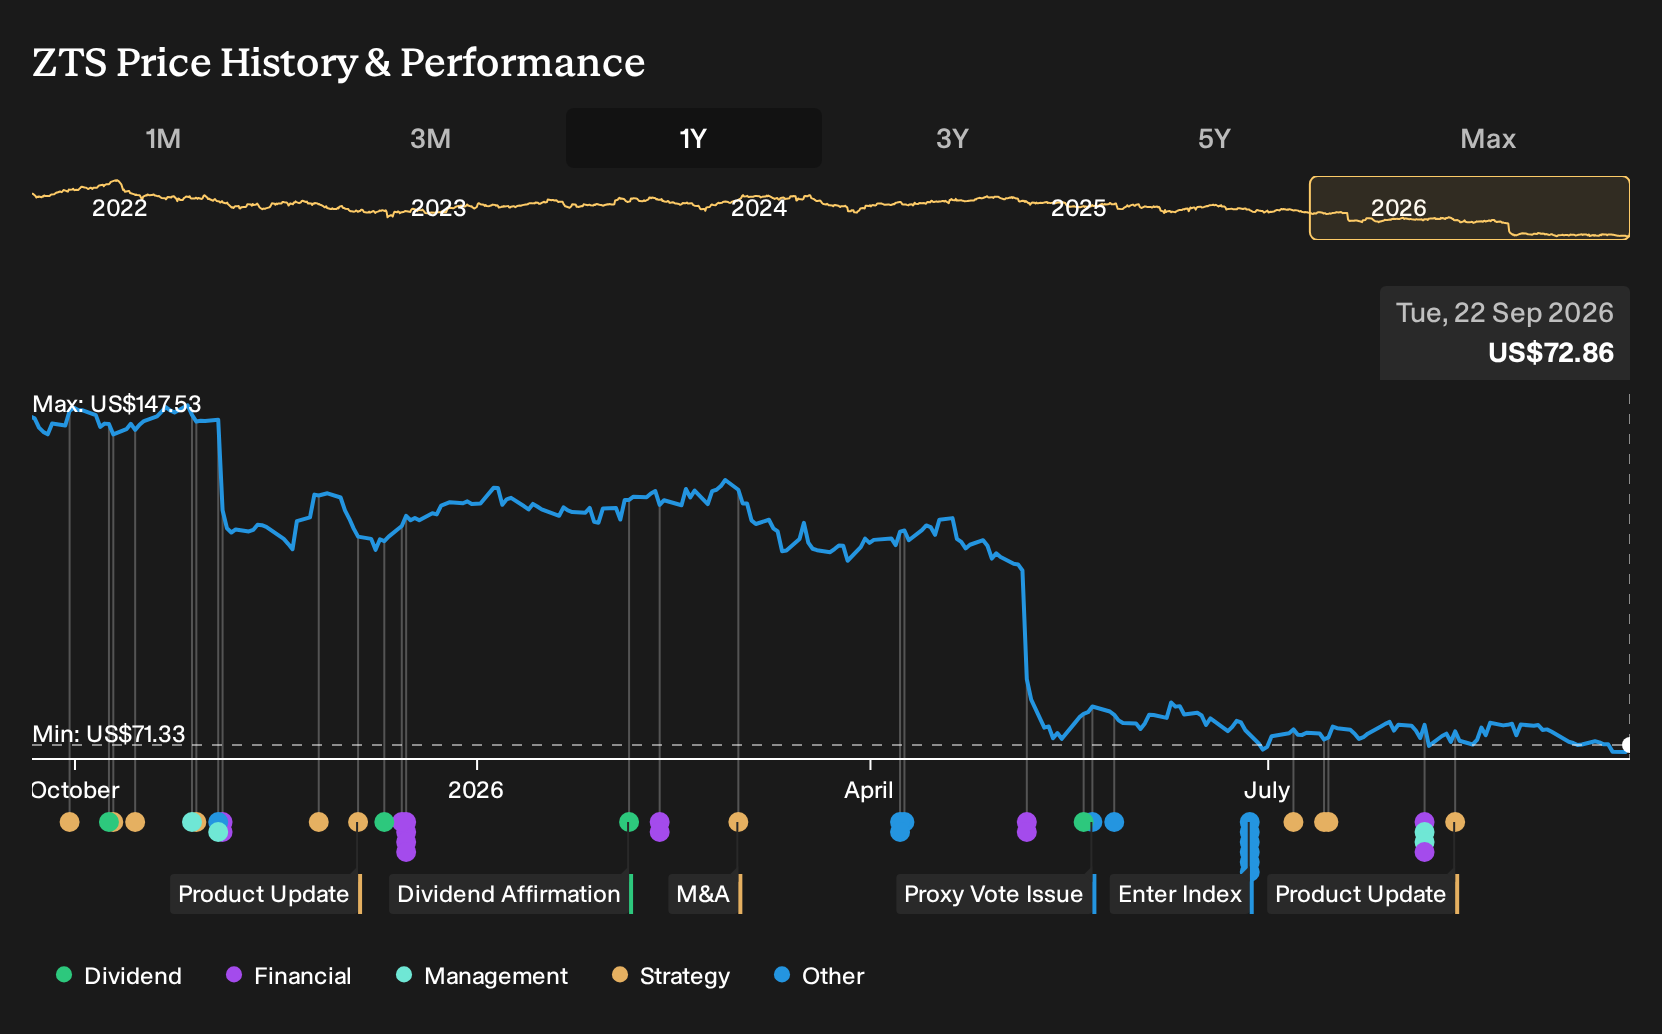
The most relevant development for this news cycle is not a fresh filing or product launch. It is the sharp reset in Zoetis’ share price over the past year, with the stock down about 48% on a 1 year total return basis and now trading at 11.4x earnings versus an estimated fair P/E of 21.7x.
That valuation reset is what investors such as Michael Burry appear to be reacting to. The business still reports net income of US$2.6b on revenue of US$9.5b, high quality earnings, a 2.91% dividend yield and analyst expectations for mid single digit earnings growth, even as debt levels and slower adoption in some franchises keep risk firmly in view.
Analysts project Zoetis to reach about US$10.0b in revenue and US$2.7b in earnings by 2029, which corresponds to a 1.5% yearly top line growth rate and an earnings increase of roughly US$0.1b from current earnings of US$2.6b.
Uncover how Zoetis' fair value indicates a 32% potential upside to its current price before sentiment narrows the discount.
Exploring Other Perspectives
One alternate angle focuses less on product competition and more on macro risk. The most cautious analysts were already worried that weaker pet spending could cap Zoetis’ earnings nearer US$2.4b, even as consensus pointed to about US$2.7b. With Michael Burry buying into weakness, you can now compare sharply different stories and decide which assumptions feel more realistic.
Explore 9 other Zoetis fair value estimates, including one that suggests it could be worth just $80.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zoetis research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zoetis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zoetis' overall financial health at a glance.
Looking For More Investment Ideas Beyond Zoetis?
If Zoetis has you thinking about where valuation, quality and sentiment collide, it can be useful to line it up against other opportunities using the Simply Wall St Screener.
- Focus on quality at a discount by scanning a curated set of companies trading below their estimated worth with the help of 29 high quality undervalued stocks.
- If balance sheet strength is your first filter, concentrate on businesses with robust finances by checking the list of solid balance sheet and fundamentals (23 results).
- For investors who prefer resilient profiles with fewer flagged risks, narrow your search using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com