
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Ipsen (ENXTPA:IPN) Undervalued After Its Board Refresh?
Board refresh puts Ipsen’s governance in focus
Ipsen (ENXTPA:IPN) has reshaped its boardroom, co-opting longtime healthcare executive Mariette Finet as Director after the resignation of Michèle Ollier earlier in the summer.
The move adds more than three decades of pharmaceutical and life sciences experience to Ipsen’s oversight structure, and gives investors fresh context for evaluating how the business is governed and how capital allocation decisions are reviewed.
Recent trading tells a mixed story for Ipsen. The 1 day share price return of 1.83% comes after the stock fell around 8% over the past month, yet the year to date share price return of 29.72% and 5 year total shareholder return of 96.96% point to momentum that has built over a longer horizon.
Scan how Ipsen compares with other potential opportunities in healthcare by reviewing a hand picked set of 132 healthcare AI stocks aligned with long term medical and drug development themes.
Ipsen’s refreshed board and mixed recent share performance raise a basic puzzle. Do the current numbers mainly reflect the underlying €4.3b specialty care business, or a swing in sentiment that valuation has not fully caught up with yet?
Most Popular Narrative: 10% Undervalued
Ipsen’s most followed valuation story points to a fair value of €167.07, compared with the recent €150.6 close. This frames the current board refresh against a market that already bakes in measured growth and risk.
Significant available cash and financial flexibility (€3B firepower, net cash balance) position the company to accelerate external innovation via targeted M&A or licensing, strengthening both pipeline depth and long-term earnings growth potential.
See why 7 investors see Ipsen as 10% undervalued.
Result: Fair Value of €167.07 (UNDERVALUED)
Still, Ipsen’s heavy reliance on a few key treatments and the competitive threat around Somatuline could quickly challenge the current undervaluation story.
Find out about the key risks to this Ipsen narrative.
Another View on Ipsen’s Valuation
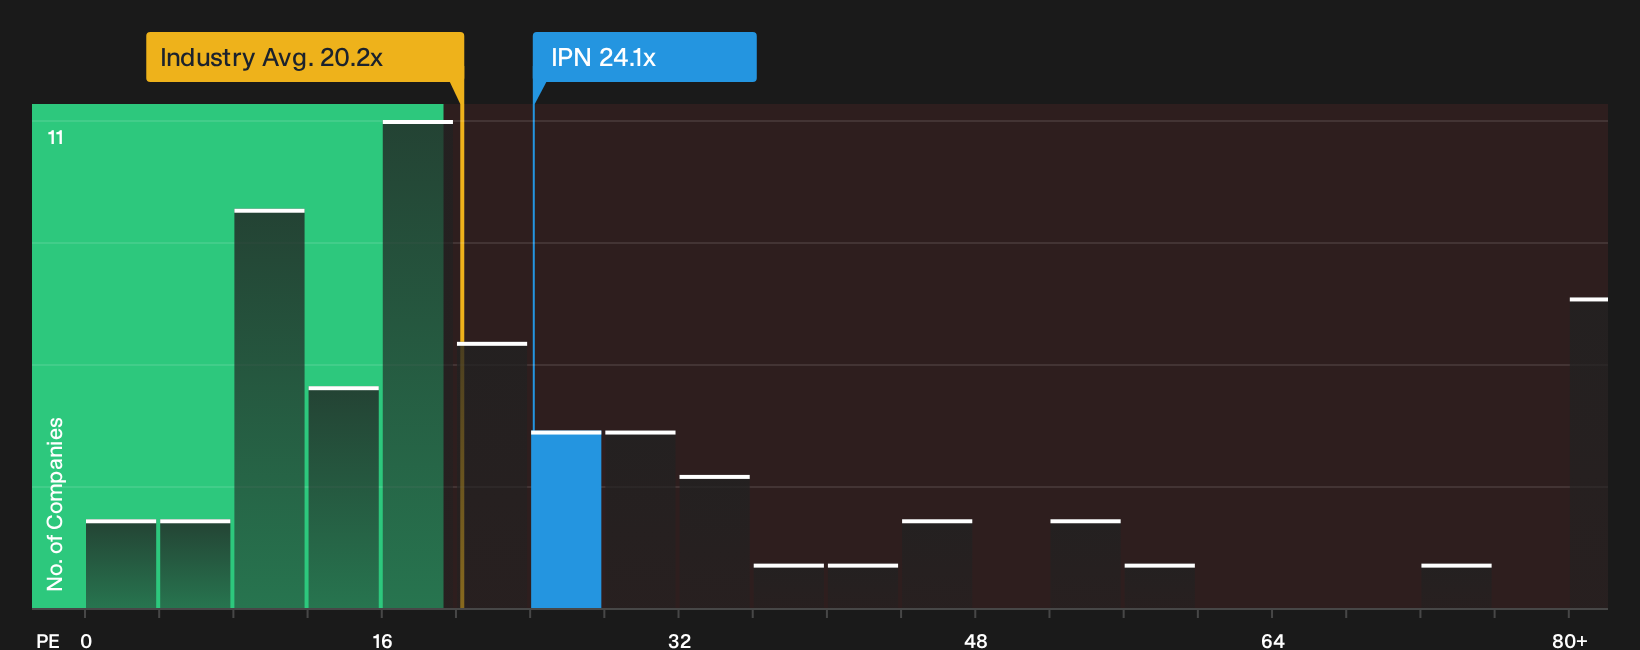
Headline story says Ipsen looks cheap against a €167.07 fair value, yet the P/E ratio of 24.1x tells a tougher story. That multiple sits above both European pharma at 20.4x and the peer average at 16.8x, while it is only slightly under a fair ratio of 25.1x. Is that a margin of safety or a narrow cushion if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sitting between optimism on growth and concern on concentration risk, Ipsen now offers a lot of data for you to weigh quickly. To see both sides of that debate in one place, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ipsen?
If Ipsen has sharpened your focus on quality and valuation, broaden your watchlist now so you do not miss opportunities sitting in plain sight.
- Target resilient income by scanning companies that show the balance of yield and stability through our 162 dividend fortresses.
- Hunt for mispriced quality by checking businesses that pair solid fundamentals with attractive valuations using the 173 high quality undervalued stocks.
- Zero in on durability by reviewing a list of solid balance sheet and fundamentals (198 results) that can help you avoid fragile balance sheets before the market turns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com