
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Wolfspeed (WOLF) Is Back In The Spotlight
Wolfspeed (WOLF) has filed a shelf registration for up to US$1.40b in common stock, covering 58,148,889 shares. The move puts potential future equity issuance squarely on investors’ radar.
Over the past week, Wolfspeed’s 7 day share price return of 16.53% and 30 day share price return of 8.66% contrast with a 90 day share price decline of 38.98%, so short term momentum has picked up after a much weaker few months.
Scan Wolfspeed alongside other power and chip infrastructure plays by checking our curated list of 86 AI infrastructure stocks while this fresh capital raise is in focus.
Wolfspeed’s sharp rebound sits against a much steeper recent slide, which raises a simple tension. Is this upswing pointing to improving business fundamentals, or has sentiment just swung ahead of what the numbers support?
Most Popular Narrative: 2% Overvalued
Wolfspeed’s most widely followed narrative pegs fair value at about $27.50, slightly below the last close at $27.99, so the stock is framed as only modestly ahead of that thesis while sentiment reacts to the shelf registration.
The analysts have a consensus price target of $27.5 for Wolfspeed based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $867.6 million, earnings will come to $172.3 million, and it would be trading on a PE ratio of 14.8x, assuming you use a discount rate of 12.5%.
See why 3 investors see Wolfspeed as 2% overvalued.
Result: Fair Value of $27.50 (OVERVALUED)
Still, Wolfspeed’s story can break if high fixed costs keep margins deeply negative or if heavy spending on new silicon carbide capacity fails to convert into material customer orders.
Find out about the key risks to this Wolfspeed narrative.
Another View: Wolfspeed Through The Sales Lens
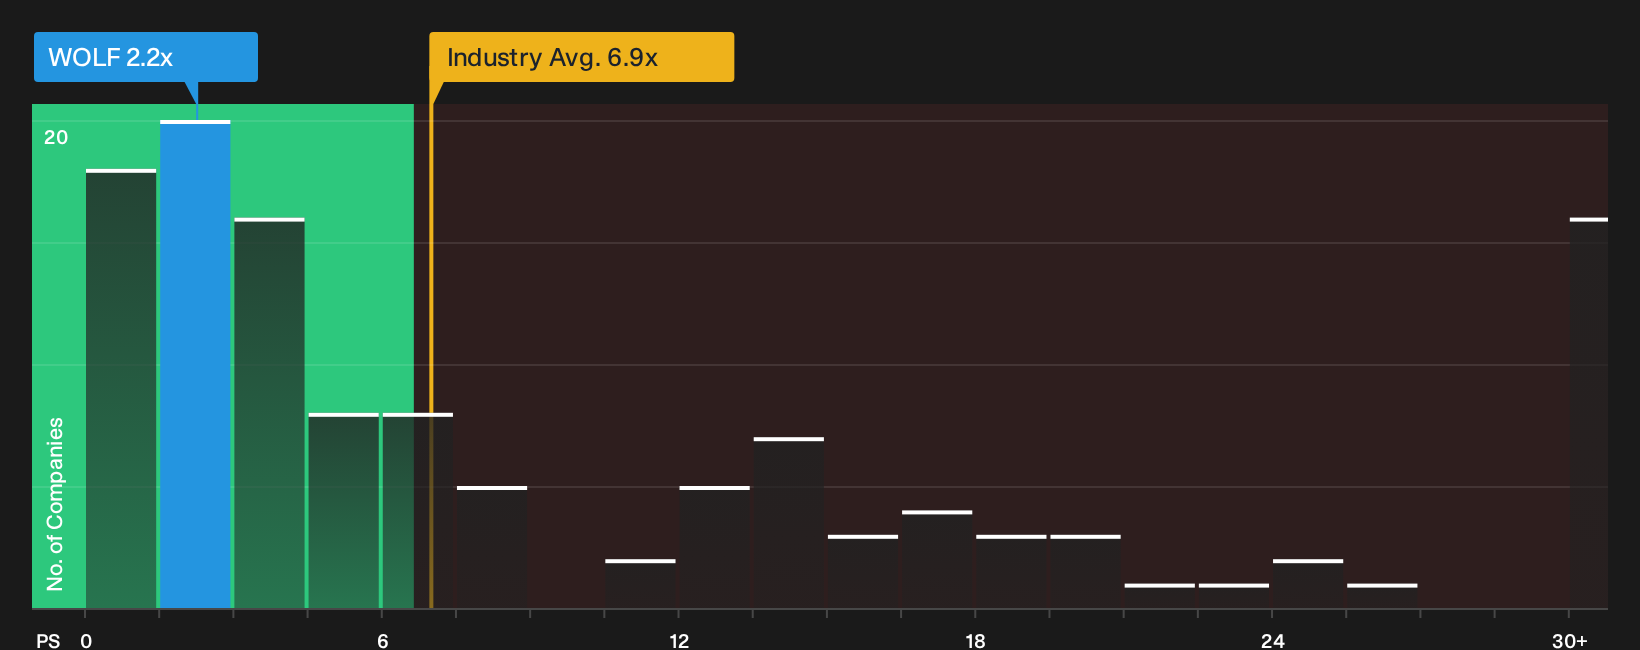
The fair value narrative pegs Wolfspeed close to $27.50, yet the market is already paying about 2.2x P/S compared with 6.9x for the broader US Semiconductor group and a fair ratio of 0.8x. That means peers trade rich, the fair ratio points lower, and the current tag sits in between. Is that a cushion or a warning sign for you as a shareholder?
To see how this price-to-sales gap could matter over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views are already forming around Wolfspeed, so consider acting promptly, review the data yourself, and weigh both the upside and the downside using 1 key reward and 4 important warning signs
Looking for more Wolfspeed sized investment ideas?
Do not stop with Wolfspeed alone. Broaden your watchlist now, or you risk missing out on other opportunities that could fit your style even better.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio when conditions get choppy.
- Hunt for mispriced quality by reviewing a 29 high quality undervalued stocks that combines stronger fundamentals with comparatively lower market expectations.
- Stack potential income and stability by filtering for 7 dividend fortresses that focus on higher yields backed by durable financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com