
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
US Stock IPO Outlook | Haofeng Group: Based on the “Big Pool Little Fish” pattern of financial education, high revenue growth, diversification of business results
Recently, Hao Feng Group Ltd. (Hao Feng Group Ltd.), a Hong Kong investment and education service provider, submitted an F-1 prospectus to the US Securities and Exchange Commission. It plans to issue 3.2 million common shares at 5 to 8 US dollars per share and land on NYSE American under the stock code “HFE”. Based on the median issue price, the market value after issuance is about US$151 million. Aide Securities is the sole bookkeeping manager. The company previously secretly submitted application documents on April 10, 2026.
Drive revenue growth with volume supplementation
According to the prospectus, Haofeng Group was founded on January 13, 2012 and is one of the few leading players in Hong Kong's highly diversified investment education market with the ability to generate large-scale income. According to Barentsz & CRI's industry report, the company ranked 3rd among investment education service providers for retail investors and high-net-worth clients in terms of 2024 revenue.
The company carries out substantial business through its wholly-owned operating subsidiary Hao Feng, and is positioned as an independent financial education teaching center. The curriculum system covers the five core modules of financial markets, stock trading, portfolio management, fundamental analysis and investment strategy, and uses a hybrid delivery model of “offline physical teaching+online realtime/recorded course+theme seminar”. The revenue source is strictly focused on the financial education sector. It consists of regular tuition fees (mainly annual subscriptions) and seminar fees, and the business boundaries are clear. After years of operation and accumulation, the number of annual subscribers achieved steady and compound growth, providing a basic stock market with strong predictability for revenue.
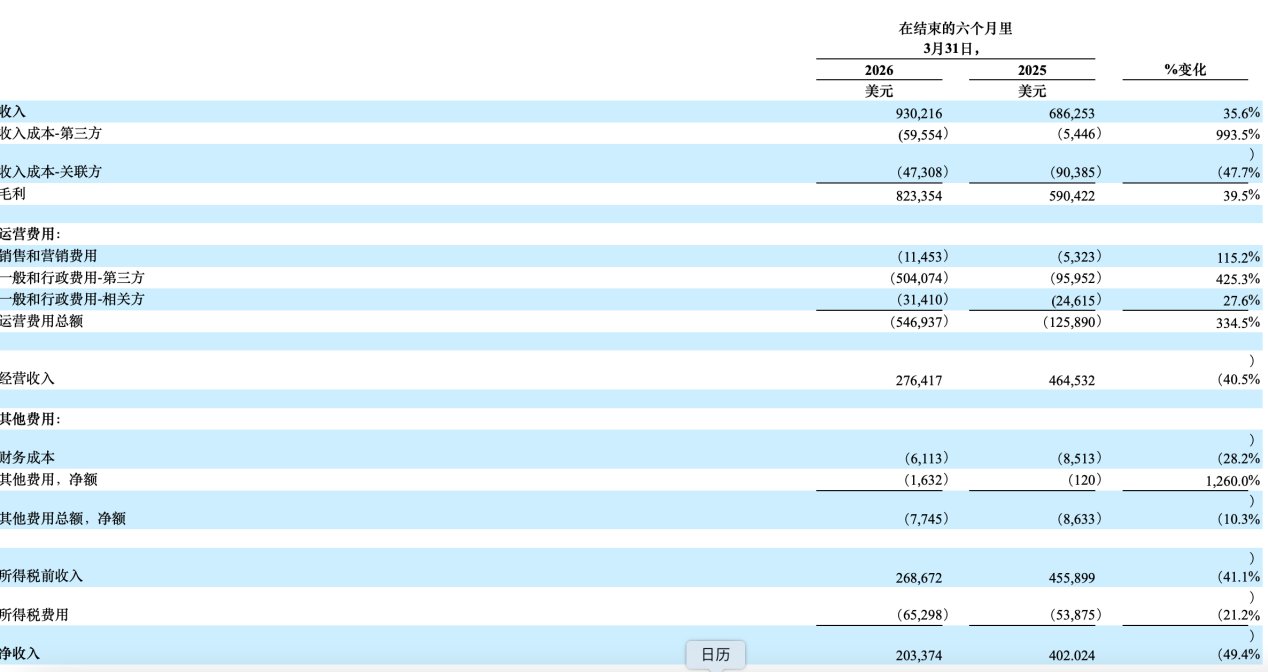
Financial reports show that in the 2025 and 2026 fiscal years, the company's revenue was 686,300 yuan (unit: US dollar, same below) and 930,200 yuan, respectively, an increase of more than 36% over the previous year. Notably, the gross profit side performed better than the revenue side. Gross profit reached US$823,400, up 39.5% year over year, and gross margin rose slightly to 88.5% from 86.0% in the same period last year. It shows that the pricing power and high margin attributes of core course products are prominent.
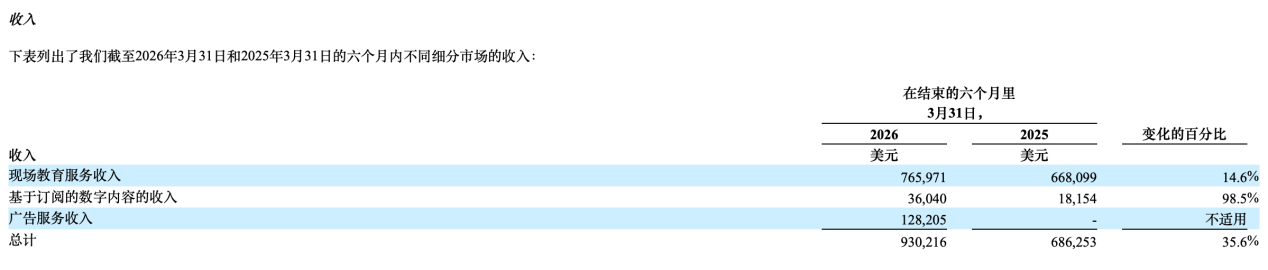
Looking at the split business structure, on-site education service revenue reached 766,600 yuan, an increase of 14.6% over the previous year, but the share of total revenue fell to 82.3% from 97.4% the previous year. Notably, the number of participants increased from 416 to 493 (+18.5%), which is faster than revenue growth (14.6%). According to this estimate, the average customer unit price (ARPU) for the current period was about 1,553 US dollars, a slight decrease of about 3.3% from 1606 US dollars in the same period last year. This indicates that during the listing sprint period, the company may have actively adjusted its pricing strategy or course product structure (such as launching entry-level courses), shifting from the past “price over quantity” to a “volume supplement” customer acquisition orientation in order to expand the user base market. In addition, advertising services generated 128,200 yuan in revenue, accounting for 13.8% of total revenue, and are an emerging business. Subscription-based digital content revenue increased 98.5% year over year to $36,000, accounting for 3.9% of total revenue. Although the growth rate has doubled, the absolute base is still too small, and a substantial second curve has not yet been formed.
The revenue side did not press the table for the time being, and the profit side's performance was indeed not as good as expected. During the period, profit fell from 402,000 yuan to 203,000 yuan, which is almost at a standstill. The culprit behind the sharp drop in net profit was completely exposed on the operating expenses side. Total operating expenses surged from 125,900 yuan to 546,900 yuan, an increase of 334.5%. Among them, general and administrative expenses - third parties soared from 9.6 million yuan to 5041 thousand yuan, an increase of 425.3% over the previous year. At the same time, although sales and marketing expenses doubled to 11,500 yuan, an increase of 115.2% over the previous year, the absolute size is still extremely small, indicating that the company is currently not adopting a strategy of burning money for scale, and growth is still highly dependent on the natural transformation of the founder's IP.
In short, Haofeng Group's business diversification trend in 2026 is obvious, and the transformation from a “single IP education service” to an “investor traffic platform” is being initially explored. Breaking the ice in the advertising business is the biggest highlight, effectively hedging the growth rate of the education business due to a slight drop in customer unit prices, and verifying the cross-border commercial value of its user assets. However, advertising revenue is naturally highly volatile, and we need to be wary of excessive commercialization diluting the expertise of education brands.
Hong Kong Financial Education Circuit “Big Pond Little Fish”
Haofeng Group is in Hong Kong's financial education segment, a “big pond little fish” segment.
On the one hand, there is room for growth on the demand side of the industry. The prospectus shows that demand for financial education will continue to grow, driven by the expansion of different population groups. The demand for professional wealth management and digital assets courses from high-net-worth individuals is increasing. At the same time, the younger generation and newcomers are increasingly paying attention to basic financial literacy and investment skills, which together have created new growth opportunities for the financial education market.
The financial education market in Hong Kong was around US$1,054 billion in 2024. The compound growth rate from 2022 to 2024 was only 3.9%, and growth is moderating. However, CRI predicts that the CAGR will rise back to 7.8% from 2025 to 2034, and the market size will reach US$2,233 billion in 2034.
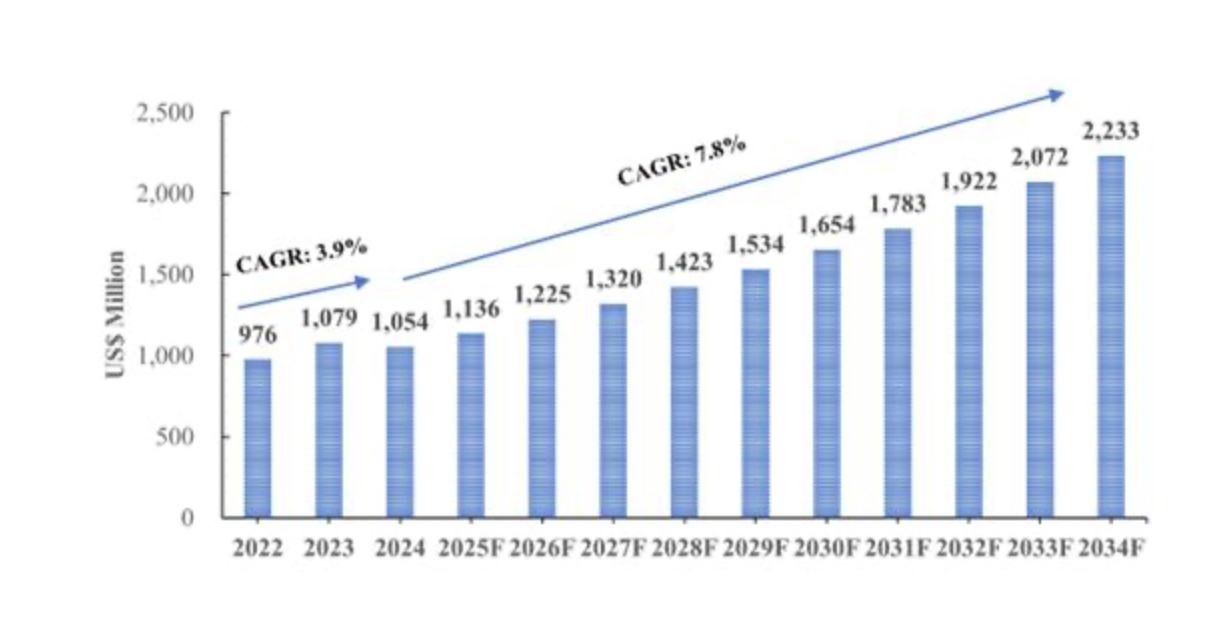
It is worth mentioning that Hong Kong's per capita wealth increased by 1.5% to US$60.1 million in 2024, ranking fourth among the world's major cities with a median wealth of US$222,000. At the same time, the complexity of financial products and fintech lowering the threshold for participation have created a perception gap of “easier participation and more difficult to understand”, and the demand for systematic financial education continues to unleash. Individual investor education accounts for 75.6% of the market, with a scale of about US$797 million in 2024, which is Haofeng Group's core target market.
On the other hand, the embarrassment of Haofeng Group in the competitive landscape is that it ranks high and is extremely small. Of the 54 active financial education institutions in Hong Kong, private financial education centers account for only about 18.5%, and the industry is extremely fragmented. Haofeng ranked third in revenue with less than 500 participants, indicating that there is still a distance between the “head” of the track and the real barriers to scale.
In summary, the core of Haofeng Group's future development is whether the company can move the teaching model from “individual teaching” to “replicable curriculum system+digital delivery capability” while maintaining the founder's IP premium, thereby truly participating in the 7.8% incremental allocation of the industry. Judging from current data, digital subscription revenue accounts for only 3.9% of total revenue. Ad monetization has just begun, and the transformation is still in the very early stages.