
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
A 1,252% Revenue Surge Isn’t the Most Important Number in This Nvidia-Backed AI IPO
The U.S. IPO market has come roaring back in 2026, with a wave of major companies tapping the public markets, including Space X (SPCX), Cerebras Systems (CBRS), and SK Hynix (SKHY). Investors pay close attention to any companies that chip giant Nvidia (NVDA) puts its eye on. And this time, the spotlight is on Nscale, an AI infrastructure or neocloud company.
Nscale has now filed for a U.S. IPO, targeting a valuation of roughly $30 billion, with major customers including Microsoft (MSFT) and Anthropic. But the headline 1,252% revenue jump may not be the important number investors should focus on before the company enters the public markets. There are more revealing figures buried in the filings.
The Number That Changes the Nscale Story
Nscale is a vertically integrated, full-stack AI hyperscaler. Its infrastructure business combines power generation, AI-focused data centers, and high-performance computing, while Nscale Cloud adds software and managed AI services on top.
The company hasn’t disclosed the date of its IPO yet, but when submitting its filing, it reported extraordinary revenue figures. The company generated $140.6 million of revenue in the first six months of 2026, compared to just $10.4 million in the same period last year. That is an eye-catching 1,252% year-over-year increase. This growth rate matters when the company is being discussed at a potential valuation in the tens of billions of dollars.
Furthermore, the company also reported that the cost of revenue reached $189.6 million in the first half of 2026, up from $7.8 million a year earlier. This implies that cost of revenue alone was higher than reported revenue during the period. The company attributed the increase to higher rental and power expenses as it expanded its sites. So the huge revenue growth is arriving alongside a business that is still spending heavily to bring new infrastructure online.
But that’s not the number that changes Nscale’s story.
Nscale says its power pipeline has grown from 750 megawatts to more than 10 gigawatts in roughly two and a half years, now that it operates across 14 regions. As of August 31, Nscale reported roughly $103.4 billion of active and contracted total contract value, or TCV, under long-term take-or-pay agreements, up from $38 billion at the end of 2025. This is not revenue already generated but the value of long-term customer commitments. Nscale says those contracts had a weighted average life of approximately 5.7 years.
There is another important distinction. Out of this $103.4 billion, the company classified just $2.6 billion as active, meaning the capacity that has already been deployed and is generating revenue. Therefore, whether Nscale successfully delivers the contracted infrastructure and generates the revenue is the important thing to watch after the IPO.
Two enormous agreements help explain the scale of the pipeline. Its agreement with Microsoft, signed between Sept. 2025 and April 2026, could generate up to $43.8 billion in payments through 2033. It also has another deal with Anthropic signed in August that could be worth up to $44.6 billion, depending on the company meeting the required delivery and service conditions. That explains how a company which generated $140.6 million in the first six months of 2026 suddenly has more than $100 billion in active and contracted TCV.
However, there is one issue investors cannot overlook. Nscale’s biggest customer accounted for 52% of revenue during the first six months of 2026. So while the $103.4 billion TCV figure looks enormous, current revenue remains dependent on a relatively small number of customers.
Why Nvidia’s Backing Matters
Nscale has already secured billions of dollars of financing for GPU infrastructure and data center projects, including facilities in Texas and North Carolina. Additionally, on Sept. 15, Nscale entered into a subscription agreement for at least $3.1 billion of financing. The arrangement includes $2.1 billion of unsecured convertible loan notes along with $1 billion of convertible notes or non-voting shares to be issued to Nvidia.
Nvidia’s backing matters because Nscale faces tough competition in this space from companies such as CoreWeave (CRWV) and Nebius Group (NBIS), which are also Nvidia-backed AI infrastructure companies. According to reports, Nvidia has invested $2 billion in CoreWeave in January and $2 billion in Nebius in March through a pre-funded warrant.
Both companies are currently seeing strong demand for AI compute, with Nebius raising prices on some Nvidia GPU capacity and CoreWeave continuing to secure higher-priced contracts as demand for AI infrastructure remains strong.
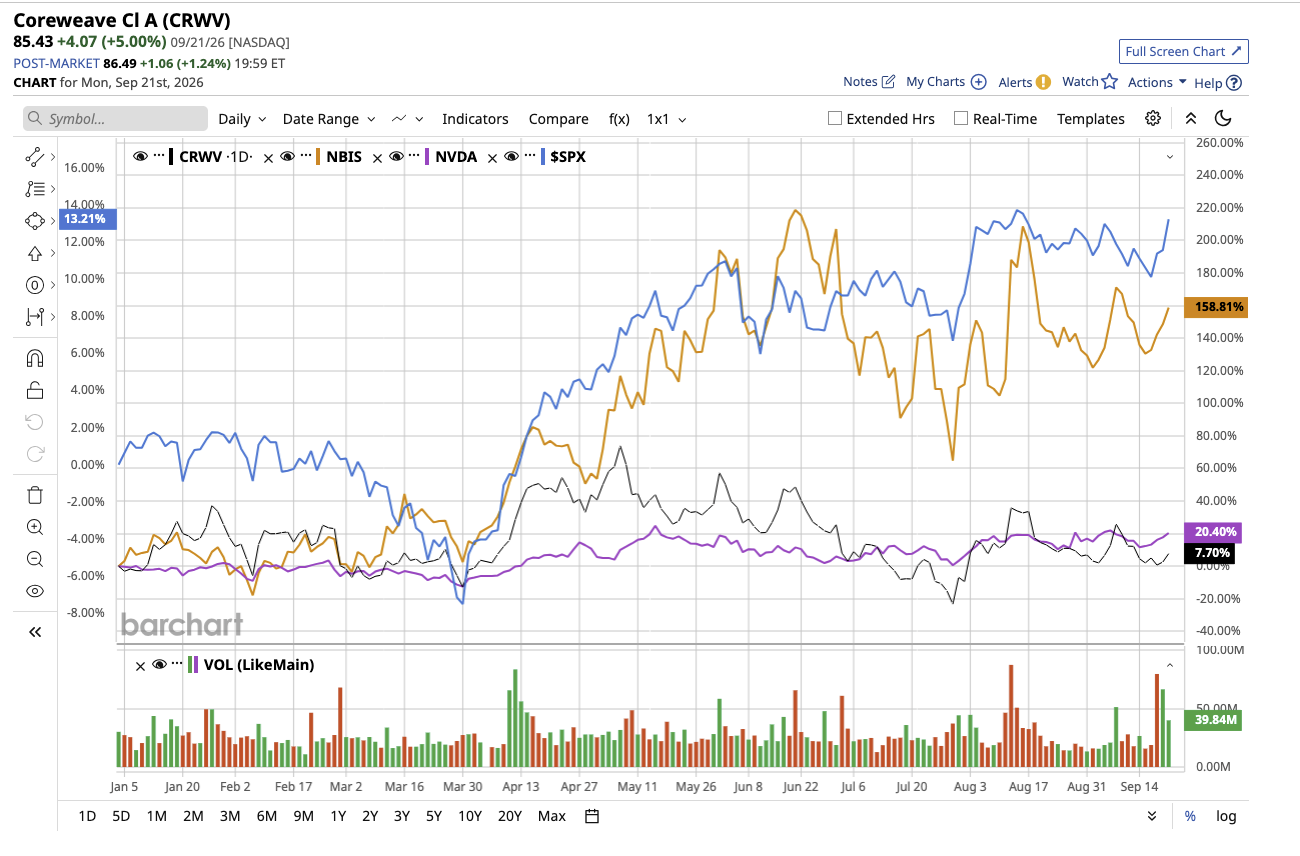
This is a capital-intensive business. Nscale has to acquire land and power, construct facilities, purchase or finance GPUs, install networking and cooling equipment, and then turn those assets into revenue-generating capacity. Therefore, Nvidia backing definitely matters.
The One Number That Cannot Be Ignored
There is another number that also helps explain why Nvidia backing matters. For the first six months of 2026, Nscale reported a net loss of $1.02 billion, compared to $368.9 million in the same period a year ago. So while revenue rose dramatically, Nscale’s bottom line reflects the strain of the enormous financial demands involved in turning Nscale's contracted pipeline into physical AI infrastructure.
Finally, the 1,252% revenue growth rate shows that Nscale is moving very quickly. However, ahead of the IPO, investors should keep an eye on how efficiently the company can convert its $103.4 billion of contracted commitments into active infrastructure, revenue, and, eventually, steady profits.
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.