
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BridgeBio Pharma (BBIO) Stock Looks Properly Priced For Its Sales Story
BridgeBio Pharma has delivered a powerful run over the past few years, which puts a sharp spotlight on what investors are paying for each dollar of its sales today. With the stock now at US$69.23 after some recent volatility, the question is how much of its future commercial potential is already reflected in that revenue-based valuation.
- Over the past 3 years the share price has climbed 160.5%, so the current tag on BridgeBio Pharma puts a lot of weight on how its sales story develops from here.
- The business model leans heavily on turning a pipeline of drug candidates into commercial therapies, which can shift future revenue, cash needs and the timing of any meaningful sales base.
- Your read on BridgeBio Pharma is one view; the desks covering it have another. See what analysts think BridgeBio Pharma's shares could be worth.
For investors, the debate is whether BridgeBio Pharma's current share price is appropriately supported by the level and trajectory of its sales.
If you want more context around whether BridgeBio Pharma's sales-based valuation feels rich or reasonable, compare it with companies in 29 high quality undervalued stocks
Does BridgeBio Pharma Look Fairly Valued on Sales?
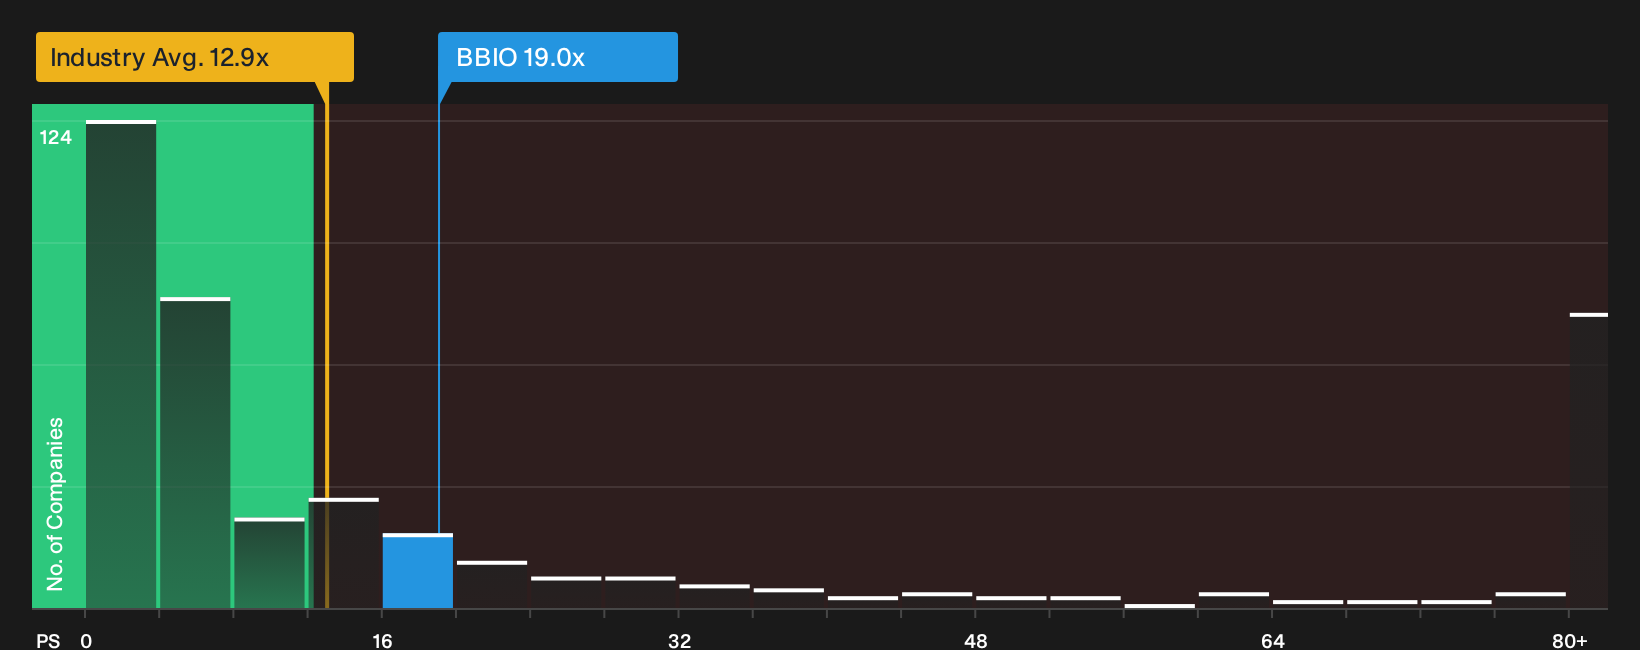
P/S suits BridgeBio Pharma because investors are being asked to value a pipeline and commercial ramp story more on revenue potential than current profits. At the latest price, the stock trades on a P/S of about 19.0x, which is higher than the broader biotechs industry at roughly 12.9x and also above a peer group average near 15.3x.
The fair value model used here suggests that, given BridgeBio Pharma’s growth expectations, risk profile and scale, a P/S closer to what it trades on today would be typical. That leaves the current multiple sitting near the level implied by that more tailored benchmark. As a result, the share price already builds in a lot of confidence about how future sales will materialise. Explore the numbers behind BridgeBio Pharma's P/S valuation.
The BridgeBio Pharma Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for BridgeBio Pharma leaves off by spelling out which combinations of future growth, profitability and earnings power would need to line up for the stock to be worth materially more or materially less than today. Each scenario pins a plain-english fair value on a specific mix of potential catalysts and risks, so you can track over time which story about BridgeBio Pharma's future is actually unfolding on the Community page.
Community views on BridgeBio Pharma are split between seeing a multi-asset growth story and a tougher competitive reality that could limit what the current valuation supports.
Bull case: 50% undervalued
"BridgeBio's ability to leverage advances in AI-driven and genomics-driven drug discovery, validated by its rapid pipeline progress and high late-stage success rate, is positioning the company to sustain a serial product launch model..."
Discover why this Narrative puts BridgeBio Pharma at 50% undervalued.
Bear case: 177% overvalued
"With Amvuttra’s recent blockbuster HELIOS-B Phase 3 data, the ATTR-CM landscape is aggressively shifting from TTR stabilizers to TTR silencers..."
Explore why this Narrative puts BridgeBio Pharma at 177% overvalued.
BridgeBio Pharma's valuation is only part of the story
Price tags on future medicines are one thing, but BridgeBio Pharma also carries specific risk checks that could reshape how you judge the opportunity or the downside. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com