
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Singapore Consumer Staples Stocks With Pricing Power As Inflation Pressures Households
Singapore’s inflation pulse just ticked higher again, with rising food, services, electricity and transport costs squeezing household budgets and lifting the bar for consumer staples and essential services stocks. That pressure can hurt weaker businesses yet reward companies that manage costs well and keep shoppers coming back. This article walks through three Singapore Consumer Staples & Essential Services Stocks that screen as potentially well placed in this new pricing reality.
The three stocks highlighted next are only a sample from this theme, and the full Singapore Consumer Staples & Essential Services screen flagged nine more listed companies with equally compelling stories that are not covered here.
To go deeper into this idea and analyze and compare potential high conviction opportunities, head straight to the Singapore Consumer Staples & Essential Services Stocks screener.
Sheng Siong Group (SGX:OV8)
Sheng Siong Group runs a pure-play supermarket chain focused on groceries and household essentials, squarely in the everyday-needs theme. It generates about S$1.7b in supermarket consumer goods revenue, almost entirely from Singapore, and carries a market value of roughly S$4.8b.
Sheng Siong Group offers direct exposure to Singapore’s staple spending, with supermarket earnings tied to everyday food and basic household items rather than discretionary splurges. The business combines high reported profitability and steady demand in a period of rising living costs, yet it raises the question of what happens when pricing power and cost pressures tug in opposite directions for longer than expected.
If you want to see how that pricing power tug-of-war could play out for Sheng Siong Group, scan the 2 key rewards and 1 important warning sign before inflation shifts the story again.

DFI Retail Group Holdings (SGX:D01)
DFI Retail Group gives this staples-focused screen a regional twist, combining supermarkets, convenience outlets and health and beauty chains that cater to everyday spending even as inflation keeps pressure on household budgets across Asia.
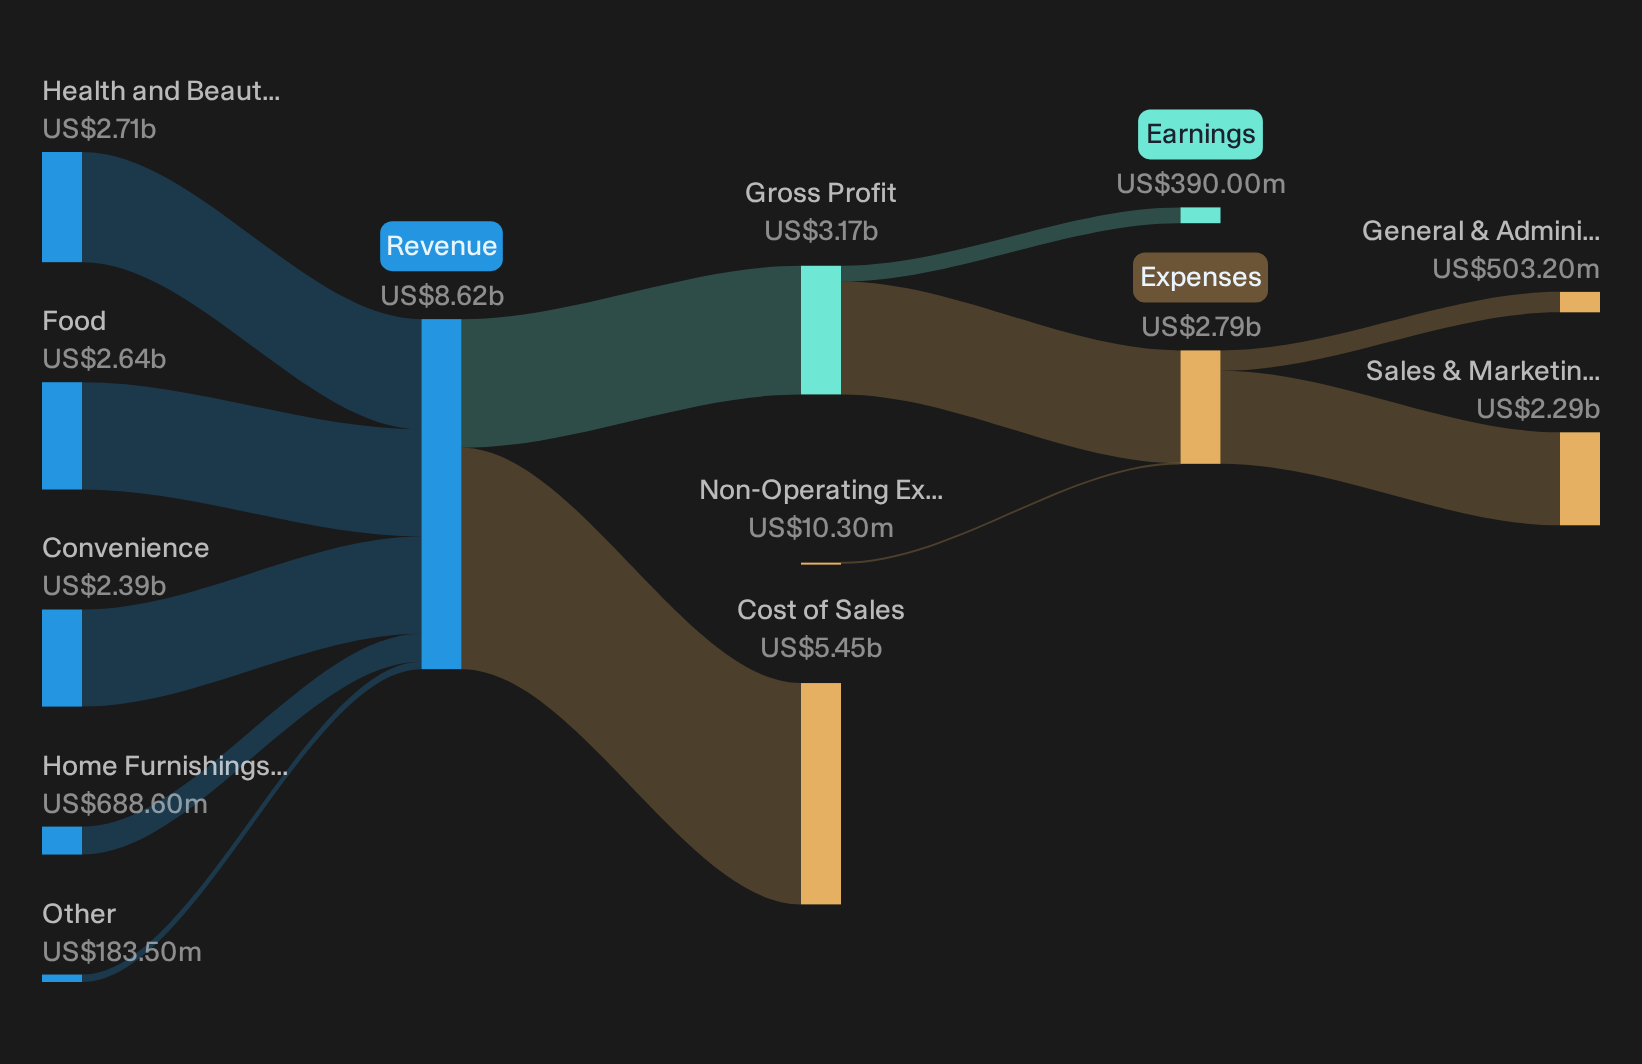
DFI Retail Group runs health and beauty, food and convenience chains across Asia, earning about US$2.7b from Health and Beauty, US$2.6b from Food, US$2.4b from Convenience and US$700 million from Home Furnishings, with a market value near US$4.4b.
"DFI has achieved profitability in its e-commerce segment, and management is pursuing an "accretive digital ecosystem" by integrating profitable e-commerce, retail media, and loyalty data/AI initiatives. This positions DFI to benefit from rising adoption of digital payments and omni-channel retailing in Asia, likely supporting both revenue growth and net margin improvement as scale and personalization increase."
The real swing factor is how one quiet shift in everyday shopping habits ultimately affects pricing power and profit resilience.
That quiet shift is already reshaping how DFI Retail Group earns every checkout. Read the full narrative for DFI Retail Group Holdings to see whether digital gains are masking deeper risks or accelerating an advantage.
Wilmar International (SGX:F34)
Wilmar International anchors the staples side of this screen as an integrated agribusiness that turns palm oil, grains and sugar into everyday food products. Food Products bring in about US$35.9b, Feed and Industrial Products around US$43.3b, Plantation and Sugar Milling roughly US$3.6b, and the group carries a market cap near S$22.8b.
For a theme built around essential spending, Wilmar International offers sheer scale in edible oils, flour, rice and packaged food that households and food manufacturers keep needing, even as Singapore’s core inflation sits at 2.2%. The business couples this with an integrated upstream and midstream model that gives it some ability to influence pricing and protect profitability, depending on how one unseen pressure plays out for food supply costs and margins.
Those supply cost cross-currents are already in motion, so scan the 3 key rewards and 3 important warning signs (1 is major!) to see where Wilmar International’s pricing power could start to decouple from input pressures.

Seeking Fresh Alternatives Beyond Staples?
Fresh opportunities do not stay quiet for long. Breakout stories gain momentum, weak ideas get caught dropping, and under the radar for now eventually expires. Act now.
- Spot cash rich balance sheets and resilient earnings engines before they start flying by scanning the curated list of solid balance sheet and fundamentals (198 results).
- Ride structural trends in automation and efficiency upgrades while it still matters by tracking the companies powering the 95 robotics and automation stocks.
- Position ahead of potential demand spikes in clean energy infrastructure by screening the curated 19 nuclear energy infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com