
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Zions Bancorporation National Association (ZION) Could Be 20% Undervalued On Leadership Change
Zions Bancorporation National Association (ZION) reported an internal leadership shift, with long-time executive Brian Stringham becoming Senior Vice President and Corporate Controller. He will now serve as the bank’s principal accounting officer.
For context, Zions Bancorporation National Association’s recent leadership reshuffle comes as the share price has eased, with the stock down 6.8% over the past 90 days but still showing a year-to-date share price return of 7.4% and a strong 3-year total shareholder return above 100%. This points to longer term momentum even as near term sentiment cools.
Scan beyond Zions Bancorporation National Association and see how other resilient financials are setting up today with the curated 30 resilient stocks with low risk scores.
The recent pullback at Zions Bancorporation National Association could hint at cooler sentiment rather than a sharp change in the underlying bank. So how does that mood shift stack up against what investors are paying today?
Price-to-Earnings of 8.1x: Is it justified?
Zions Bancorporation National Association changes hands at a P/E of 8.1x, while the stock last closed at $63.65. Compared with peers and the wider US banks industry, that valuation level screens as inexpensive based on current earnings.
The P/E ratio compares what investors pay for each dollar of profit. For a regional lender like Zions Bancorporation National Association, it is a quick way to see how the market is weighing its earnings profile against other banks that share similar regulatory, credit, and interest rate exposures.
On the numbers provided, ZION is described as good value relative to peer and industry averages, which sit at 12.6x and 11.7x respectively. That is a sizeable discount. The ratio is also below an estimated fair P/E of 10.2x. This points to a level the valuation could plausibly converge toward if sentiment and fundamentals align.
Explore the SWS fair ratio for Zions Bancorporation National Association.
Result: Price-to-Earnings of 8.1x (UNDERVALUED)
Still, Zions Bancorporation National Association carries clear risks, including pressure on net income, which declined 7.7%, and the broader share price pullback over recent months.
Find out about the key risks to this Zions Bancorporation National Association narrative.
Another view on Zions Bancorporation National Association’s value
The P/E discount presents Zions Bancorporation National Association as inexpensive, and the SWS DCF model offers an additional perspective. On that framework, the shares trade at $63.65 against an estimated future cash flow value of $125.69, which appears significantly undervalued. It is up to you to decide which signal should carry more weight.
Look into how the SWS DCF model arrives at its fair value.
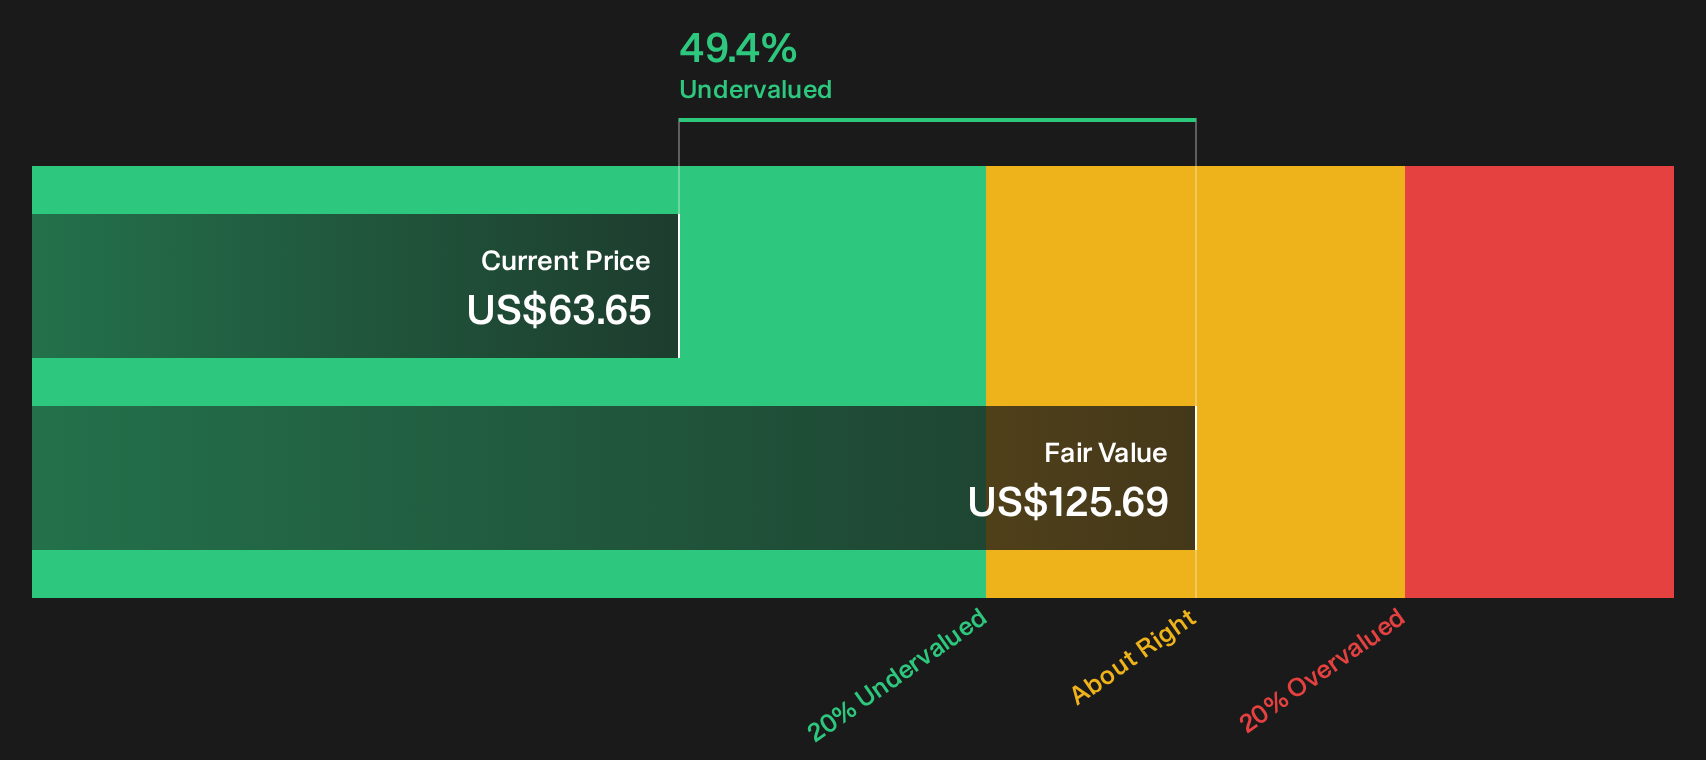
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Zions Bancorporation National Association for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment in this piece on Zions Bancorporation National Association is mixed, and the clock is always ticking in markets, so check the full risk and reward picture before deciding where you stand by reviewing the 4 key rewards and 2 important warning signs.
Looking for more Zions Bancorporation National Association style ideas?
If Zions Bancorporation National Association has sharpened your focus on value and risk, you may want to broaden your watchlist with a few targeted stock shortlists built from clear fundamentals.
- Target value-focused opportunities by scanning companies that trade below what their quality and fundamentals might justify through the 29 high quality undervalued stocks.
- Strengthen your downside protection by zeroing in on businesses with resilient finances using the curated list of solid balance sheet and fundamentals (23 results).
- Spot potential mispriced opportunities before the crowd by reviewing the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com