
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Did Silicon Motion Technology (SIMO) Climb Today?
Silicon Motion Technology (SIMO) is back in focus after fresh consensus estimates pointed to sharply higher expectations for earnings and revenue, just days before its presentation at the 5th Global Memory Innovation Forum.
The sharp 5.3% 1 day share price return and 18.4% 7 day gain suggest investors are quickly re-pricing Silicon Motion Technology ahead of its forum appearance, even though the 90 day share price return declined 11.9%. This follows a year to date share price surge of 202.1% and a three year total shareholder return above 5x that level, pointing to momentum that has accelerated over the longer stretch despite recent volatility.
Scan other fast-moving chip stocks showing similar estimate momentum using our hand-picked 86 AI infrastructure stocks for context alongside Silicon Motion Technology.
Silicon Motion Technology now looks like a powerful business story tied to NAND controllers and a suddenly hot earnings outlook. After a run like this, the real question is whether the current price still makes sense.
Most Popular Narrative: 23% Undervalued
On the latest numbers, the most followed narrative pegs Silicon Motion Technology’s fair value at about $369.70, well above the recent $283.26 close. That gap is built on a specific view of how AI led storage demand and controller design wins could reshape the earnings profile over time.
The rapid expansion of high-performance storage demand from AI, data centers, cloud computing, and edge computing is fueling adoption of advanced NAND controller solutions, particularly Silicon Motion's PCIe Gen 5 and enterprise-focused MonTitan controllers, supporting robust future revenue and margin growth as these markets scale.
See why 62 investors see Silicon Motion Technology as 23% undervalued.
Result: Fair Value of $369.70 (UNDERVALUED)
Still, the bullish Silicon Motion Technology narrative depends on the company avoiding heavy price competition and effectively managing rising R&D and operating costs that could squeeze profitability.
Find out about the key risks to this Silicon Motion Technology narrative.
Another Take On Silicon Motion Technology’s Valuation
The popular story presents Silicon Motion Technology as undervalued compared with a roughly $369.70 fair value. However, the SWS DCF model tells a very different story. On that cash flow view, the shares around $283.26 appear expensive relative to an estimated value of $158.55. This raises a simple question: which lens do you trust more, the growth narrative or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
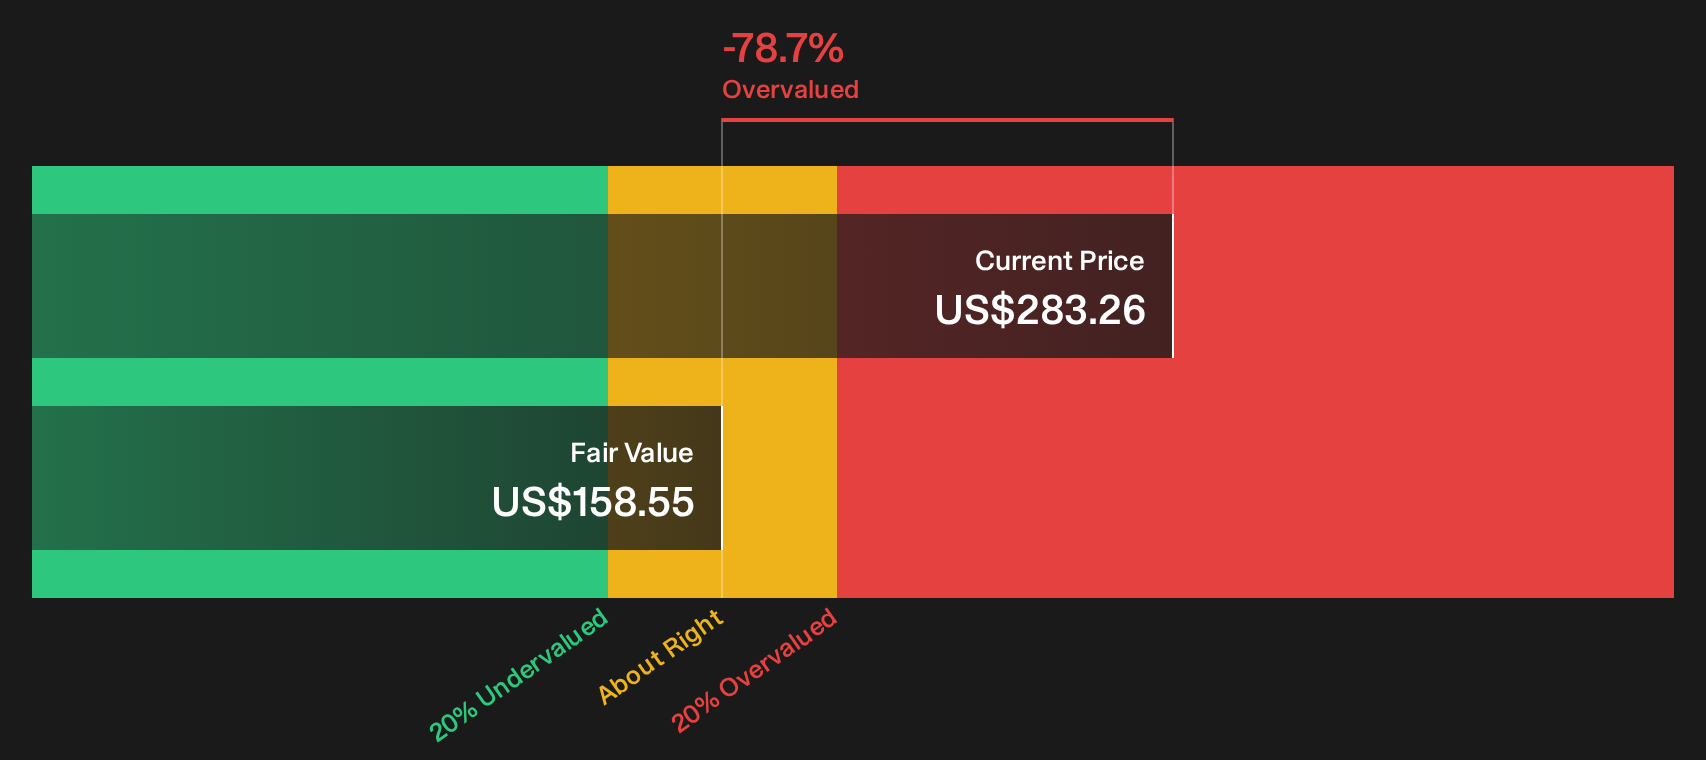
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Silicon Motion Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The mood around Silicon Motion Technology is clearly charged, so use that urgency to your advantage by reviewing both sides of the story today and weighing the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Silicon Motion Technology?
Do not stop your research with Silicon Motion Technology. Broaden your watchlist with a few focused stock sets that match different risk profiles and income goals.
- Target resilient income streams by reviewing 7 dividend fortresses that can help anchor your portfolio when growth stories take a breather.
- Prioritize capital preservation and sleep-better-at-night positions through 30 resilient stocks with low risk scores that keep overall portfolio risk in check.
- Hunt for under-the-radar opportunities with strong fundamentals using 16 high quality undiscovered gems before the wider market starts paying full attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com