
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bloom Energy (BE) Stock May Be Reasonable Despite Its Huge 3 Year Run
Bloom Energy has ridden a powerful story around fuel cells and power hungry AI data centers, and the share price surge now puts the focus squarely on whether the current market value lines up with the cash the business can produce over time. With the stock already pricing in a lot of optimism, the central question for investors is how that optimism compares with what its cash flows can realistically support.
- Over the past 3 years, Bloom Energy has delivered a very large share price gain. This raises the stakes on whether those returns are backed by a correspondingly strong cash flow profile.
- The company’s 800V DC native fuel cell for AI data centers and the potential shift toward operators funding more on site power infrastructure can support expectations for higher long term demand and may influence the timing and scale of future cash generation and capital spending.
- Prefer to judge Bloom Energy on sales? See why Bloom Energy's 26.2x P/S tells a different valuation story.
The issue now is whether Bloom Energy’s current share price is justified by the cash flows implied by its intrinsic value estimate from a Discounted Cash Flow (DCF) model.
If you want to test the same cash flow question across a broader set of AI infrastructure stocks, take a look at the 86 AI infrastructure stocks.
Is Bloom Energy a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here weighs what Bloom Energy can return to shareholders against what you pay today. Latest twelve month free cash flow sits at about $619 million in $ terms, and the model then builds in a growing stream of future cash that climbs from current levels to several billions over the coming decade.
Those rising cash assumptions mean the DCF output sits meaningfully above the current share price of $276.53, so the market is not reflecting the full cash flow path implied by this model. Because Bloom Energy’s 800V DC native fuel cell is aimed directly at power hungry AI data centers, the recent focus on cutting non compute costs by billions helps explain why the cash flow story appears stronger than the price. You can see how that gap is quantified in more detail in the full intrinsic value summary. Find out what Bloom Energy could be worth using our Discounted Cash Flow (DCF) estimate.
The Bloom Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Bloom Energy pick up where the cash flow puzzle leaves off and explain which paths for revenue, margins and earnings would need to occur for the stock to appear meaningfully under or over valued compared with today’s price. Each scenario treats any fair value as the result of specific assumptions rather than a single number. This allows you to compare those inputs with future results as they are reported on Bloom Energy’s Community page.
Community views on Bloom Energy are split between those who see a misunderstood cash engine and those who think expectations already stretch too far.
Bull case: 28% undervalued
"The markets they have barely penetrated are still there, ready for a better solution and although paradigm shifts are hard for bureaucrats..."
Discover why this Narrative puts Bloom Energy at 28% undervalued.
Bear case: 113% overvalued
"Bloom's business remains capital intensive, with continued need for large-scale manufacturing expansion funded through convertible debt or future equity..."
Explore why this Narrative puts Bloom Energy at 113% overvalued.
One more Bloom Energy signal worth checking
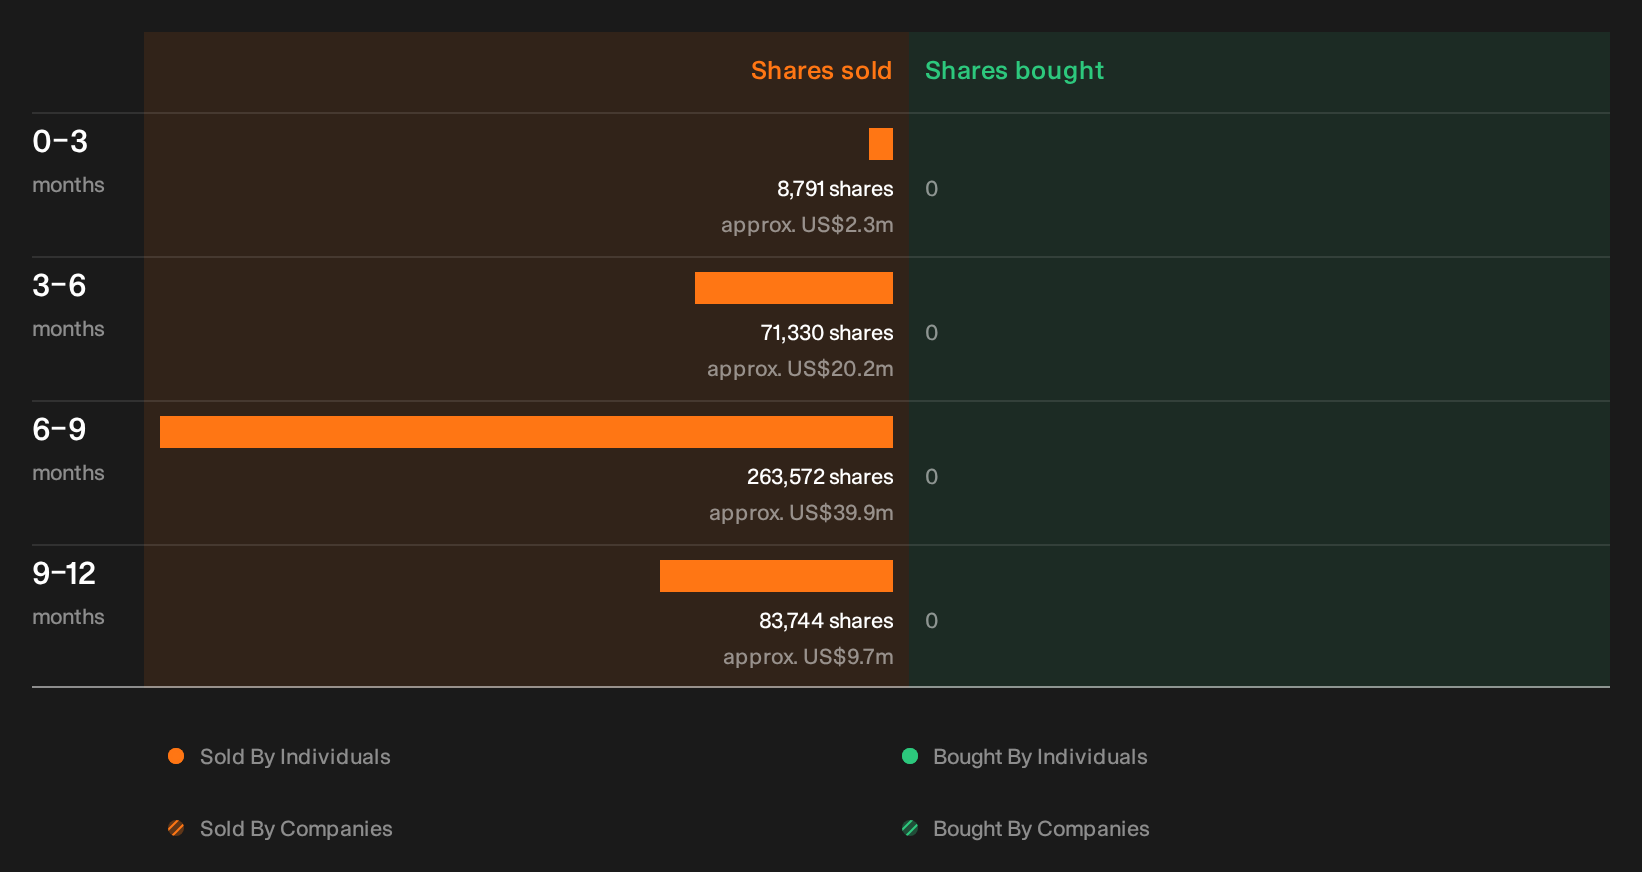
Before closing the file on Bloom Energy, it is worth knowing that recent share dealings by people inside the business have been flagged by our checks, and the specific traders, size and possible meaning are all still for you to review. See the recent insider selling flagged for Bloom Energy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com