
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Omnicom Group (OMC) Led Global Media New Billings In First Half 2026
- Omnicom Group (NYSE: OMC) reported that Omnicom Media secured the highest volume of new billings among global media groups in the first half of 2026.
- The performance was driven by high profile client wins across multiple regions, reflecting broad engagement with multinational advertisers.
- Management highlighted strong regional momentum within Omnicom Media agencies as a key factor in capturing large new account mandates.
- Omnicom Media leading global new billings only tells part of the story about how the wider group is evolving operationally. We have also flagged 5 warning signs (1 major) for Omnicom Group.
For readers tracking Omnicom Group and related media holdings, the next step is to explore income ideas through 7 dividend fortresses.
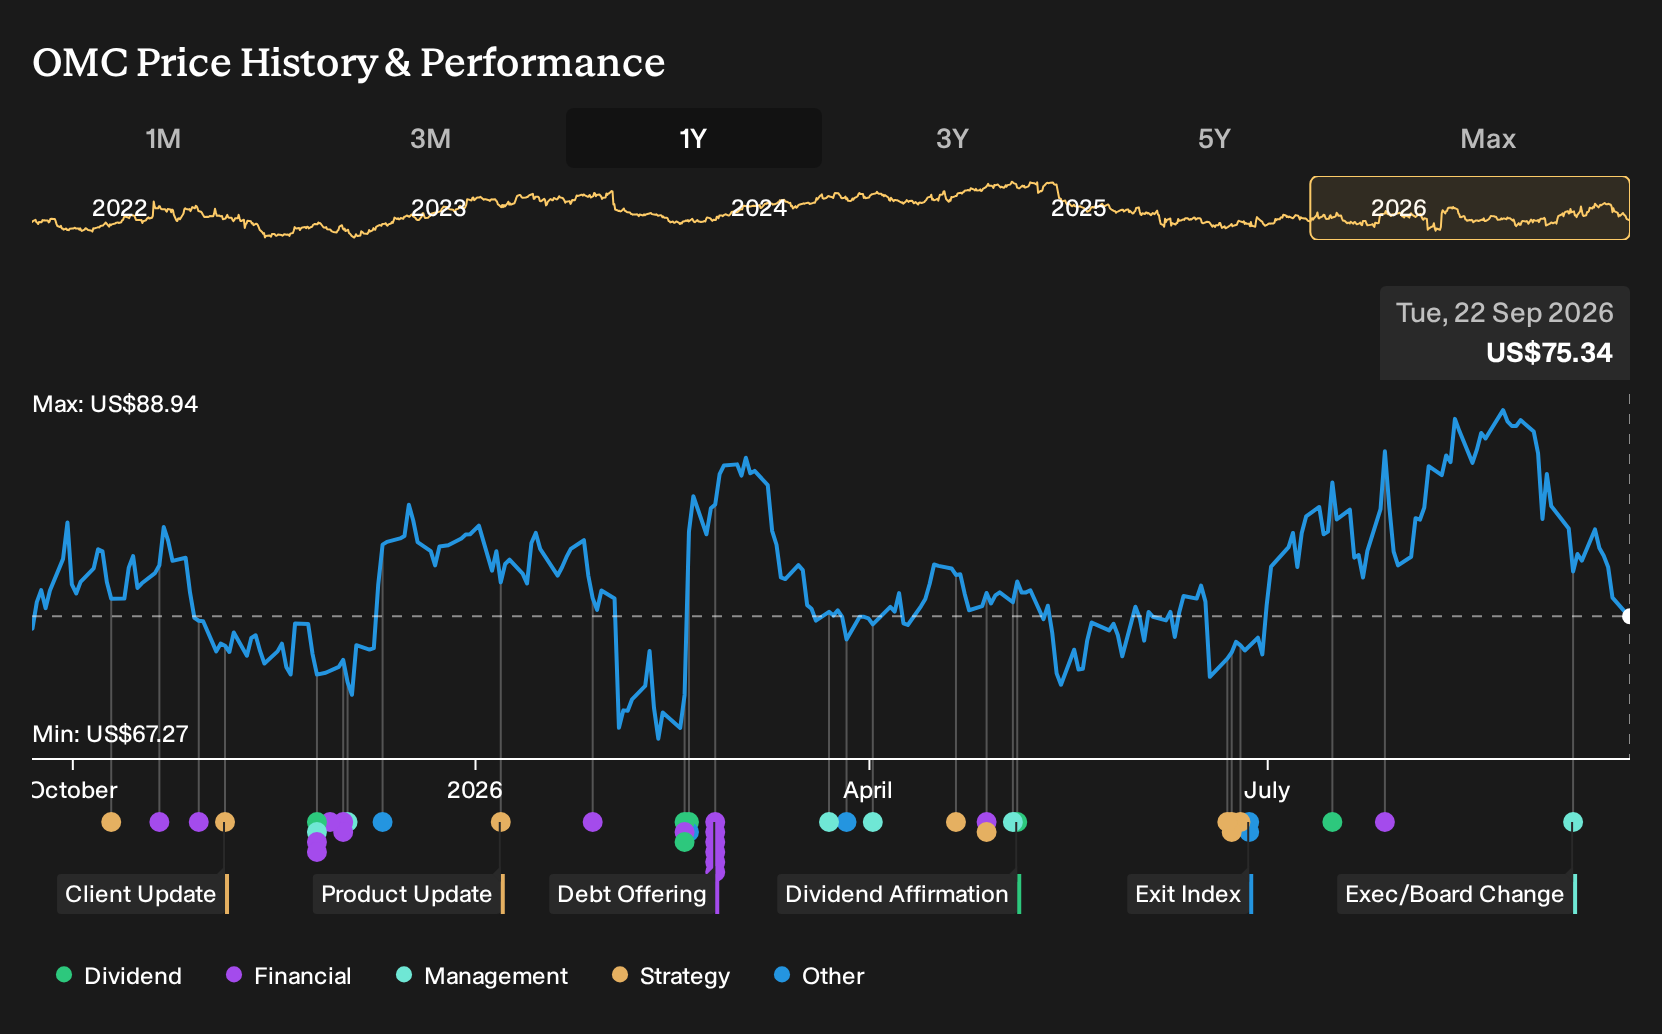
Omnicom Group is a US media conglomerate with a market value of about $20.7b. It helps large advertisers plan, buy, and measure campaigns across channels. Its Omnicom Media agencies sit inside a broader mix of advertising, marketing, and corporate communications services that compete with other global holding groups.
New media wins show whether Omnicom Group’s integration story is working
Omnicom Group’s Narrative rests on the idea that absorbing Interpublic and pushing deeper into data and AI can create a bigger, more efficient media operation that supports stronger margins over time. The new billings success gives you a live read on whether that media scale argument is taking hold with global advertisers.
"The integration of Interpublic assets with Omnicom Group’s existing media and marketing capabilities is creating what management now describes as the largest global media management network by market share…"
See how the full story points towards a $102 fair value for Omnicom Group.
This billings performance leans in the direction the Narrative describes. Winning Adidas, IBM and Royal Caribbean suggests the enlarged media network is competing effectively for global mandates against groups like Publicis and WPP, which is exactly what needs to happen for integration and AI-powered tools such as Omni to translate into higher quality revenue.
The open question is whether leadership turnover at Omnicom Advertising disrupts that momentum or locks it in. Troy Ruhanen’s retirement and Andrew Robertson’s appointment come just as management is trying to deliver portfolio pruning and cost savings, so execution risk around the wider restructuring and margin ambitions remains very real.
To make sense of news like this, you need a clear view of where Omnicom Group is trying to go, which is exactly what its Narrative is designed to spell out.
The one Omnicom Group detail hiding in the long range charts
Short term headlines rarely match where longer term projections say a business might end up. Omnicom Group is no exception, and the multi year outlook runs to a very different destination. See where analysts expect Omnicom Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com