
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Recursion Pharmaceuticals (RXRX) Shares Just Moved, So What Is Driving Attention Now?
Recursion Pharmaceuticals (RXRX) drew fresh attention after signing a TxFM RNA Foundation Model License Agreement with Tempus AI. The agreement includes a US$12,000,000 fee and shared oncology data access over a two year term.
Short term momentum has picked up around Recursion Pharmaceuticals, with a 7 day share price return of 25.00% and a 90 day share price return of 25.39% at a US$4.05 close. However, the 1 year and 5 year total shareholder returns are still down 15.80% and 82.33%, so recent enthusiasm follows a much tougher longer term journey.
Scan how Recursion Pharmaceuticals fits into a broader wave of data driven drug discovery by reviewing hand picked 37 healthcare AI stocks that could also be reacting to similar AI and oncology catalysts.
Recursion Pharmaceuticals has surged on the Tempus deal, yet the share price still sits well below many fair value estimates. Is the recent jump closing the gap, or is it leaving a wider mispricing on the table?
Most Popular Narrative: 106% Overvalued
Against a last close of $4.05 for Recursion Pharmaceuticals, the leading community narrative pins fair value at $1.97, which frames the recent Tempus-driven rally as excessive rather than closing a gap.
RXRX is a terrible biotech only because the INSIDERS themselves don’t believe in it! All they’re doing is milking the heck out of this doomed stock! Never seen a company where ALL they’re doing insiders are selling! Stock continues to go down every month! CEO said in 2014 that in 10 years there would be 100 new drugs! 12 years later they have ZERO 0️⃣!!! This stock went from over $40 to under $4! The hype is unbelievable! Worst biotech ever!!! Nuff said
See why 17 investors see Recursion Pharmaceuticals as 106% overvalued.
Result: Fair Value of $1.97 (OVERVALUED)
Still, if Recursion Pharmaceuticals secures stronger data from its pipeline or lands deeper partnerships, the bearish overvaluation call could face real pressure.
Find out about the key risks to this Recursion Pharmaceuticals narrative.
Another View on Recursion Pharmaceuticals' Valuation
The community narrative calls Recursion Pharmaceuticals overvalued at a fair value of $1.97. Our DCF model points in the opposite direction. It estimates future cash flow value at $9.57 per share, which frames the current $4.05 price as trading well below that figure. Which story do you think better reflects the risk you are willing to take?
Look into how the SWS DCF model arrives at its fair value.
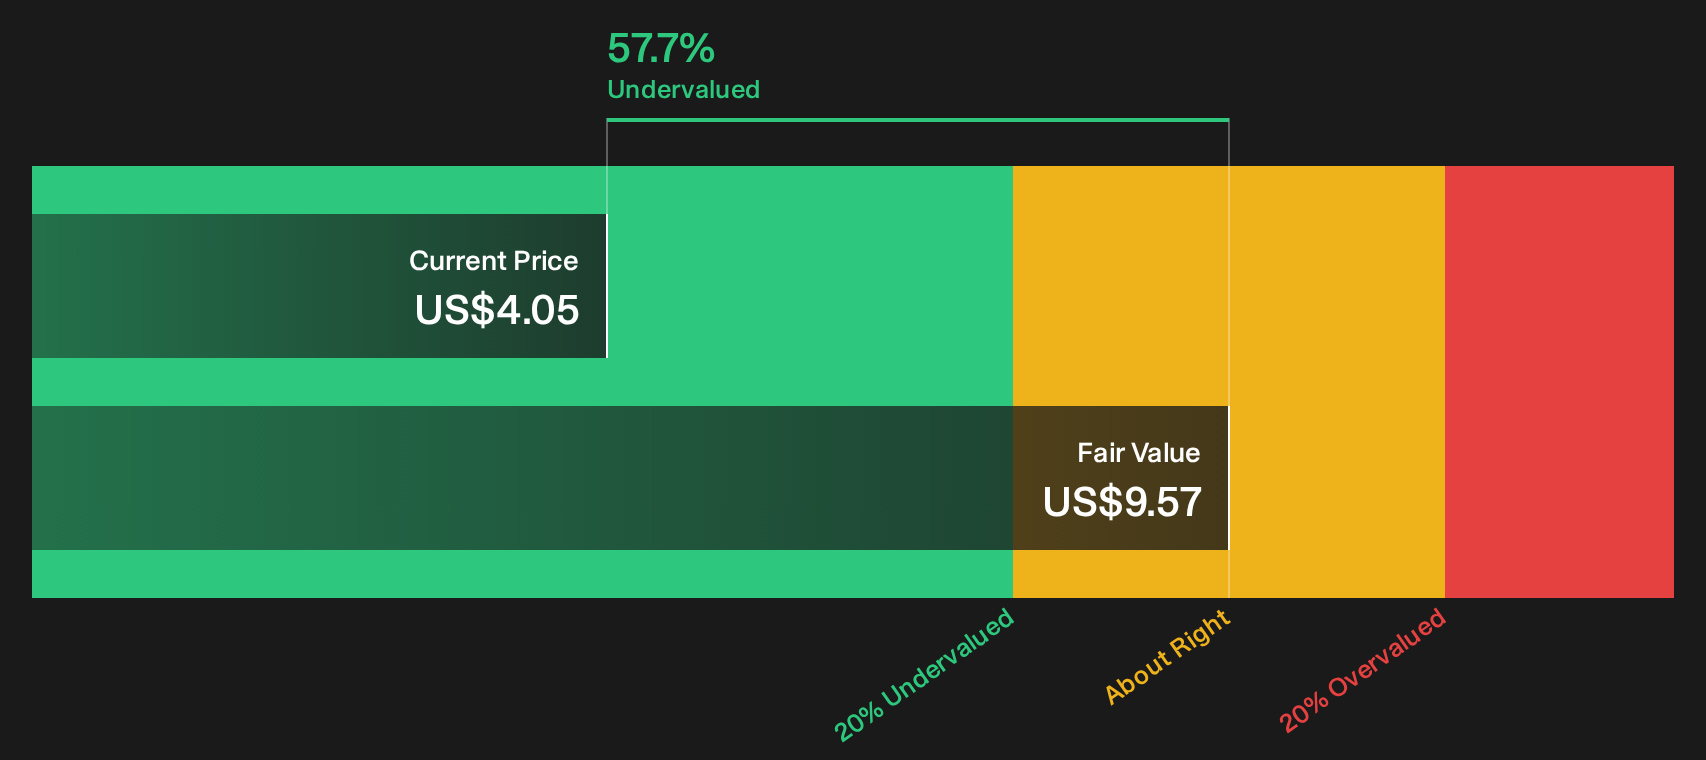
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Recursion Pharmaceuticals for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Opinion on Recursion Pharmaceuticals is clearly split, which is exactly why it pays to move quickly, review the numbers yourself, and weigh both the downside risks and upside potential highlighted in the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Recursion Pharmaceuticals?
If Recursion Pharmaceuticals has sharpened your focus on where risk and opportunity meet, you can keep that momentum going by scanning other potential setups before the next move passes you by.
- Target fresh upside by reviewing 16 high quality undiscovered gems that pair strong fundamentals with lower visibility on the market radar.
- Protect your downside first and then your upside by checking the 30 resilient stocks with low risk scores built around resilient businesses with steadier profiles.
- Focus on financial strength by filtering through the list of solid balance sheet and fundamentals (23 results) to identify companies with sturdier debt and liquidity positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com