
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Undervalued Stocks Trading Up To 47% Below Fair Value
The Federal Reserve has just lifted rates again and signaled higher borrowing costs well into the late 2020s, which puts pressure on highly leveraged and story driven stocks. Cash rich businesses suddenly look more attractive when money is no longer cheap. That is where companies generating solid cash and trading below their estimated worth come in. This article spotlights three such ideas from our cash flow value screen.
The ideas in this piece are just a handpicked sample from the value screen, with another 195 companies showing similarly cash rich profiles and discounted valuations that are not covered below.
To size up that wider opportunity set and focus on the potential highest conviction ideas for your watchlist, head straight into the Undervalued Stocks Based On Cash Flows screener.
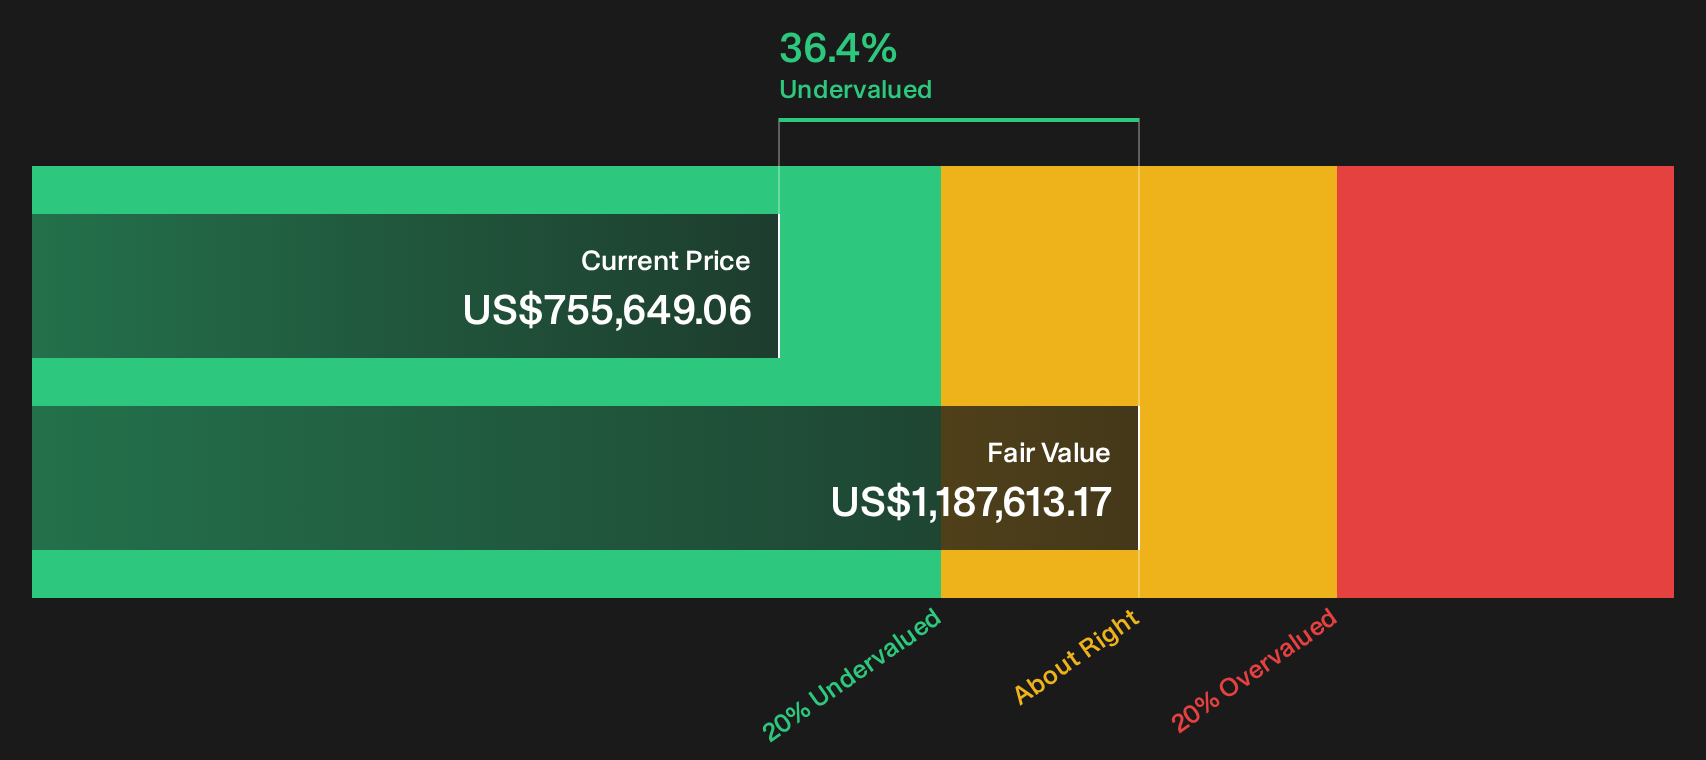
Berkshire Hathaway (BRK.A)
Overview: Berkshire Hathaway is a diversified holding company whose insurance, rail and energy subsidiaries generate large, recurring operating and investment cash flows.
Operations: Berkshire Hathaway earns most of its revenue from manufacturing at about US$83b, with sizeable contributions from insurance at roughly US$89b and freight rail at around US$25b.
Market Cap: US$1.07t
Berkshire Hathaway matters for a cash flow focused screen because its insurance operations build a reservoir of investable funds that supports disciplined, valuation driven capital deployment.
"The Cash Fortress: Berkshire's cash and short-term Treasuries hit a staggering, record-breaking $397.4 billion."
What happens if a single assumption around how that reservoir is redeployed shifts, even slightly, against current expectations?
If that shift is what you are weighing up, the full narrative for Berkshire Hathaway breaks down how Berkshire’s cash pile could accelerate or stall future capital deployment.
Autodesk (ADSK)
Overview: Autodesk sells subscription-based 3D design, engineering, and construction software that generates recurring cash flows from tools like AutoCAD, Revit, and Fusion.
Operations: Autodesk generates about US$7.79b from CAD / CAM software, with key markets across the U.S., EMEA, APAC, and other Americas.
Market Cap: US$45.74b
Autodesk matters for a cash flow focused screen because its subscription heavy software stack turns design, engineering, and construction workflows into repeatable, contract backed cash generation.
"If one engineer with AI eventually does the work that previously required three, does the firm still need three Autodesk seats? Maybe not."
What happens to Autodesk’s cash flow profile if a single quiet shift in how that extra productivity is monetised falls short of expectations?
That quiet shift is exactly where the real story starts, and the full narrative for Autodesk explains how Autodesk could use AI driven efficiency to increase cash generation.

Amazon.com (AMZN)
Overview: Amazon.com runs global online and physical retail stores, cloud computing through AWS, digital content, devices, subscriptions, and high-margin advertising services.
Operations: The business generates about US$453.7b from North America, US$173.6b from International, and US$148.4b from AWS.
Market Cap: US$2.79t
Amazon.com matters to a cash flow focused screen because AWS converts cloud infrastructure and AI demand into high margin, scalable cash generation that underpins the wider group’s valuation story.
"AWS reaccelerated through 2025 with roughly 20% year-over-year growth, exiting the year with an annualized revenue base exceeding $130 billion."
What happens to that cash generation profile if a single assumption about how quickly new AI capacity fills up proves too optimistic?
If that risk is what you are weighing, the full narrative for Amazon.com shows how Amazon.com could turn AI driven cloud demand into accelerating cash strength.

Seeking Fresh Alternatives Before They Fly?
Fresh ideas can move quickly, and value can be captured early when momentum builds. Scan these under the radar for now opportunities before the broader market reacts.
- Search for resilient cash generators that may hold up when sentiment softens by scanning the list of solid balance sheet and fundamentals (23 results) while it still appears overlooked.
- Explore early developments in automation and AI infrastructure by reviewing the curated 95 robotics and automation stocks before attention potentially broadens.
- Review cash rich digital businesses connected to blockchain rails by checking the hand picked 19 cryptocurrency and blockchain stocks while valuations may still reflect hesitation rather than strong conviction.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com