
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Agricultural Bank Of China (SEHK:1288) A Bargain Or Fully Priced?
Agricultural Bank of China has delivered a powerful run in recent years, and the share price now invites a closer look at what you are paying for its earnings. With the stock last closing at HK$6.50, the central issue is how well that market value lines up with what the bank currently earns.
- Over the past 5 years the stock has returned about 250.7%, which puts real weight on whether the present valuation can be supported by the profit stream behind it.
- The business leans heavily on steady interest income and fee-based activities, so any change in loan quality, funding costs or fee growth can shift how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on Agricultural Bank of China worth weighing. See what analysts think Agricultural Bank of China's shares could be worth.
For investors, the debate is whether Agricultural Bank of China's current share price is adequately grounded in the earnings it generates today.
If you want a broader earnings comparison alongside Agricultural Bank of China, it can help to line it up against 171 high quality undervalued stocks.
Is Agricultural Bank of China Still Cheap on Earnings?
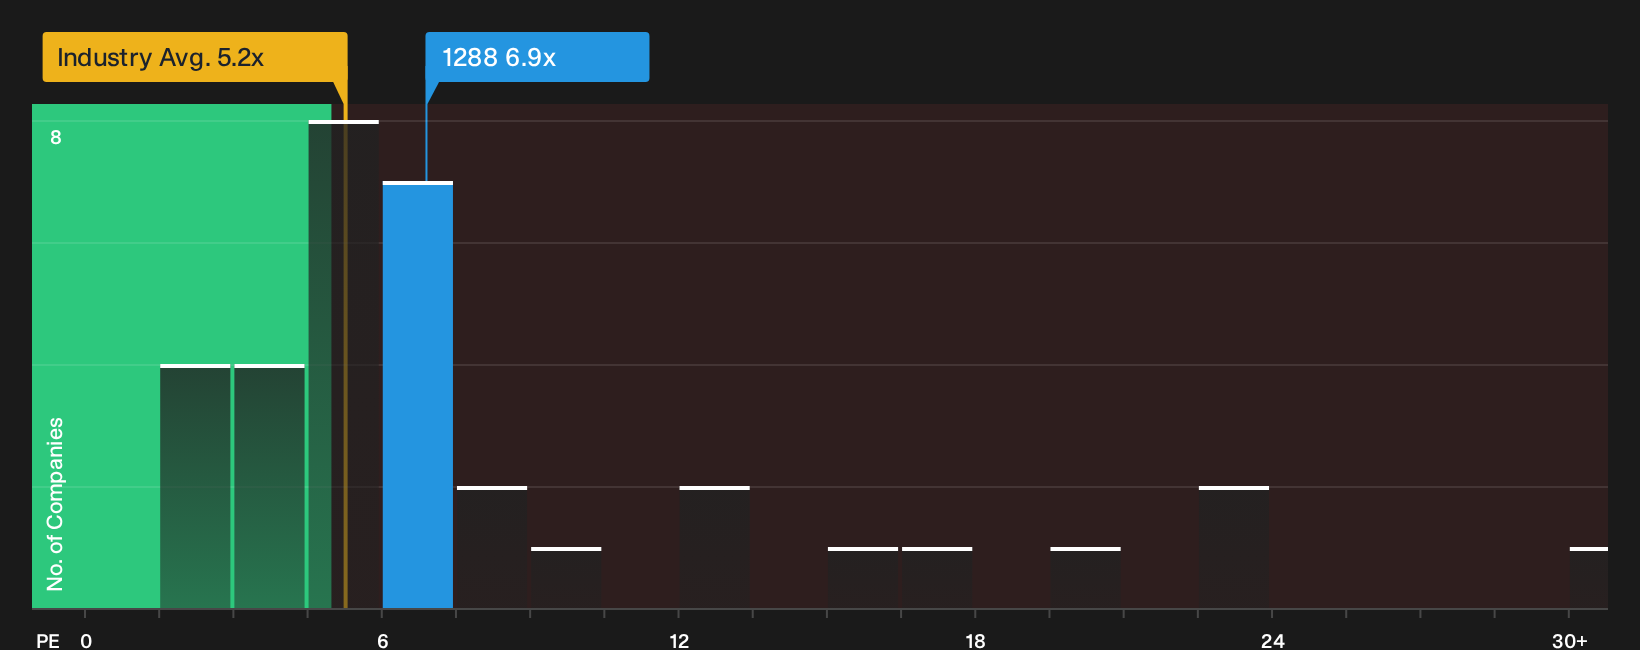
The P/E ratio is often a clean way to compare banks that convert balance sheet scale into earnings. Agricultural Bank of China trades on a P/E of 6.9x, which is slightly above its peer average of 6.7x and higher than the wider Banks industry on 5.2x. That gap indicates that investors pay more for each dollar of earnings here than for the typical listed lender.
The valuation model that blends the bank's growth outlook, profitability and risk profile points to a P/E that would sit above where the shares trade today. This suggests the current 6.9x is below the level implied by those fundamentals. For a holder, the key question is whether the bank's earnings quality and return on equity justify that discount or whether the peer and sector benchmarks are better guides to what the stock should cost. Explore the numbers behind Agricultural Bank of China's P/E valuation.
The Agricultural Bank of China Narrative: What Would Justify Today's Price?
Narratives for Agricultural Bank of China pick up where the P/E puzzle stops, by spelling out which paths for growth, profitability and earnings would need to play out for the current valuation to prove too high or too low. Instead of a single output from a ratio or pricing model, they map the future that number relies on so you can watch how Agricultural Bank of China's actual progress lines up with those assumptions. These sit on Simply Wall St's Community page and give you a forward-looking context for the bank's present earnings multiple.
The community is split between those who see more upside in Agricultural Bank of China at roughly current levels and those who focus on dilution and structural risks.
Bull case: roughly fairly valued
"Ongoing expansion in green finance, SME lending, and pension-related services, all prioritized by policy and demographic trends, positions ABC to grow new, higher-margin revenue streams…"
Discover why this Narrative puts Agricultural Bank of China at roughly fairly valued.
Bear case: 24% overvalued
"As demographic growth slows and rural depopulation accelerates in China, ABC's core customer base will shrink, eroding future demand for agricultural and rural loans…"
Explore why this Narrative puts Agricultural Bank of China at 24% overvalued.
Agricultural Bank of China’s price tag is only half the story
Who runs Agricultural Bank of China, how their incentives are structured, and whether those rewards line up with your interests can matter as much as any P/E chart. See who runs Agricultural Bank of China and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com