
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tamboran Resources (ASX:TBN) Shares Look Rich Despite Its Asset Backing
Tamboran Resources has delivered a 96.0% gain over the past three years, which naturally puts its current A$0.25 share price under the microscope. The key issue for investors is whether that move is aligned with what the company’s book value says the business is worth.
- The stock’s 96.0% return over three years means anyone looking at Tamboran Resources today is no longer judging a neglected small cap, but a company whose valuation now carries more weight in a portfolio.
- The balance sheet, including how much equity is tied up in exploration assets versus more established operations, can influence how much investors are willing to pay above or near the accounting value of Tamboran Resources.
- The analysts covering Tamboran Resources have run their own numbers. See what analysts think Tamboran Resources's shares could be worth.
For investors, the debate is whether Tamboran Resources' current share price is adequately supported by its book value when compared with the industry average.
If you want to test the same book value question across more than just Tamboran Resources, consider broadening your analysis with 5 high quality undervalued stocks
Has Tamboran Resources Run Too Far on Book Value?
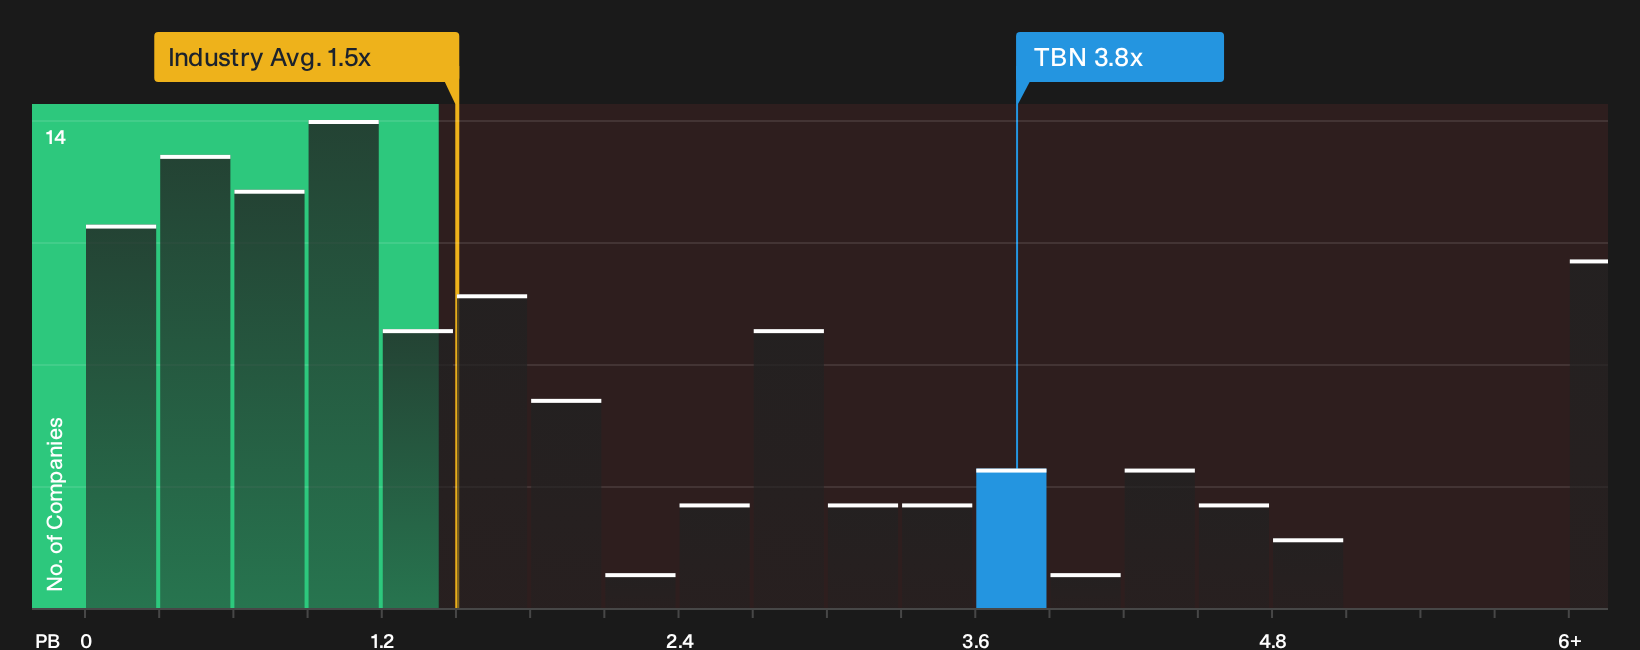
P/B suits Tamboran Resources because the business is still in an exploration heavy phase where book value carries more weight than earnings. The current P/B of 3.8x compares with an Oil and Gas industry average of about 1.5x, so the shares are trading at a sizeable premium to the sector’s accounting capital base.
Relative to a broader peer group on roughly 0.9x P/B, Tamboran Resources is priced well above the value of its net assets on the balance sheet. For you as an investor, that gap means the market is assigning considerable value to future projects and intangible potential rather than the existing equity today. It is therefore worth asking whether your own view of the company’s prospects supports paying that much above the industry book-value norm. Explore the numbers behind Tamboran Resources's P/B valuation.
The Tamboran Resources Narrative: What Would Justify Today's Price?
Narratives for Tamboran Resources pick up where the P/B puzzle leaves off by spelling out which paths for production, margins and earnings would need to unfold for the shares to be worth materially more or less than today’s price. Each scenario ties a fair value estimate to a specific mix of potential catalysts and risks so you can watch over time which interpretation of Tamboran Resources' future is matching reality.
One of the top community narratives on Tamboran Resources: 33% undervalued
"Progress towards first gas from the Beetaloo Basin Pilot Area in the third quarter of calendar 2026, supported by an 88% complete compression facility…"
Discover why this Narrative puts Tamboran Resources at 33% undervalued.
A final piece of Tamboran Resources worth checking
Tamboran Resources is not only about assets and ratios, because the people steering the project and the way their pay is structured can heavily shape future decisions. See who runs Tamboran Resources and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com