
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Micron (MU) Stock Trades At A Discount After A Very Large 3 Year Run
Micron Technology has turned into one of the market’s fiercest movers in recent years, and that kind of run naturally raises a basic question for you as an investor. Is the current share price still grounded in what the business is earning, or has enthusiasm run ahead of Micron’s earnings power.
- Over the past 3 years the stock has delivered a very large cumulative gain, which puts real pressure on its earnings to keep justifying a valuation at this level.
- Micron’s push into higher capacity DDR5 server memory and the broader tight supply backdrop can shape expectations for future profitability, which feeds straight into how much earnings investors are willing to pay for today.
- The analysts covering Micron Technology have run their own numbers. See what analysts think Micron Technology's shares could be worth.
The issue now is whether Micron’s recent share price level is reasonable once you line it up against what the company is earning today and what those earnings imply for its valuation.
If you want to test the same earnings question you are asking of Micron Technology across a wider group of AI infrastructure suppliers, scan through the 86 AI infrastructure stocks.
Is Micron Technology a Bargain on Earnings?
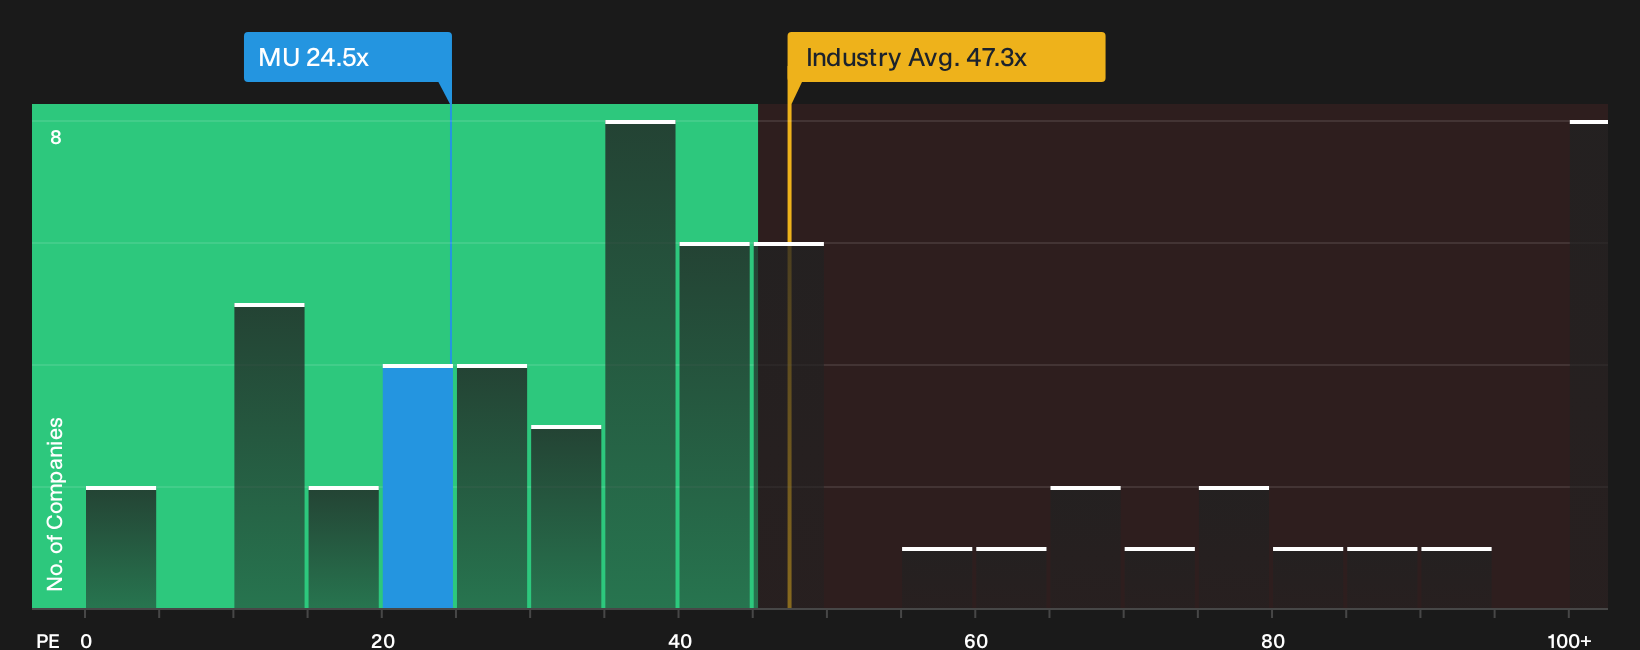
The P/E ratio suits Micron Technology because earnings are a core driver of how investors look at memory producers. Micron trades on a P/E of 24.5x, which is well below the semiconductor industry average of 47.3x and also below the broader peer group on roughly 79.7x. Based on the tailored fair multiple that blends Micron’s own growth profile, margins, scale and risk, the current valuation screens as undervalued on this earnings yardstick.
Despite optimism around Micron’s high capacity DDR5 server products and tight memory supply, the stock still carries a P/E that prices in less optimism than the sector and direct peers. For you as a shareholder, that gap suggests the market is not fully matching the earnings expectations implied by other semiconductor groups. The key question is whether Micron’s actual results and AI related demand will eventually line up with the earnings implied by that fair multiple. Explore the numbers behind Micron Technology's P/E valuation.
The Micron Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Micron Technology pick up where the P/E puzzle leaves off. They spell out which combinations of future growth, profitability and earnings power would need to play out for Micron Technology's current price to look materially higher or lower. Instead of a single multiple or model output, each narrative lays out its own fair value assumptions so you can compare those against the actual results as they arrive.
Micron Technology has sparked a split in the community, with one side treating the current price as too cautious and the other flagging how much optimism is already baked in.
Bull case: 12% undervalued
"The bull case is simple, AI has pulled memory from the commodity bucket into the strategic infrastructure bucket..."
Discover why this Narrative puts Micron Technology at 12% undervalued.
Bear case: 99% overvalued
"The real question is how long pricing power lasts, They are sold out for 2026, but i do not know about '27's status..."
Explore why this Narrative puts Micron Technology at 99% overvalued.
Micron Technology’s share price is only one piece of the puzzle
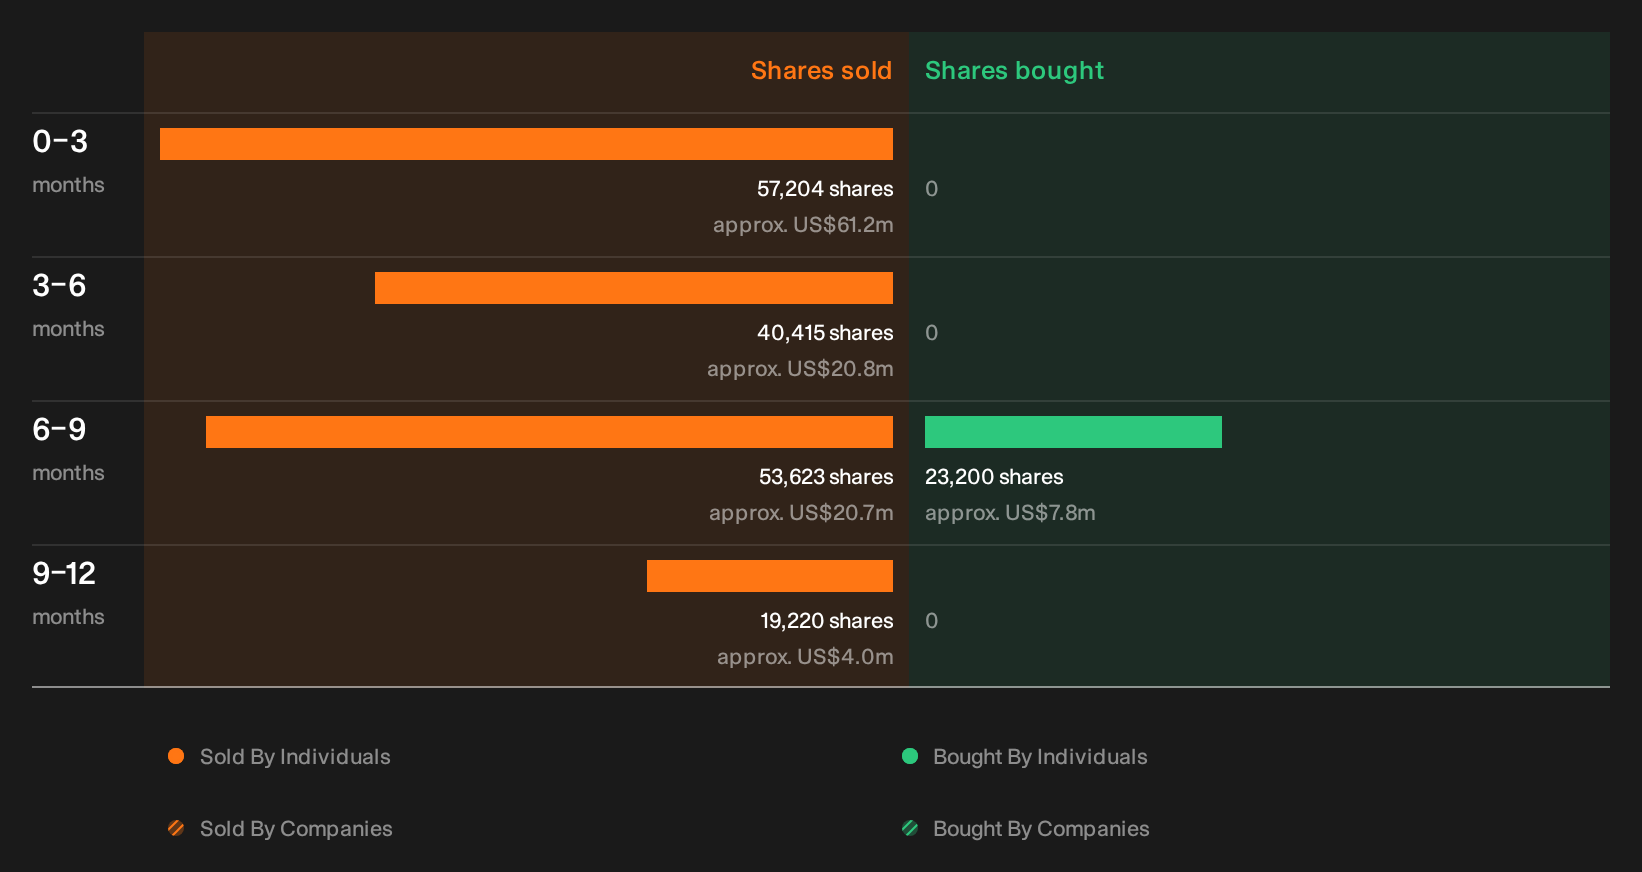
Micron Technology’s earnings story is only part of what matters, because recent trading disclosures also show insider transactions that you may want to inspect for who sold, how much, and what it might signal. See the recent insider selling flagged for Micron Technology.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com