
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Cyber Tyre Rollout Altering The Investment Case For Pirelli (BIT:PIRC)?
- Pirelli & C recently expanded its connected mobility and motorsport footprint, testing Cyber Tyre technology with Italy's Carabinieri and progressing tyre programmes for Formula 1, Moto2 and the 2027 MotoGP season.
- This mix of real-world Cyber Tyre deployment on police fleets and high-end racing tyre development highlights how Pirelli connects data-rich tyres, safety use cases and top-tier motorsport to support its premium positioning.
- Investors will be watching how Pirelli's Cyber Tyre rollout with the Carabinieri could influence the broader narrative around connected tyres.
Scan how Pirelli & C’s connected tyres and motorsport work feed into a broader theme of resilient, quality businesses by checking out the hand picked 170 high quality undervalued stocks in this space.
Pirelli & C Investment Narrative Recap
To own Pirelli & C, you need to be comfortable with a tyre specialist that leans heavily into premium, EV ready and connected products, while managing tariffs, currency swings and raw material costs. The big near term swing factor still sits in execution on premium volumes and pricing, rather than any single racing weekend or motorsport headline.
The latest Formula 1 compound choices and ongoing Moto2 and MotoGP test work look operationally routine and do not materially change that near term catalyst. Key risks stay anchored in trade policy, exposure to high value demand, and capacity constraints in places like Mexico if localisation needs to accelerate.
The Cyber Tyre trial with the Carabinieri is the announcement that lines up most clearly with Pirelli & C’s longer term smart tyre thesis. You are seeing sensors, AI and real fleet data used on public roads, which speaks directly to the idea of connected tyres becoming a commercial product rather than remaining a motorsport showcase.
From a catalyst point of view, the project gives Pirelli another real world reference case for high value, data rich tyres. It still carries execution risk around scale up, pricing and integration with automakers. The opportunity sits alongside the core premium EV compatible tyre push, not instead of it. This keeps tariffs, costs and premium demand as the bigger near term variables.
Pirelli & C's current analyst story points to revenues of €7.5b and earnings of €561.9m by 2029, based on an assumed 2.1% yearly revenue growth rate and an increase in earnings of about €39.5m from €522.4m today.
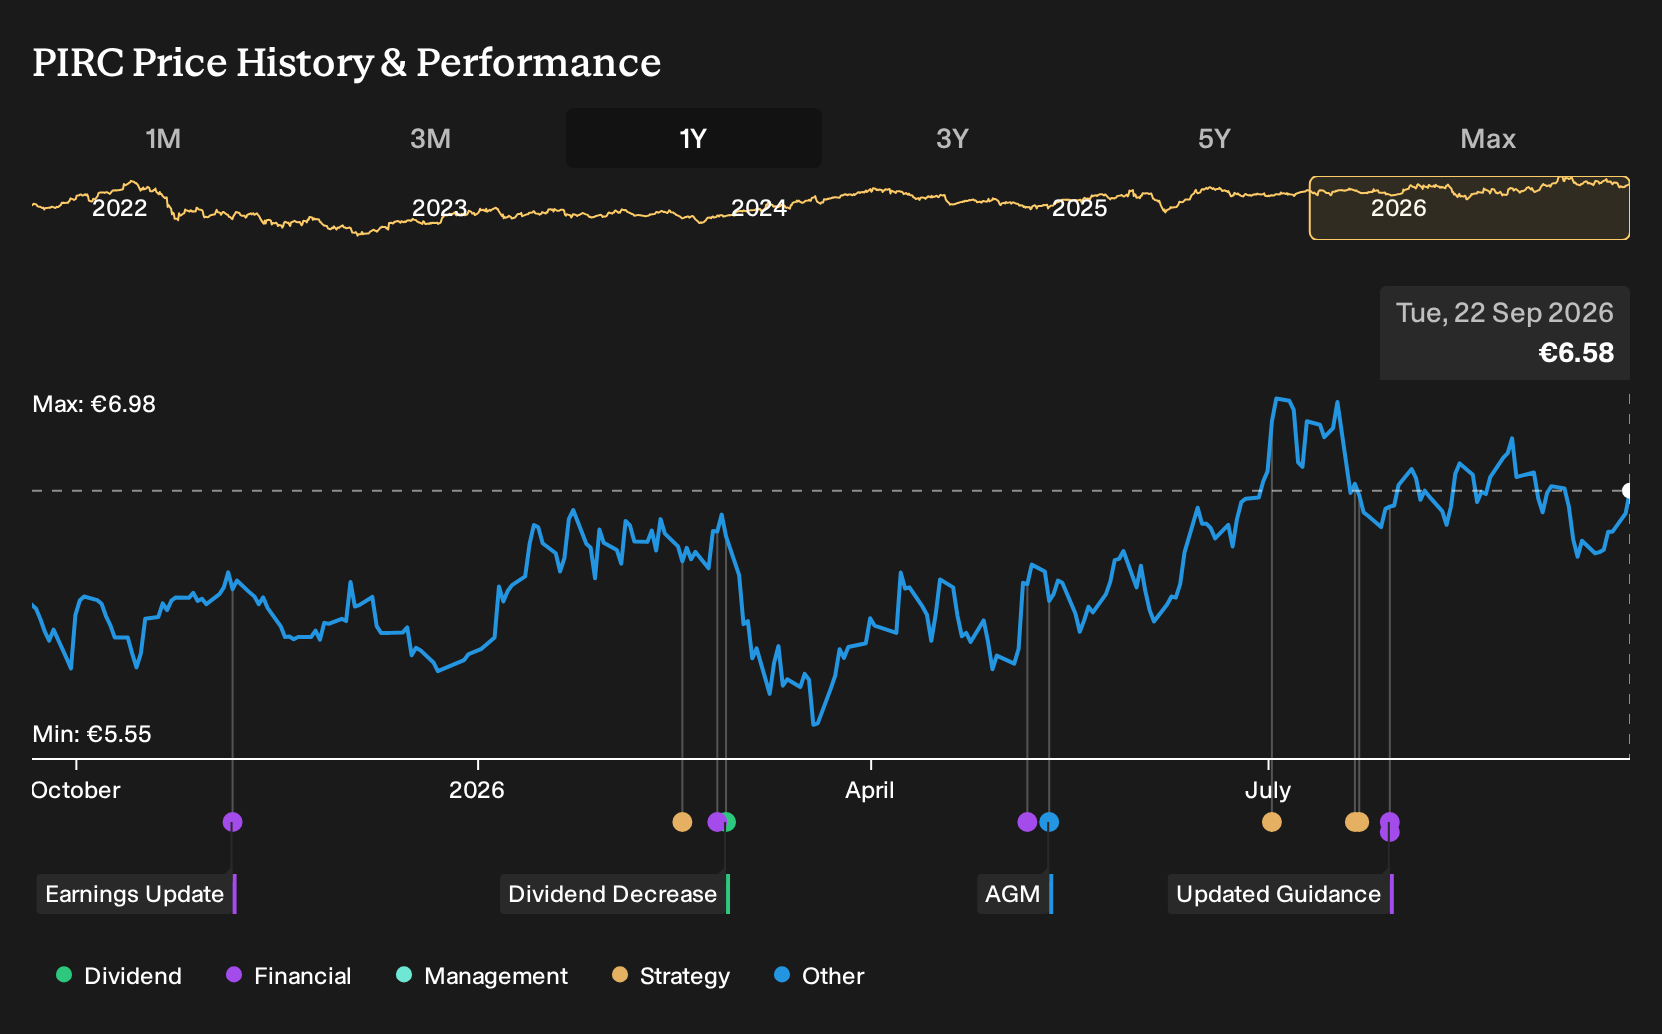
Discover how Pirelli & C's fair value points to a 7% potential upside to its current price, a discount that could close sooner than investors expect.
Exploring Other Perspectives
The Simply Wall St Community contributes 2 separate fair value views for Pirelli & C, clustering between €7.06 and about €7.85 per share. You are seeing only a narrow spread; however, those estimates do not reflect fresh motorsport contracts, Cyber Tyre trials or tariff and raw material risks. Use them as a starting point and compare several alternative viewpoints.
Explore another Pirelli & C fair value estimate, including one that suggests a potential upside of as much as 19% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pirelli & C research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Pirelli & C. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pirelli & C's overall financial health at a glance.
Looking for more investment ideas beyond Pirelli & C?
If you want to round out your watchlist beyond Pirelli & C, the Simply Wall St Screener can help you scan for different types of opportunities that fit your risk tolerance and income needs.
- For investors who care most about capital preservation and steadier ride quality, start with a basket of 230 resilient stocks with low risk scores that score well on resilience and risk metrics.
- If you prefer businesses with stronger balance sheets and fewer financial weak spots, filter for companies in the list of solid balance sheet and fundamentals (197 results) and compare how they stack up against Pirelli & C on debt and liquidity.
- Those hunting for under followed opportunities can scan the 615 high quality undiscovered gems and see which lesser known stocks have fundamentals that match your return and risk profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com