
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Heineken (ENXTAM:HEIA) Buyback And Pub Deal Chatter Build, Is It Still A Bargain?
Heineken share buyback and UK pub deal chatter put the stock in focus
Heineken (ENXTAM:HEIA) has come into focus after reporting fresh activity in its €1.5b share buyback programme, alongside renewed speculation about a potential acquisition of hundreds of UK pubs from Stonegate.
Heineken’s latest pub deal chatter and progress on its €1.5b buyback come after a mixed stretch for the shares. The 1-year total shareholder return of 12.45% is outpacing a year-to-date share price return of 3.91%, while the 3-year total shareholder return is down 8.92%. This suggests some recent momentum has rebuilt, but longer term holders have still seen value erode.
Scan how Heineken's latest buyback and pub deal speculation compares with other potential opportunities by reviewing the hand-picked 170 high quality undervalued stocks.
Heineken is buying back stock and is at the center of speculation about UK pub operators, yet the share price has only inched ahead this year. Is it worth stepping in now, or waiting for a clearer reset on valuation?
Most Popular Narrative: 20% Undervalued
Heineken last closed at €71.70, while the most followed narrative places fair value at €89.31. This points to a meaningful valuation gap built on specific growth, margin and capital return assumptions rather than sentiment alone.
Continued portfolio premiumization, including robust performance of global brands like Heineken, Amstel, and extensions such as Heineken Silver and 0.0, enables higher average selling prices and improved profitability, pointing to sustainable margin and earnings growth. Significant acceleration in low and no-alcohol beverage segments, with Heineken 0.0 seeing double-digit growth in challenging developed markets (e.g., U.S.) and opportunities for further adoption across both developed and emerging geographies, provides an additional high-margin, incremental revenue stream.
See why 41 investors see Heineken as 20% undervalued.
The narrative uses a 5.65% discount rate and assumes Heineken can reach €33.7b in revenue and €3.1b in earnings by 2029, with a future P/E of 17.6x, to support that €89.31 fair value. It also factors in risks such as slower European consumption, currency swings in emerging regions and higher input costs that could pressure profitability if execution slips.
Result: Fair Value of €89.31 (UNDERVALUED)
Still, the Heineken narrative can be knocked off course if currency swings hit earnings harder than expected or if demand for beer in mature European markets weakens further.
Find out about the key risks to this Heineken narrative.
Another View on Heineken’s Valuation
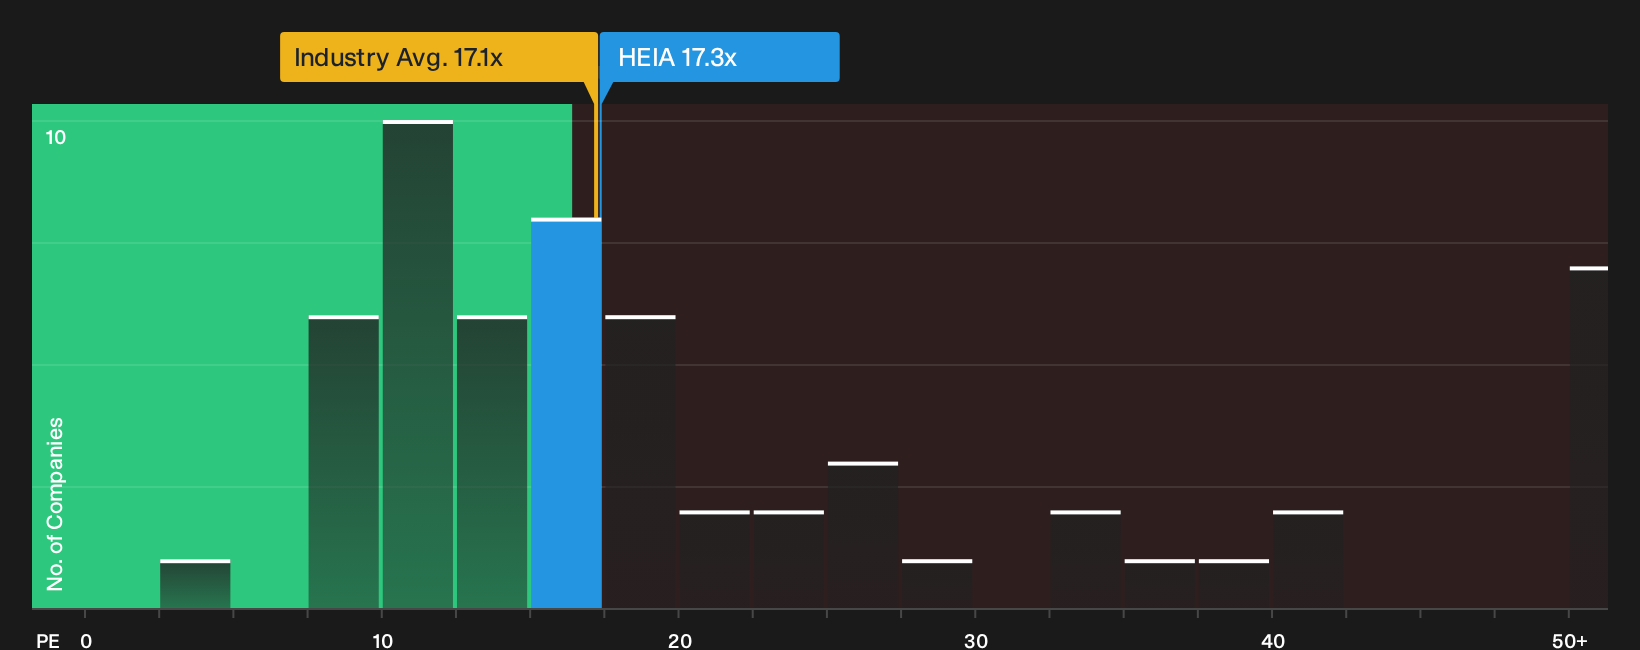
First method says Heineken looks undervalued versus its €89.31 fair value narrative. A simple P/E cross-check tells a different story. The stock trades on 17.3x earnings, which is slightly higher than the European Beverage sector at 17.1x, yet below a fair ratio of 21.7x that the market could move toward. That mix flags less of a clear bargain and more of a debate about how much valuation risk you want to carry.
To see how that trade off looks in hard numbers, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Heineken's valuation and deal chatter are one thing. Acting on them is another. Check the data yourself, weigh both the concerns and the brighter spots, and see what the 4 key rewards and 2 important warning signs really mean for your own view.
Looking for more ideas beyond Heineken?
If Heineken has your attention, do not stop there. Use the Simply Wall Street screener to uncover other opportunities that could fit your approach and time horizon.
- Target stronger income potential by reviewing high-yield opportunities in the 159 dividend fortresses that focus on resilience as well as payout.
- Hunt for quality at a reasonable price by scanning the 170 high quality undervalued stocks that blend solid balance sheets with attractive valuations.
- Seek out quieter opportunities by checking the 616 high quality undiscovered gems that pair robust fundamentals with lower profile market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com