
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
UPM-Kymmene Oyj (HLSE:UPM) Climbed, So What Is Drawing Attention Now?
UPM-Kymmene Oyj (HLSE:UPM) is stepping in front of investors at three consecutive conferences in New York, London and Stockholm, putting its forest-based bioindustry and energy operations under closer scrutiny for portfolio watchers.
For investors tracking the bigger picture, UPM-Kymmene Oyj’s share price has moved to €26.01, with a 1-month share price return of 9.89% and a 1-year total shareholder return of 17.36%. The 3-year total shareholder return shows a 4.23% decline, suggesting that recent momentum has picked up after a weaker stretch.
Compare UPM-Kymmene Oyj’s recent move with a curated field of resilient balance-sheet plays by scanning the list of solid balance sheet and fundamentals (197 results) alongside it.
After a sharp move to €26.01, the question is whether UPM-Kymmene Oyj still offers meaningful upside or whether the recent recovery already captures most of the easy gains. The valuation numbers give the clearest clues.
Most Popular Narrative: 5% Overvalued
The most followed valuation story for UPM-Kymmene Oyj puts fair value at €24.70, which sits below the latest close of €26.01, so the current price is ahead of that narrative.
The updated analyst price target for UPM-Kymmene Oyj has shifted from €26.27 to €24.70 as analysts factor in lower revenue growth and profit margin assumptions, alongside recent Street research that highlights downside earnings risk and concerns about valuation against softer pulp demand, even as some still point to potential benefits from lower Nordic wood costs and planned spinoffs.
See why 30 investors see UPM-Kymmene Oyj as 5% overvalued.
Result: Fair Value of €24.70 (OVERVALUED)
Still, the whole story for UPM-Kymmene Oyj can change quickly if wood costs in Finland stay elevated or if weaker pulp demand continues to pressure earnings expectations.
Find out about the key risks to this UPM-Kymmene Oyj narrative.
Another View: UPM-Kymmene Oyj Through A Cash Flow Lens
Analyst targets put UPM-Kymmene Oyj around fair value at roughly €24.70, yet our DCF model points in a different direction. On that framework, the shares at €26.01 trade about 45% below an estimated cash flow value of €47.31, which frames the stock as undervalued rather than slightly overvalued. Which story do you think better fits how UPM actually turns projects into long term cash?
Look into how the SWS DCF model arrives at its fair value.
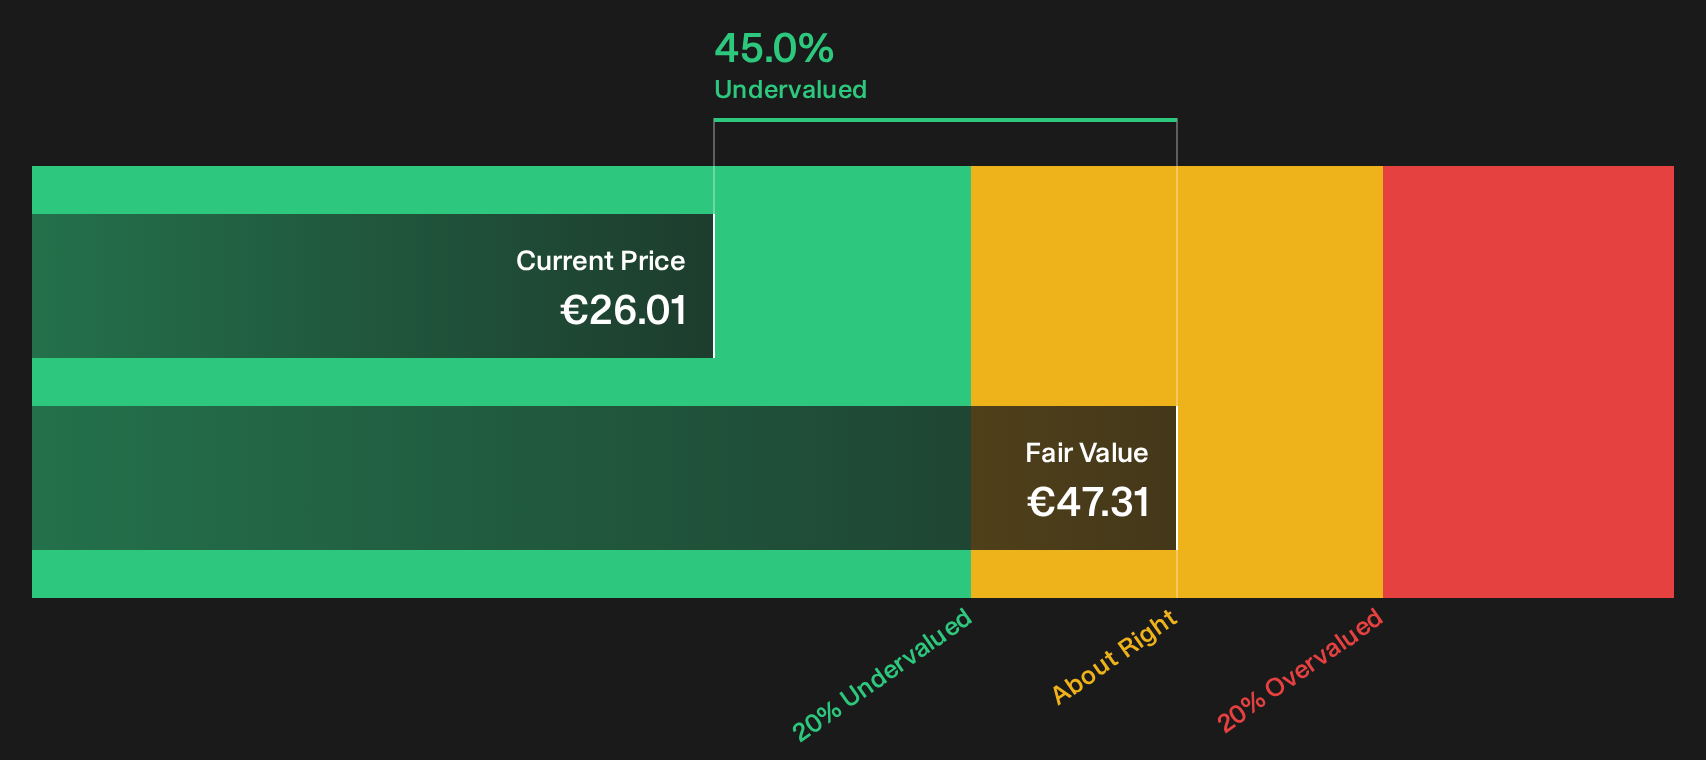
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out UPM-Kymmene Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 170 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on UPM-Kymmene Oyj so far. If you want to move fast and judge the balance of risk and upside for yourself, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond UPM-Kymmene Oyj?
If UPM-Kymmene Oyj has sharpened your focus on valuation, do not stop here. Use targeted screeners to surface other opportunities that might better fit your risk and income goals.
- Target resilient payouts by scanning for income ideas through the 159 dividend fortresses that prioritise yield and stability.
- Hunt for potential mispricings by checking the 170 high quality undervalued stocks that focuses on quality fundamentals at compressed valuations.
- Put capital to work in sturdier balance sheets by filtering with the 230 resilient stocks with low risk scores that highlights lower risk profiles and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com