
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Alleima (OM:ALLEI) Rolls Out AI Tube Inspection, Is The Upside Already Priced In?
Why Alleima’s AI quality project matters for shareholders
Alleima (OM:ALLEI) and Prevas have rolled out an AI driven machine vision pilot that automates tube surface inspection, replacing manual checks and tightening how defects are detected on the production line.
For investors, the project focuses attention on how automation, data and real time image analysis might influence Alleima’s cost base, product consistency and the risk profile attached to its Tube division revenue.
Momentum has been building in Alleima’s shares, with a 28.09% 90 day share price return and a 41.18% year to date share price return. The 1 year total shareholder return of 66.94% shows how strongly the recent AI and automation news lands on an already positive trend.
Scan beyond Alleima and Prevas by sizing up other industrials pushing AI and automation into real production with our curated list of 95 robotics and automation stocks.
Alleima now appears to be a more focused, increasingly automated business, and the share price already reflects much of that optimism. The more difficult question is whether today’s valuation matches the quality on display.
Most Popular Narrative: 22% Overvalued
Alleima last closed at SEK118.10 while the most followed narrative anchors fair value at SEK96.75, so the machine vision news lands on a stock that consensus models already view as stretched.
The company's continued shift toward high-margin, specialty and customized solutions (notably in Medical, Nuclear, and precision Strip), combined with ongoing automation and operating leverage initiatives, is positioning Alleima for structural net margin expansion and stronger earnings resilience as volumes recover and low value-add exposures diminish.
See why 10 investors see Alleima as 22% overvalued.
On that view, the current price implies expectations that sit above a fair value built on a 6.9% discount rate, 5.6% revenue growth assumptions and an 8.8% profit margin profile.
The narrative also points out that while analysts model better earnings and higher quality cash generation, their SEK96.75 target is still below the present share price, which suggests the market is already assigning a rich premium to Alleima's Tube, Kanthal and Strip divisions.
For anyone weighing the AI quality project against this backdrop, the key question is whether further automation genuinely improves earnings power enough to close the gap between SEK96.75 and SEK118.10, or whether expectations have simply moved faster than the underlying business.
Result: Fair Value of SEK96.75 (OVERVALUED)
Still, the narrative starts to wobble if weak demand in industrial and chemical markets persists, or if productivity issues in Alleima’s Strip division drag on longer.
Find out about the key risks to this Alleima narrative.
Another view on Alleima’s valuation
The analyst narrative paints Alleima as 22% overvalued at SEK118.10 versus a SEK96.75 fair value, yet our DCF model points in the other direction, with a future cash flow value of SEK136.11 and a 13.2% discount to that figure. Which lens feels more realistic to you?
Before leaning on either outcome, it can help to understand how the cash flow assumptions are built and stress test them against your own expectations for Alleima’s earnings path, margins and reinvestment needs over time, then see how comfortable you feel with the SWS DCF model sitting above the analyst target. Look into how the SWS DCF model arrives at its fair value.
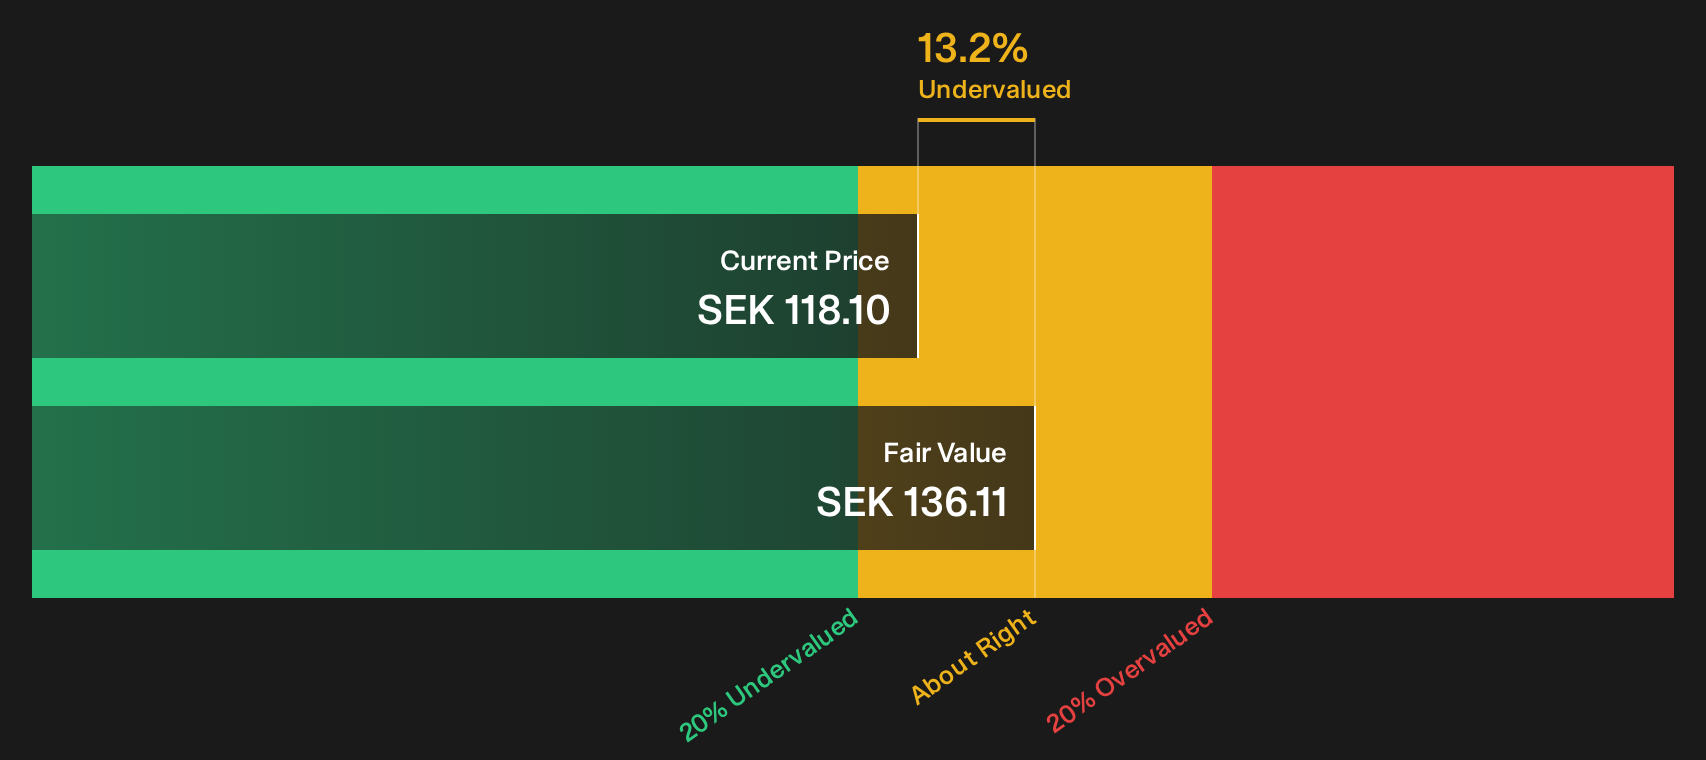
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alleima for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 170 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Alleima leaves you unsure, move quickly from reading to testing the numbers yourself. Start by weighing the 2 key rewards
Looking for more investment ideas beyond Alleima?
You have already done the hard work by digging into Alleima. Do not stop there; broaden your watchlist now while the numbers are fresh in your mind.
- Target dependable cash generators by scanning for robust balance sheets and consistent fundamentals using our list of solid balance sheet and fundamentals (197 results).
- Hunt for quality at a discount by reviewing companies that screen well on valuation and fundamentals through our 170 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with lower risk scores and steadier profiles in our 230 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com