
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OceanaGold And 2 Canadian Undervalued Stocks Picks
Interest rate hikes in the U.S. have made expensive borrowing a global story, and that matters for Canadian investors who care about cash. When money costs more, steady cash generation can become the difference between grinding through tighter conditions and scrambling to refinance. This article looks at three Canadian stocks where the current share price sits below what their cash flows suggest they might be worth, based on SWS DCF estimates.
The three stocks covered below are only a small sample, with the wider screen highlighting 0 more Canadian listed businesses with cash flow stories that also align with the SWS DCF approach but are not unpacked in this article.
If you want to identify and analyze the rest of this undervalued cash flow group directly, head straight into the Undervalued Stocks Based On Cash Flows screener.
OceanaGold (TSX:OGC)
Overview: OceanaGold operates producing gold and gold/copper mines in the United States, the Philippines, and New Zealand that drive the cash flows underpinning its DCF-based valuation in this screener.
Operations: The business generates revenue mainly from Haile at about $796 million and Macraes at about $781 million, with Didipio at about $549 million and Waihi at about $338 million rounding out its producing mines.
Market Cap: CA$9 billion
For investors focused on cash generation, OceanaGold matters here because its producing mines already generate the cash flows that anchor this screener’s DCF work.
Optimization and expansion at Didipio, including restoration of normal underground rates and a targeted 2.5 million tonne annual mining rate by 2026, is expected to increase copper and gold output from an already low cost asset, which would enhance consolidated cash flow and margins.
What really moves the needle for OceanaGold’s future cash profile is how one large, long life project ultimately shapes costs and profitability.
If that project outcome is what matters most to you, read the full narrative for OceanaGold to see how OceanaGold’s risk, capital needs, and upside potential compare.
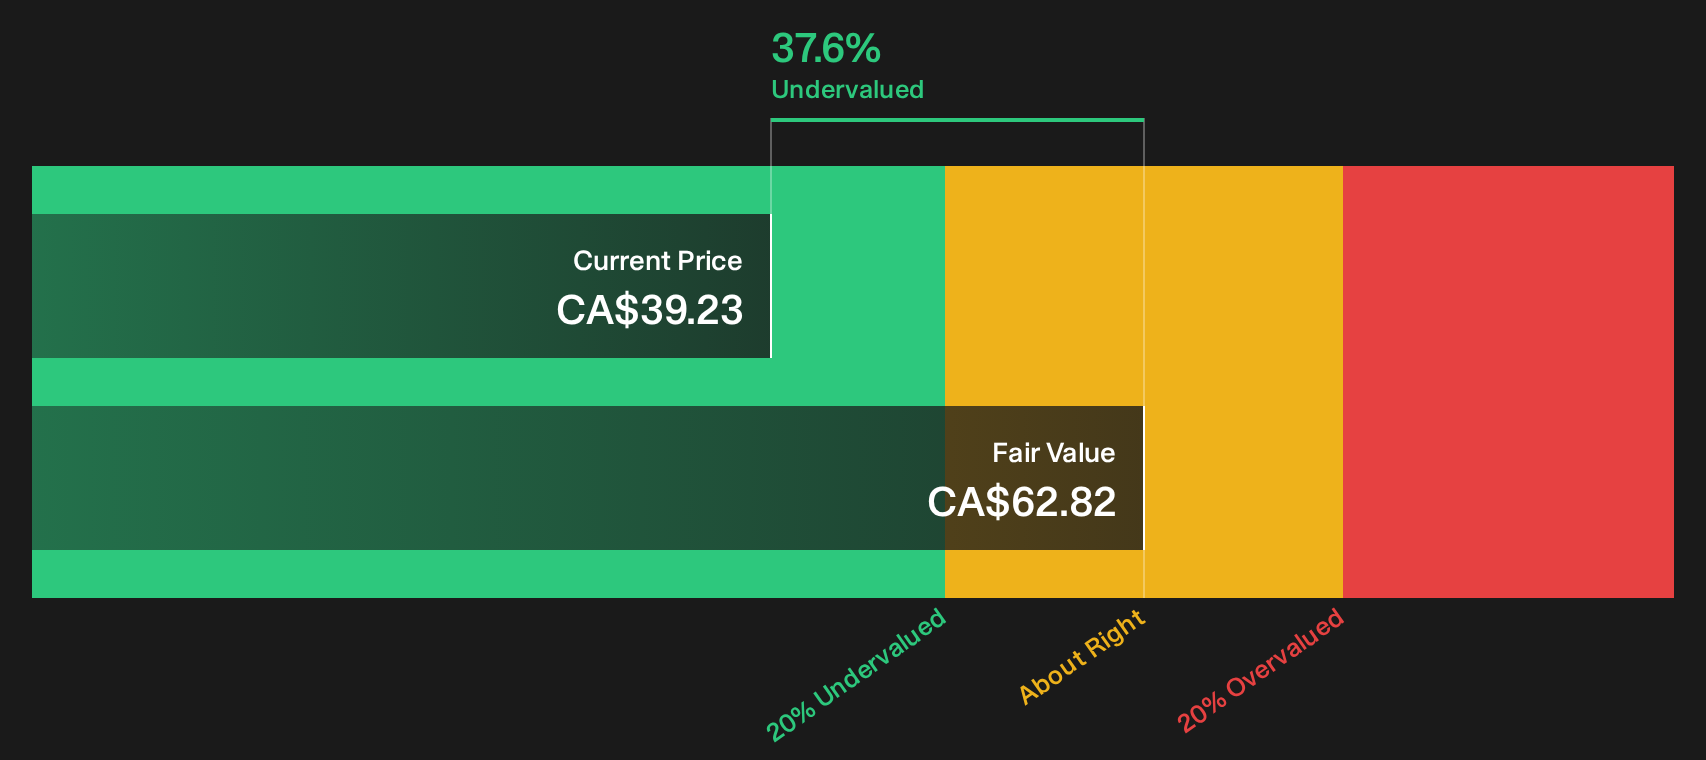
Savaria (TSX:SIS)
Overview: Savaria provides accessibility and patient handling equipment, with home and commercial elevators, stairlifts and adapted vehicles driving recurring service-based cash flows.
Operations: Savaria generates about CA$739 million from Accessibility including adapted vehicles and CA$209 million from Patient Care across Canada, the US and Europe.
Market Cap: CA$2.1 billion
Savaria matters for this cash flow focused screen because its accessibility equipment often leads to long-lived service, maintenance and parts income that can compound well beyond the first installation.
"Ongoing global demographic shifts, namely population aging and increased urban density, are expected to drive increased demand for home accessibility solutions (e.g., elevators, stairlifts), which may influence Savaria’s revenue over time."
What ultimately shapes the payoff for investors is how one quiet shift in profitability filters through that installed base into future cash generation.
That profitability shift is the fulcrum. Read the full narrative for Savaria to see whether rising service cash flows are accelerating or masking deeper risks.
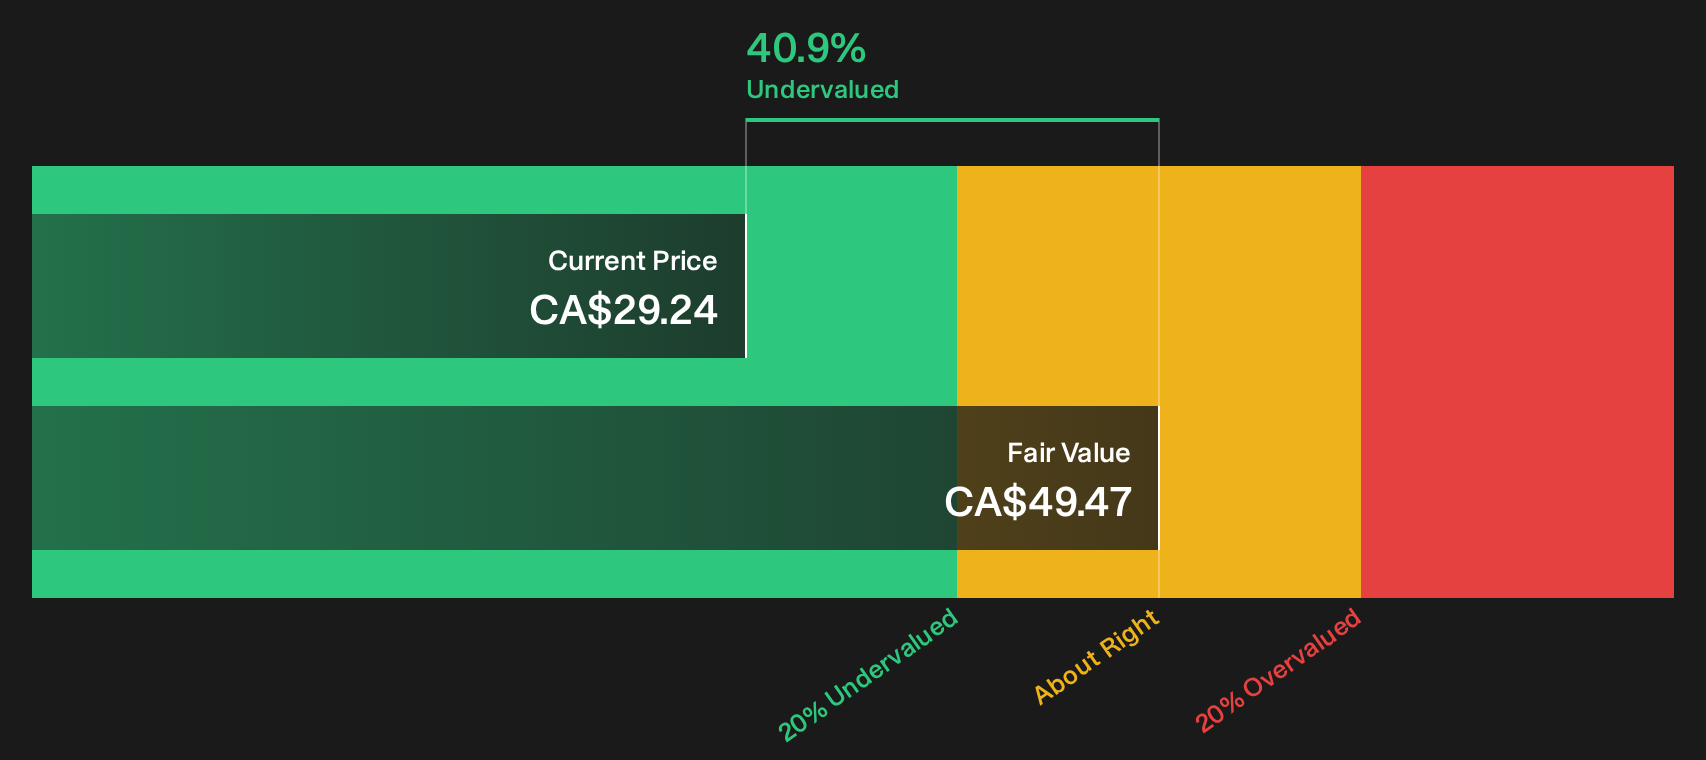
Suncor Energy (TSX:SU)
Overview: Suncor Energy is an integrated producer that turns Alberta oil sands bitumen into crude, fuels, and petrochemical products across its value chain.
Operations: Suncor Energy generates about CA$26.9b from Oil Sands, CA$36.8b from Refining and Marketing, and CA$2.5b from Exploration and Production.
Market Cap: CA$113.6b
For this cash flow focused screen, Suncor Energy matters because its oil sands operations feed a large, integrated refinery and retail system that can convert heavy crude into steady earnings across market cycles.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages. This could pressure volumes and compress margins if reliability slips from current record levels."
What really shapes the payoff for Suncor Energy now is how one growing strain inside that system ultimately filters through future margins and cash returns.
As that strain builds, read the full narrative for Suncor Energy to see whether Suncor Energy’s cash engine is quietly accelerating or if reliability risks are starting to bite.

Curious About Fresh Alternatives To Explore
Fresh ideas move fast. Breakout stories gather momentum while laggards keep dropping. Use these under the radar lists before the crowd catches on and pricing shifts, then act now.
- Spot resilient balance sheets before they get re rated by the market by scanning the curated list of solid balance sheet and fundamentals (7 results) that filters for strength while it still flies under the radar.
- Track the next stage of the AI build out by following power hungry infrastructure players inside the hand picked 86 AI infrastructure stocks while pricing still reflects last quarter, not the next potential breakout.
- Follow the new energy build cycle by checking the focused 40 power grid technology and infrastructure stocks that zeroes in on grid technology stories before momentum funds fully catch on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com